Applied Industrial Beats On EPS As Engineered Solutions Orders Surge, But Flat Guidance And A Slowing Service Center Temper The Upside
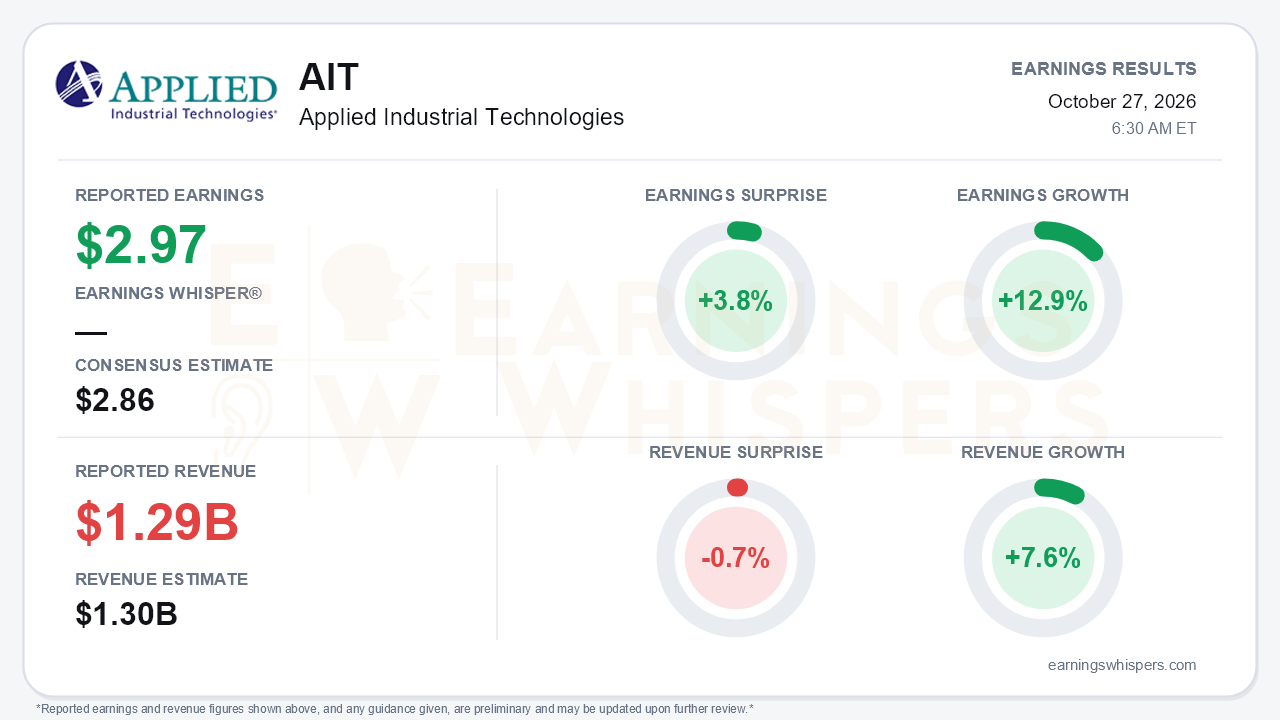
Applied Industrial Technologies (NYSE: AIT) opened fiscal 2027 with earnings of $2.97 per share, beating the $2.86 consensus by 3.8% and growing 12.9% year over year. Revenue rose 7.6% to $1.291 billion but came in 0.7% below the $1.30 billion consensus. That split points to the central tension. The bottom line was helped by margin discipline and a shrinking share count, and the order book in Engineered Solutions is accelerating at a pace not seen in years. Yet management left full-year sales and EBITDA margin guidance unchanged. The modest EPS raise was purely mechanical.
The quality of the beat deserves some scrutiny, though it largely holds up. Operating income rose 11.3% to $143.6 million and EBITDA rose 9.6% to $160.3 million. EBITDA margin reached 12.4%, the top of management's first-quarter guide. Gross margin expanded 25 basis points to 30.4%, or about 50 basis points excluding LIFO, a reversal from a 20-basis-point decline in the fourth quarter of fiscal 2026. That was achieved despite LIFO expense more than doubling to $5.6 million. Part of the EPS gain came from financial engineering, however. Diluted shares fell roughly 1.1 million year over year after another $80 million in buybacks, which helped per-share growth outpace the 9.5% rise in net income. Cash flow also softened. Operating cash flow fell to $86.4 million from $119.3 million on working-capital build, and free cash flow of $73.4 million represented only about 67% of net income. Net interest expense tripled to $3.1 million as the company drew on its revolver, and cash has dropped to $112 million from $419 million a year ago.
Beneath the consolidated numbers, the business is diverging sharply by segment. Engineered Solutions delivered 14.1% organic growth, continuing a steep climb from 0.5% two quarters earlier, then 9.3% and 12.9%. Segment EBITDA jumped 24.7% and margin widened 129 basis points to 15.1%. More importantly, segment orders rose more than 30%, accelerating from mid-20s growth in July, and book-to-bill hit its highest level in over four years. Within the segment:
- Automation grew more than 20% for a second straight quarter, with backlog up over 30%.
- Fluid power grew in the high teens, with backlog at a four-year high on semiconductor and data center demand.
- Flow control swung to better than 6% growth after a muted fourth quarter.
The Service Center segment tells a weaker story. Organic growth slowed to 3.5% from 8% in the prior quarter, although management attributed much of that to a tougher comparison. Segment EBITDA margin slipped 35 basis points to 13.6% on LIFO, a bad-debt provision comparison, higher health costs, and muted Canada and Mexico demand.
Forward indicators lean constructive. October organic sales are running about 10% month to date, and Service Center backlog is up roughly 20% year over year and 7% sequentially. Management also noted several mid-sized acquisition targets in due diligence. Bears still have legitimate ammunition:
- Second-quarter EBITDA margin is guided to 12.3%-12.5%, essentially flat with the first quarter despite stronger volume.
- November and December comparisons are about 200 basis points tougher.
- Incremental margin eased to 15% from roughly 19%.
- The number of top-30 end markets growing fell to 18 from 20.
- Full-year sales guidance of 4%-6.5% implies meaningful deceleration from the current run rate. Management attributes that caution to trade policy, geopolitics, and harder back-half comps.
Investors entered the report far less enthusiastic than they were last quarter. Earnings Whispers sentiment fell from 0.41 to 0.07, remaining barely positive but sharply weaker. Price action reflects the same fatigue. Shares hit a 52-week high of $374.80 on the day of the August report and have since slid to $324.68, down 11.3% from the post-report open and 13.4% below that peak. The stock sits about 5.1% above its 200-day moving average and just 4% above its September low of $312.25, leaving it in the lower part of its inter-earnings range. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative, consistent with a stock that has cooled without breaking down.
The disconnect is notable. The market spent the quarter de-rating AIT even as Engineered Solutions orders were accelerating. A report showing 30%-plus order growth, four-year-high backlogs, and a 10% October start addresses the demand concern that likely drove that pullback. Conservative guidance, however, leaves the upside case dependent on management eventually raising the outlook rather than on anything already promised.
The bottom line is that Applied delivered a high-quality operating quarter wrapped in cautious guidance. Engineered Solutions is the clear growth engine, while Service Center margins, weaker cash conversion, and buyback-aided EPS keep the headline beat from being as clean as it looks. With sentiment reset lower and shares well off their highs, the bar has come down. Whether order momentum translates into guidance increases later in the year is the key question for the stock.
Read our earnings preview for Applied Industrial Technologies: https://www.earningswhispers.com/article/AIT/20676
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| 12 hours | |
| Oct-07 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Jul-17 | |
| Jul-16 | |
| Jul-15 | |
| Jun-23 | |
| Apr-29 | |
| Apr-28 |
