Asbury Misses As Tekion Disruption Squeezes Margins, Leverage Rises And Buybacks Are Paused
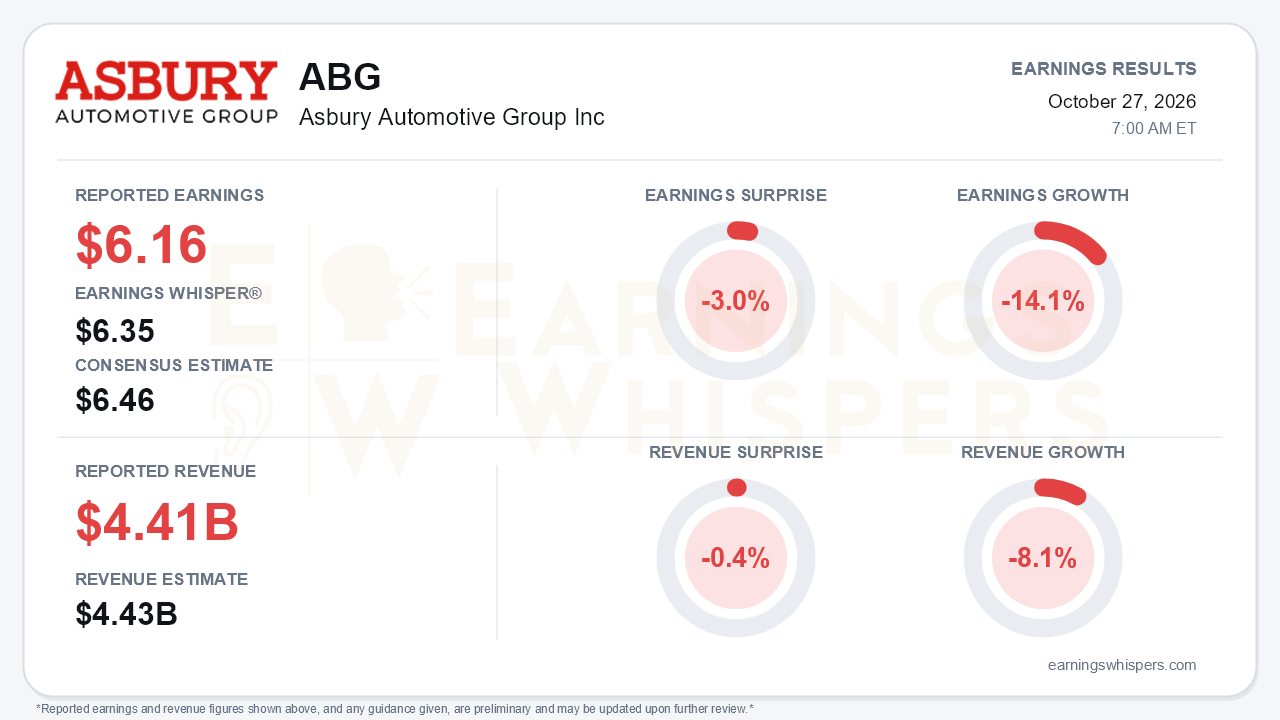
Asbury Automotive Group finished its most ambitious technology project, but the quarter's financial results still reflected the cost of getting there. Adjusted EPS of $6.16 fell short of the $6.46 consensus and the $6.35 Earnings Whisper number, a 3.0% miss, and earnings declined 14.1% from a year ago. Revenue of $4.414 billion was 0.4% below expectations and down 8.1% year over year. Sequentially, adjusted EPS slipped from $6.82 in the second quarter. The central tension is that management is asking investors to look through a trough to a 2027 recovery. In the same quarter, it raised leverage, stopped buybacks and pushed its deleveraging timeline out again.
The quality of the quarter deserves scrutiny beyond the modest headline miss. GAAP EPS of $5.84 compared with $7.52 a year earlier, but the prior-year figure included a $35.7 million divestiture gain, so the adjusted comparison is the cleaner read. Even that measure flattered per-share results. Adjusted net income fell 21% to $111 million, while diluted shares dropped to 18.0 million from 19.6 million, which cushioned EPS. That buyback tailwind is now going away. On a same-store basis, new-vehicle gross profit fell 20% as gross profit per unit dropped to $2,901 from $3,305. Import and domestic units were hit hardest. Same-store parts and service gross profit declined 2%, with margin down 181 basis points. Adjusted SG&A rose to 67.4% of gross profit from 64.2%, and adjusted operating margin compressed to 4.9% from 5.5%.
The call explained much of the damage as conversion disruption, and there is evidence the platform can deliver. The company converted 47 stores to Tekion in the third quarter, a record, and finished the remaining stores in October. In the longest-tenured markets, customer-pay gross profit rose 7% and gross per technician rose 9%, while the company overall was flat. Used vehicles were the clear bright spot. Used retail gross profit per unit rose 10% to $1,777, and all-store used volume rose 4.5% sequentially. Management expects year-over-year used volume growth in the fourth quarter. The miss on expectations management itself set is harder to dismiss. On the second-quarter call, management had expected SG&A as a share of gross profit to fall in the third quarter, but it rose to 67.4% from 66%. It had also guided to low-to-mid single-digit customer-pay growth, but customer pay was flat, repair-order count fell 1.9%, and post-conversion discounting compressed fixed-ops margins.
The forward story rests on a preliminary 2027 framework:
- fixed-ops growth back to mid-single digits;
- new-vehicle gross profit per unit of $2,750 to $3,000;
- used gross profit per unit around $1,750;
- SG&A exiting 2027 in the low 60s as a percentage of gross profit.
Management also floated a digital transaction initiative that could push SG&A below 60% in 2028-29. Dismissal of the FTC proceeding removes an overhang, and Total Care Auto is now in every store, with strategic options including a spin-out under evaluation. Bears have legitimate ammunition, however. Net leverage climbed to 3.5x from 3.4x in the second quarter. The sub-3x target has moved from summer 2026 to mid-2027, and full-year capex was raised to about $275 million from $250 million. Full Tekion benefits are not expected until late in the first quarter or the second quarter of 2027. Management also flagged other pressures:
- the TCA deferral cost $0.69 per share this quarter and will weigh on F&I into 2027;
- EV sales fell 76%;
- negative equity is emerging on pandemic-era trade-ins.
The market had already turned decisively against the stock before the report. Shares spiked to an inter-earnings high of $257.21 the day after the July report, then fell to a 52-week low of $160.30 on October 14. At $172.96 heading into earnings, the stock was down 26.4% from the post-July opening price. It sat just 7.9% above that low and 15.7% below its $205.21 200-day moving average. Investor sentiment flipped from mildly positive to mildly negative, falling from 0.13 to -0.14. That is a meaningful shift in expectations, though not an extreme reading. The Earnings Whispers price and AVWAP trend readings remain negative, while momentum and sequential growth are neutral.
That backdrop explains why the investment setup is more complicated than a 3% miss implies. Much of the bad news, including the Tekion disruption, new-vehicle margin normalization and leverage, was visible and arguably priced in. Still, the company has now missed its own near-term operating markers, and the per-share support from buybacks is gone until leverage falls.
The bottom line is that Asbury has removed two real overhangs, the Tekion conversion and the FTC case, and its used-vehicle and mature-Tekion data offer a credible recovery story. Investors are nonetheless being asked to trust a 2027 framework from a management team whose third-quarter expectations for SG&A and customer pay did not hold, and whose deleveraging timeline keeps slipping. Until fixed-ops growth and SG&A leverage actually show up in reported results, this remains a show-me story.
Read our earnings preview for Asbury Automotive Group Inc: https://www.earningswhispers.com/article/ABG/20674
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-06 | |
| Sep-25 | |
| Aug-31 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-17 | |
| Jul-09 | |
| Jul-07 | |
| Jun-22 | |
| Jun-18 | |
| Jun-01 |
