Avidbank Delivers Its Cleanest Quarter Yet, But A $270 Million Temporary Deposit Flatters The Print And Investors Turn Wary
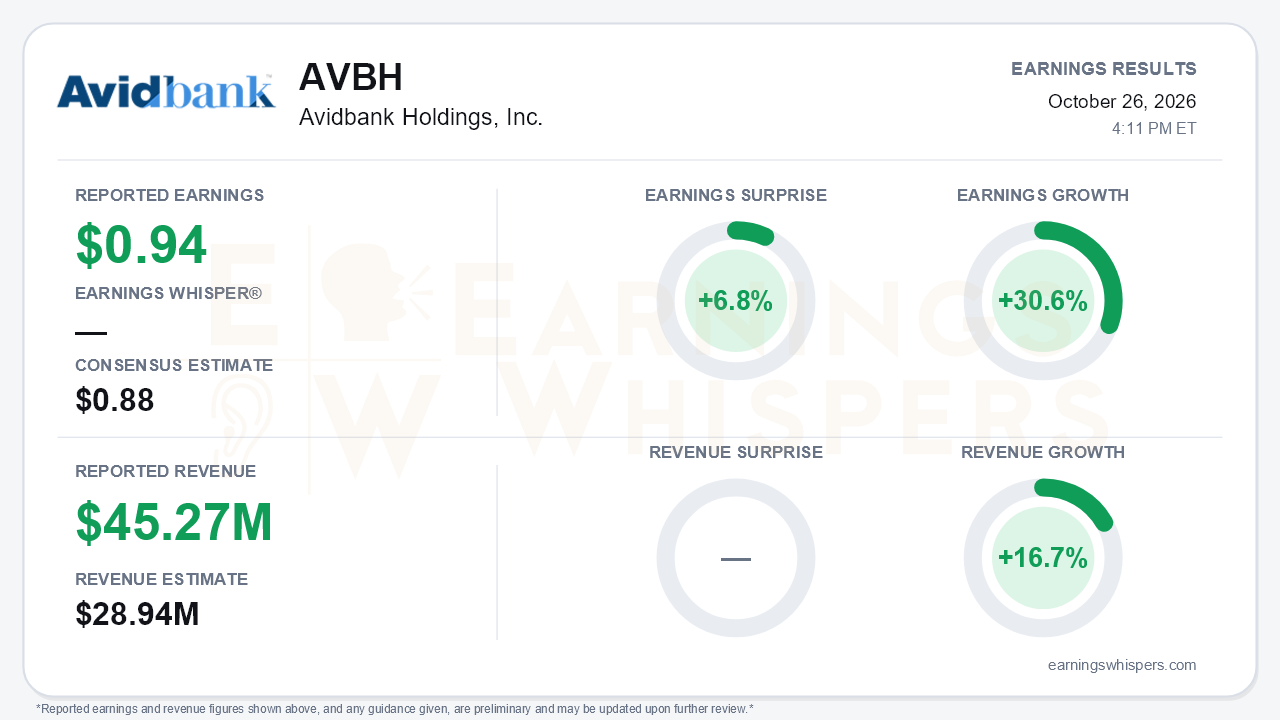
Avidbank Holdings (NASDAQ: AVBH) produced the most profitable quarter of its post-restructuring run. Third-quarter earnings of $0.94 per share beat the $0.88 consensus by 6.8% and grew 30.6% year over year. The comparison is especially stark on a GAAP basis: a year ago the bank booked a $37.7 million net loss tied to its securities repositioning. Sequentially, the trajectory accelerated. EPS rose from $0.71 reported, or $0.76 adjusted, in the second quarter and from $0.84 in the first. Return on average assets reached 1.42%, and return on equity climbed to 13.43%. That is the central tension: the quarter was clean and strong, but part of its strength rests on a balance-sheet event that management says will reverse within weeks.
The quality of the beat deserves scrutiny. Revenue of $45.27 million topped the $28.94 million consensus by 56.4% and grew 16.7%. That surprise appears to reflect total interest income measured against an estimate built closer to net revenue, so it says more about definitions than performance. Investors should anchor instead on net interest income, which rose $2.0 million sequentially to $28.7 million. Management attributed much of that gain to temporarily higher cash balances, alongside higher average loans and securities. Roughly $270 million of the quarter's $290.1 million deposit increase came from a single temporary client deposit expected to leave in the fourth quarter. The cash it created earned income but cut net interest margin by about 17 basis points, pushing it to 4.07% from 4.26% in the second quarter and 4.38% in the first. Encouragingly, the quarter carried no special items. Net charge-offs were essentially zero, against 35 basis points in the second quarter and 52 in the first, and that helped drive the provision down to $1.2 million.
Beneath the noise, the core franchise kept moving forward. Loans grew $58.4 million, a 10% annualized pace and 17% year over year, following $51 million in the second quarter and $24 million in the first. Growth was broad-based across C&I, multifamily and owner-occupied real estate, even as construction balances kept running off. Excluding the temporary deposit and brokered funds, core deposits grew about $76 million. Brokered deposits fell to roughly $10 million and mature in the fourth quarter. The efficiency ratio stayed below 50% for a second straight quarter, and management now frames that level as the ongoing standard. Book value per share rose to $27.24, up 9% year over year, despite a $0.85 per-share drag from accumulated other comprehensive loss as higher rates widened unrealized securities losses to $13.1 million.
Bears have legitimate ammunition on margin and costs. Management indicated that the normalized margin, excluding excess cash, sits in the low 4.20s and is drifting slightly lower. That is consistent with the 4.20%-4.25% path discussed earlier in the year, but it is not expanding. The spot cost of deposits excluding the temporary deposit rose to 3.13% from 3.07%, and management cautioned that deposit competition could pressure margins over time in a rising-rate environment. It is targeting a 40%-50% deposit beta. Core expenses rose $1.3 million on compensation and credit-related legal fees, headcount reached 171 versus 162, and fourth-quarter expenses were guided flat to slightly higher. Credit is mixed. Non-performing loans edged up to 0.70% after a $1.5 million land loan went to nonaccrual, and the entire NPL book now sits in construction and land. Classified loans climbed to 1.31% from 0.96%, although criticized loans fell to 1.68% from 2.16%.
The catalysts lean toward 2027. The September Fed rate hike should help fourth-quarter net interest income given the bank's asset sensitivity. The sub-debt refinancing is now complete, with $30 million of new 7% notes issued and $22 million redeemed. Management is targeting SBA preferred-lender status around the first quarter of 2027 and expects its new HOA and specialty deposit team to matter that year. A new president has been hired. Management described the fourth-quarter pipeline as strong but did not restate an explicit loan or deposit growth target, and it called construction payoffs the wild card.
The market setup is more complicated than the surprise implies. Earnings Whispers investor sentiment swung from essentially neutral, at 0.01, to decidedly negative, at -0.45, a meaningful deterioration heading into the print. Shares have gone nowhere: at $31.57 they are down 0.5% since the open after the July report, though they still trade about 3.7% above the 200-day moving average of $30.45. The internal trend readings are mostly neutral, with AVWAP negative, which fits a stock the market is treating with patience rather than conviction.
The bottom line is that Avidbank's underlying engine of loan growth, core deposit gathering, cost discipline and benign charge-offs looks healthier than at any point this year. However, the third quarter's peak profitability was partly borrowed from a deposit that is about to leave. The fourth quarter will show what normalized earnings look like with a low-4.20s margin, rising deposit costs and a still-elevated construction NPL book.
Read our earnings preview for Avidbank Holdings, Inc.: https://www.earningswhispers.com/article/AVBH/20642
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-07 | |
| Aug-26 | |
| Aug-06 | |
| Aug-03 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-14 | |
| Jul-06 | |
| May-29 | |
| Apr-29 | |
| Apr-27 |
