SNDL Misses On EPS As Retail Margins And Cash Flow Improve, But Cannabis Operations Unravel
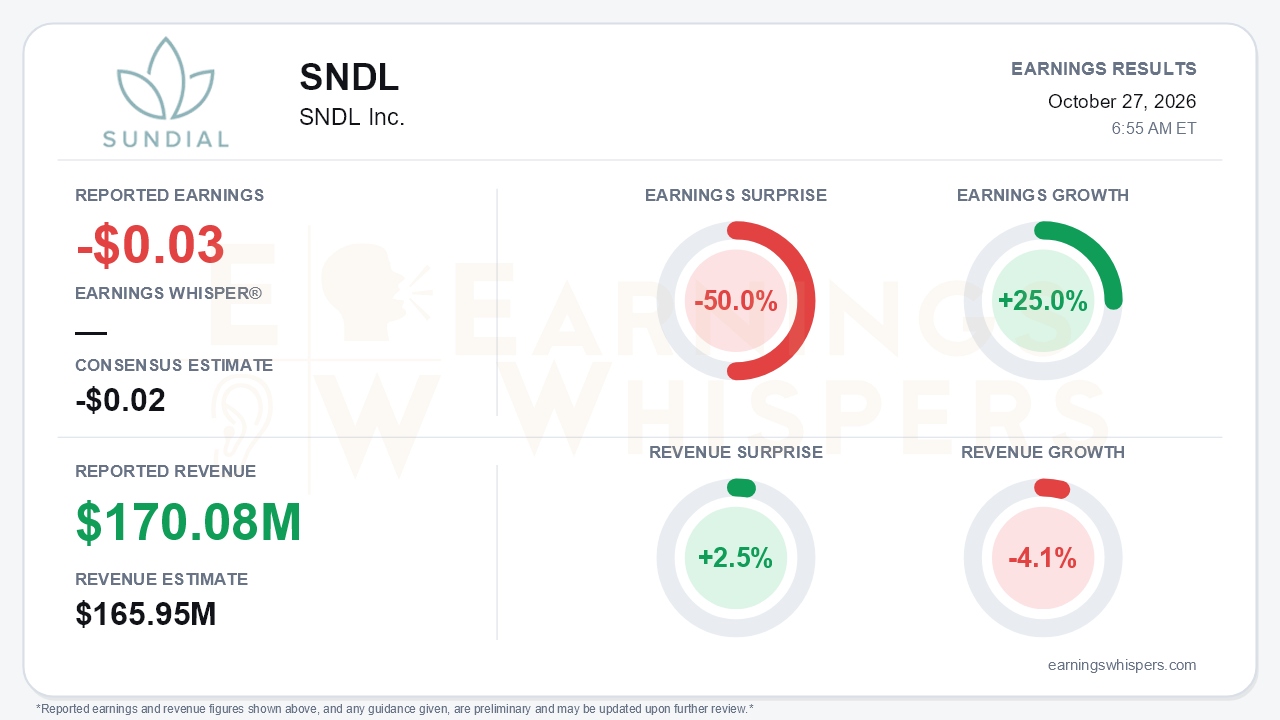
SNDL Inc. reported a third-quarter loss of $0.03 per share, missing the -$0.02 consensus by 50.0%, even as the normalized result improved 25.0% from a year ago. Revenue of $170.08 million beat the $165.95 million consensus by 2.5% but fell 4.1% year over year. The press release reported net revenue of C$238.0 million, down 2.5%, because SNDL reports in Canadian dollars. Earnings Whispers' normalized revenue appears to reflect a U.S.-dollar translation. The central tension is clear: SNDL's retail and corporate engine produced its cleanest quarter in some time, while its manufacturing business deteriorated badly enough to trigger a goodwill write-down and a strategic review.
The quality of the quarter depends on which line investors read. On an IFRS basis, the net loss widened to C$50.8 million from C$13.3 million, and the operating loss reached C$48.3 million. Both were driven by a C$52 million non-cash goodwill impairment in Cannabis Operations. That GAAP deterioration sits awkwardly beside the improvement in normalized earnings, and the gap is almost entirely the impairment. Excluding it and restructuring costs, adjusted operating income swung to a positive C$5.2 million from a C$9.5 million loss a year earlier and a C$7.0 million loss in the second quarter. However, roughly C$9.9 million of that swing came from lower corporate costs, including share-based compensation falling to C$1.8 million from C$10.9 million. Free cash flow hit a record C$20.0 million, but C$10.6 million came from a one-time unwind of the captive insurance arrangement. Adjusted EBITDA actually declined to C$15.8 million from C$18.1 million.
Beneath the consolidation noise, the two retail businesses are doing what management promised on margins. Both Cannabis Retail and Liquor Retail posted record 27.0% gross margins. Cannabis Retail revenue returned to growth at a record C$85.6 million, up 0.7% after a 1.4% decline in the second quarter. Demand, however, has not recovered. Liquor same-store sales fell 6.0%, essentially unchanged from -6.2% and -6.1% in the prior two quarters. Cannabis Retail same-store sales fell 3.8%, with new stores and Value Buds conversions masking market contraction in Ontario and Alberta. The second-half market recovery management flagged earlier in the year is barely visible. Retail growth is coming from footprint and margin, not traffic.
Cannabis Operations is where the story broke. Segment revenue fell 27.7% to C$27.0 million, an acceleration from declines of 10.1% and 14% in the prior two quarters. Gross margin collapsed to -6.0% from 1.8% in the second quarter and 19.7% in the first. Management blamed the exit from domestic dried flower, inventory adjustments and Jeeter cost variances. In response, it cut more than 30% of the Kelowna workforce and launched a review that could include divestitures. A segment once framed as an increasingly important driver is now being shrunk or sold, and the expected fourth-quarter cost benefits remain unquantified.
The forward catalysts are increasingly strategic rather than operational:
- **Parallel:** After Parallel's restructuring and rights offering, SNDL's indirect equity interest rose to about 92% from 67%. Management is exploring direct consolidation of its roughly US$150 million medical business.
- **Ontario:** A pending AGCO resolution should restart Value Buds franchise growth in the province. It will also deconsolidate about C$105 million of trailing revenue, though management expects to substantially preserve SNDL's net economics.
- **Capital returns:** A proposed substantial issuer bid of up to C$50 million, capped at C$1.92 per share (US$1.35), could retire more than 10% of the share count. It follows roughly 23 million shares already repurchased this year.
The cost of that ambition is visible in the cash balance, which fell C$50.7 million in the quarter on C$60.8 million of U.S. investment contributions. SNDL still carries no debt and about C$618 million in cash, securities and investments.
Investor sentiment improved meaningfully into the report, moving from slightly negative (-0.04) to modestly positive (0.20). The tape has been less enthusiastic. At $1.27, shares are down 1.6% since the open after the July report and sit 9.4% below their $1.40 200-day moving average. They are also 13.0% below the inter-earnings high of $1.46. The stock set a 52-week low of $1.13 on October 13 and has since rebounded 12.4%. The AVWAP trend reading is positive, consistent with that recent bounce, though price momentum remains neutral.
The bottom line is that SNDL's quarter was better than its EPS miss and GAAP loss suggest, but less clean than its record cash flow implies. Retail margins, corporate cost discipline and aggressive buybacks give the bull case real substance. Still, one-time items flattered cash generation, demand remains soft, and Cannabis Operations is in active retreat. With a buyback priced near the current share price and a Parallel consolidation still taking shape, the investment case now rests more on capital allocation and U.S. optionality than on organic growth.
Read our earnings preview for SNDL Inc.: https://www.earningswhispers.com/article/SNDL/20726
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-15 | |
| Oct-14 | |
| Oct-06 | |
| Aug-08 | |
| Aug-04 | |
| Aug-02 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-15 | |
| Jun-15 | |
| May-27 | |
| May-27 |
