ITW Falls Short Of The Whisper, But Accelerating Capex And AI Demand Drive A Third Guidance Raise
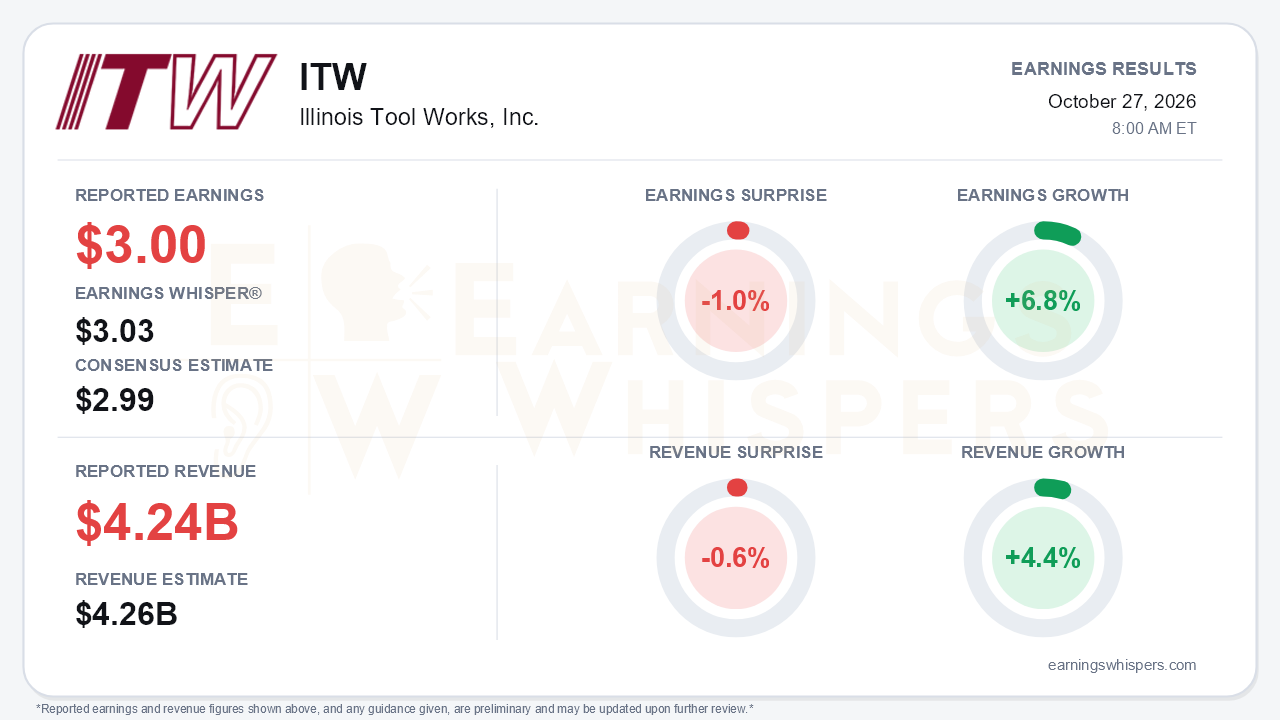
Illinois Tool Works reported third-quarter GAAP earnings of $3.00 per share, edging past the $2.99 consensus but falling short of the $3.03 Earnings Whisper number by 1.0%. Revenue of $4.236 billion missed the $4.26 billion consensus by 0.6%. Earnings grew 6.8% year over year and revenue grew 4.4%, both solid but unspectacular figures. Two things sit beneath the narrow miss. Much of the shortfall traces to a late-July tornado and a higher tax rate. Meanwhile, the demand picture in ITW's capex-linked businesses is strengthening faster than the headline suggests. That gap between a modestly disappointing print and an improving operating trajectory is the central story of the quarter.
The quality of the quarter is better than the surprise figure implies. Tornado damage at two Welding facilities cut an estimated $40 million, or about one point, from revenue. Excluding that hit, organic growth would have been roughly 5% instead of 3.8%, ahead of the 4.5% posted in the second quarter rather than behind it. On the earnings line, the effective tax rate rose to 24.4% from 21.8%. The prior-year quarter had benefited from a $27 million net discrete tax item, and management estimated the higher rate cost about $0.10 per share. Operating income reached a record $1.18 billion, and operating margin expanded 40 basis points to 27.8%, with enterprise initiatives contributing 130 basis points. There were helpers too. Other income rose to $37 million from $12 million, and the diluted share count fell about 2%. Even so, the core operating performance was clean.
The call made clear where momentum is building. Test & Measurement and Electronics organic growth has climbed from 2% to 5%, then 10%, and now 16%. Electronics alone grew 31% on AI-driven printed-circuit-board and semiconductor fab demand, and orders are running well ahead of revenue. Segment margin jumped 330 basis points to 28.7%. Welding grew 7% as reported and about 15% excluding the tornado, with orders surging and backlog building. Polymers & Fluids grew 8% with a record 31.3% margin. Food Equipment has improved steadily from -3% in the first quarter to +1%, and North American orders are up mid-single digits. Customer-Back Innovation is now projected to contribute 3%-plus to growth this year, up from 2.4% in 2025, reaching the company's 2030 target years early.
Bears have legitimate ammunition elsewhere. Automotive OEM organic revenue fell 2% and its margin dropped 170 basis points. Construction Products swung from +2% to -1% organic, also with 170 basis points of margin compression, and Specialty Products slipped from +2% to -1%. Raw material inflation of 4% to 5% is squeezing these consumer- and auto-facing businesses. Companywide, price/cost has drifted from "modestly accretive" early in the year to roughly neutral. China turned negative at -2%, and Europe was flat. Cash generation also softened. Operating cash flow fell to $953 million from $1.02 billion as receivables and inventories grew, and full-year free cash flow conversion guidance was trimmed to about 100% from above 100%.
Guidance carried the more constructive message. ITW raised the midpoint of its full-year GAAP EPS outlook for the third time this year, to $11.50 within a narrowed $11.45 to $11.55 range, implying 10% growth. Total revenue growth guidance rose to 4.5% to 5.5%, though that increase is currency-driven. Organic growth guidance of 3% to 4% was held despite the tornado, which implies fourth-quarter organic growth above 5%. Management expects fourth-quarter margins in the mid-to-high 27s, holding flat sequentially instead of declining seasonally. One caveat: the 26.5% to 27.5% full-year margin range was left unchanged for a third consecutive call even as the growth outlook improved. Early framing for 2027 points to incremental margins of 40%-plus and a normalized 10 to 20 basis point price/cost contribution.
The market setup is more complicated than the fundamentals alone suggest. Shares entered the report at $276.22, down 7.5% from the open following the July report and 8.5% below the inter-earnings high set that day. They had rebounded about 8% from an October 1 low of $255.69 and sat 2.3% above the 200-day moving average. Investor sentiment remained negative and weakened, slipping from -0.19 to -0.29. Momentum and AVWAP trend readings are positive, but the broader posture is cautious. Expectations were not euphoric, yet the elevated whisper shows some investors were looking for more.
The bottom line is that ITW's narrow miss against the whisper says less about the business than the tornado, tax and price/cost noise around it. Capex- and AI-linked demand is accelerating, guidance moved higher again, and the implied fourth-quarter organic growth rate is the strongest of the year. The risks are real but concentrated in automotive, construction, and cash conversion. Whether investors reward the improving mix will likely depend on ITW delivering that implied fourth-quarter step-up.
Read our earnings preview for Illinois Tool Works, Inc.: https://www.earningswhispers.com/article/ITW/20707
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 11 hours | |
| 11 hours | |
| Oct-15 | |
| Oct-09 | |
| Sep-16 | |
| Sep-09 | |
| Aug-27 | |
| Aug-21 | |
| Aug-18 | |
| Aug-12 | |
| Aug-07 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 |
