SunCoke Beats Easily And Lifts Its Outlook A Third Time, But The Q4 Math Points To A Step Down Rather Than Continued Momentum
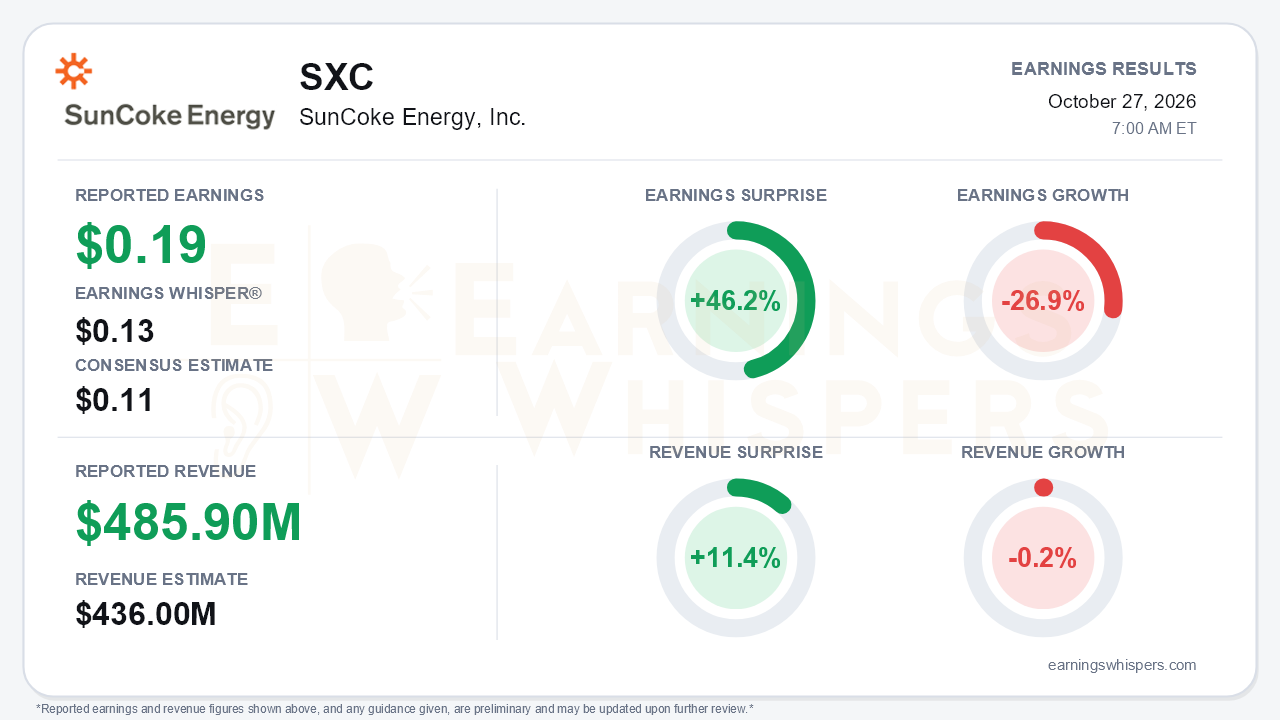
SunCoke Energy delivered a clean beat on the numbers that matter most to this name. Earnings Whispers-normalized EPS of $0.19 topped the $0.11 consensus by 46.2% and cleared the $0.13 Whisper number. Revenue of $485.9 million beat the $436.0 million consensus by 11.4%. Year-over-year comparisons are less flattering: earnings fell 26.9% and revenue slipped 0.2%. Reported GAAP diluted EPS was $0.25 versus $0.26 a year ago. That figure includes $6.9 million of property insurance recoveries tied to the 2023 Jewell flood, which helps explain the gap between the GAAP and normalized results. The more telling figure was Adjusted EBITDA of $76.9 million, up from $59.1 million a year ago and the best quarter of 2026. It also extended a clear sequential climb from $56.5 million in Q1 and $69.6 million in Q2. The central tension is that operating momentum and guidance are improving while per-share earnings, coke volumes and parts of the Q3 strength are less durable than the headline suggests.
The quality of the beat deserves scrutiny. Industrial Services did the heavy lifting. Segment EBITDA rose to $32.1 million from $18.2 million, but much of that gain reflects an extra month of the acquired Phoenix business rather than purely organic growth. Terminal volumes did help, rising to 6.4 million tons from 5.2 million and staying elevated rather than normalizing as the prior quarter had implied. Domestic Coke EBITDA increased to $51.1 million, and EBITDA per ton jumped to $58.40 from $46.27. That came despite sales volumes falling to 875,000 tons from 951,000 after the Haverhill I shutdown. The per-ton expansion came from a favorable contract/spot mix and seasonal coal-to-coke yields, and management conceded these were partly timing-driven. Corporate costs also doubled to $6.3 million. Year-over-year EPS fell largely because the prior-year quarter included capital investment tax credits, a $18.8 million tax benefit versus an $8.3 million expense this year.
Guidance is where the call preserved a credible story. Consolidated Adjusted EBITDA is now expected to modestly exceed the high end of $250-$265 million. That marks the third consecutive upgrade from an original $230-$250 million range. Industrial Services is expected to top its $110-$115 million range, and Domestic Coke is tracking toward the high end of $172-$178 million. Free cash flow guidance rose to $180-$185 million from an original $140-$150 million, helped by the October settlement with Algoma Steel. Management says that settlement made SunCoke whole and removed a working-capital overhang that had inflated receivables. The balance sheet is moving the right way: Q3 operating cash flow of $94.8 million funded a $53.5 million revolver paydown, and gross leverage of 2.34x sits below the 2.45x year-end target.
Bears still have legitimate ammunition. With year-to-date Adjusted EBITDA at $203.0 million, the guidance implies a fourth quarter in the low $60 million range. That would be a noticeable step down from Q3, and management guided Industrial Services softer, somewhere between Q1 and Q3 levels. The Middletown turbine insurance recovery, previously built into the second half, has been pulled from guidance and could slip into 2027. Management argues the Algoma settlement roughly offsets that loss, and it notes that a 2026 receipt would push results significantly past the high end. The bigger overhang is contract renewal risk. The Convent Marine Terminal agreement with Javelin and the Granite City agreement with U.S. Steel both expire in December 2026, and management described both as still in active discussions with no renewals announced.
Investors had already been warming to the story. Earnings Whispers sentiment improved sharply from -0.44 to -0.07, moving from clearly negative to roughly neutral without turning positive. The price action tells a similar story of recovery. Shares sank to $7.47 on the day of the July report, then rallied to a 52-week high of $10.68 in early September. They entered this report at $9.81, 4.6% above the post-July open, 19.3% above the 200-day moving average and about 8% below that September peak. Most Earnings Whispers trend readings are positive, though sequential growth remains the exception.
The bottom line is that SunCoke turned in a genuinely strong operating quarter, raised its outlook again, and removed the Algoma uncertainty, all while deleveraging faster than planned. Still, the beat leaned on acquisition timing, favorable coke mix and seasonal yields, and the implied Q4 points lower. The year-end CMT and Granite City renewals now matter more to the investment case than another guidance nudge.
Read our earnings preview for SunCoke Energy, Inc.: https://www.earningswhispers.com/article/SXC/20729
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| Oct-15 | |
| Sep-17 | |
| Sep-16 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Apr-30 | |
| Apr-30 | |
| Apr-30 |
