Advantage Solutions Must Prove Its Second-Half Rebound Is Real After Retailer Margin Stumble
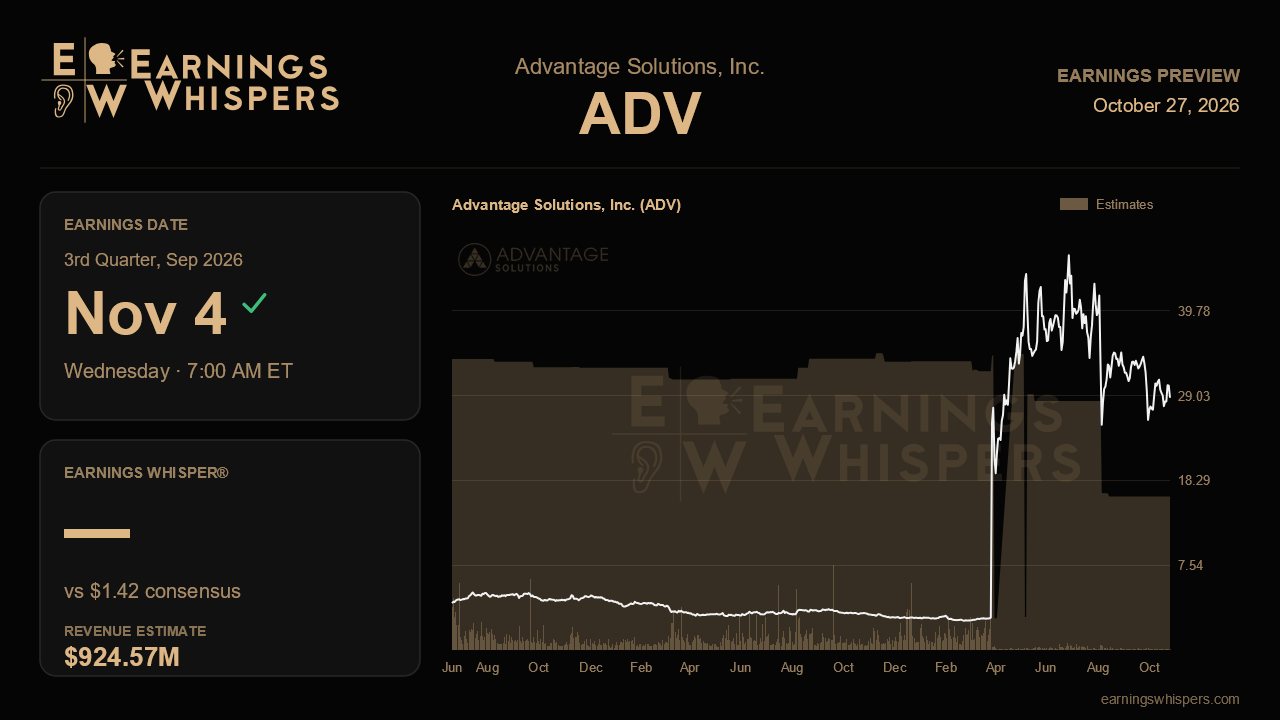
Advantage Solutions heads into its third-quarter report with a promise to keep. Three months ago, management reaffirmed its full-year outlook even as retailer services margins cracked and the branded business slid further. Its explanation was that the second quarter's problems were temporary and that all three segments would improve in the back half of the year. The November 4 release, due before the opening bell, is the first real test of that claim. A stock that has lost nearly a quarter of its value since the last report suggests many investors are not taking it on faith.
The Street expects revenue of about $924.6 million, up roughly 1% from $915.0 million a year ago and a solid step up from the $889.5 million posted last quarter. Consensus earnings stand at $1.42 per share, against just $0.06 in the year-ago period. That works out to an eye-popping expected growth rate, but the comparison mostly reflects a tiny base, and the basis of the estimate is unclear. It would be a mistake to read it as a sign of a dramatic operating inflection. The bigger signal is the revenue line. Management still targets 2026 revenue of $3.54 billion to $3.67 billion, and full-year consensus of $3.55 billion sits right at the bottom of that range. Analysts are effectively granting the guidance without leaving room for upside. A quarter that leaves the company tracking toward the low end would be tolerated. Anything that calls the floor into question would not.
Retailer services is the swing factor. Adjusted EBITDA in that segment fell about 25% in the second quarter after growing 14% in the first. Management blamed project timing, a large one-time project in the prior-year period, and startup costs on new work. If those explanations hold, third-quarter margins should recover visibly, helped by an easier comparison. A second straight quarter of double-digit profit declines would make the one-off framing much harder to defend. It would also put pressure on the reaffirmed adjusted EBITDA outlook, since total adjusted EBITDA swung from 16% growth in the first quarter to a 12% decline in the second.
Branded services needs to show it has stopped getting worse. Revenue there fell 13% last quarter, and management conceded the recovery is taking longer than expected, a retreat from earlier talk of stabilization. The more encouraging thread is merchandising project work for consumer goods clients. It rose to about a quarter of branded activity, and project revenue climbed more than 20%, which management flagged as a possible leading indicator. If that indicator is real, the decline should narrow this quarter. Experiential services has been the reliable engine, with revenue up 19% and event volumes up 18% last quarter. Investors should want growth to stay in the high teens, because that segment is carrying the rest of the company.
Cash flow deserves attention as well. Unlevered free cash flow conversion dropped to 25% in the second quarter from 110% in the first, as the final phase of an SAP implementation stretched collection times. Hitting the reaffirmed $250 million to $275 million target requires that working-capital drag to reverse. Updates on the new Chief AI Officer's efficiency pilots, the Pulse execution system and continued buybacks would help, but they are secondary to the cash numbers.
Sentiment is mildly bullish and essentially unchanged from last quarter, so the selloff reflects lost conviction rather than a crowd turning bearish. The shares trade at $28.76, comfortably above the 200-day moving average and the post-report low of $22.08. They remain well below the $38.95 high and far beneath last quarter's range in the $30s and $40s. That leaves room for relief if the second-half recovery shows up in retailer margins, branded trends and cash conversion. If it does not, the reaffirmed guidance will look less like confidence and more like a deadline approaching.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-22 | |
| Jun-26 | |
| Jun-16 | |
| May-06 | |
| Apr-22 | |
| Mar-09 | |
| Mar-03 | |
| Mar-03 |
