After Its Vepinu Windfall, Arvinas Must Show A Thinner Pipeline Can Still Deliver
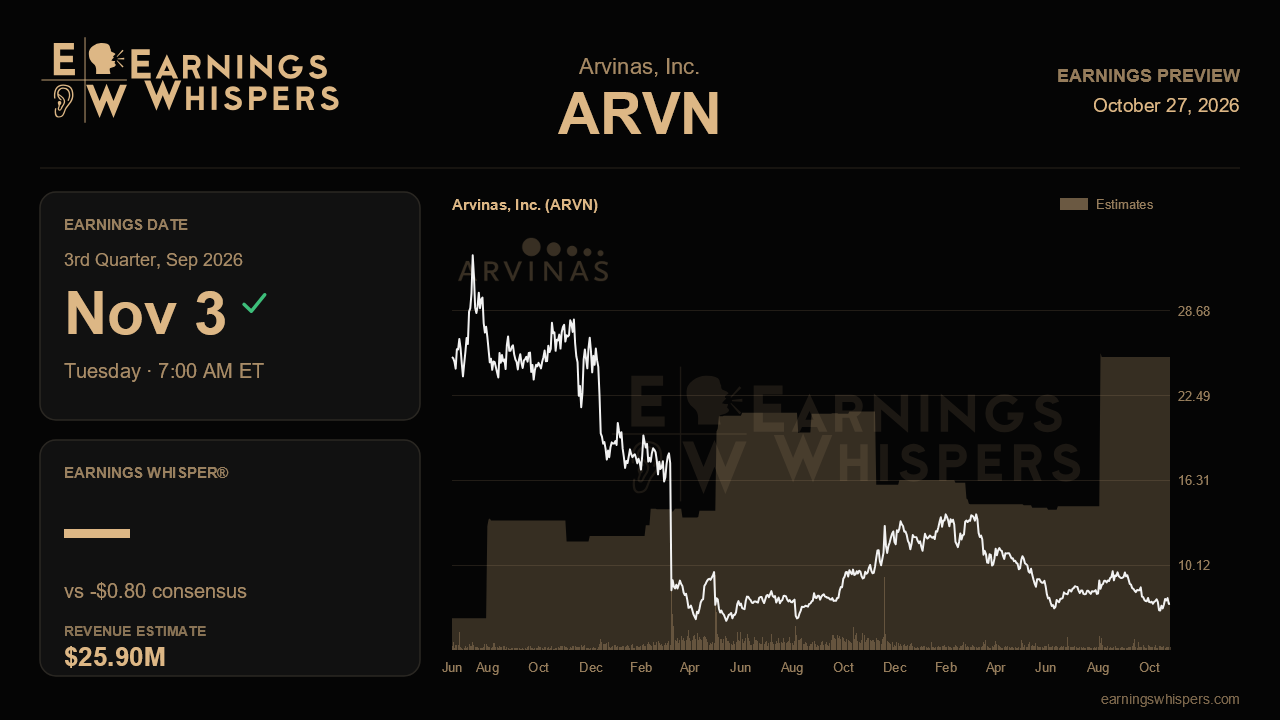
Arvinas just posted the best quarter in its history, and the market has spent the time since marking the stock down. The $249.7 million in second-quarter revenue and $2.58 per share in profit came almost entirely from one-time events: the first FDA approval of a PROTAC degrader, a $50 million Pfizer milestone tied to that approval, and the Rigel out-license of Vepinu. The third-quarter report, due before the open on November 3, will show the company without those items. The question is whether what remains, a narrower clinical pipeline funded by a shrinking cash pile, is worth more than the roughly $7 share price implies.
The Street is braced for a return to normal biotech economics. Consensus calls for a loss of $0.80 per share on revenue of $25.9 million. That revenue figure would be down about 38% from the $41.9 million reported a year ago. The expected loss is also about two-thirds wider than last year's $0.48 per share. That second point deserves attention. Management said its cost-reduction programs are complete, and R&D spending fell to $52.6 million last quarter from $68.6 million a year earlier. A deeper loss despite a leaner cost base would suggest revenue mix, not spending, is doing the damage. If expenses keep falling, the bottom line could come in better than feared. The company has not issued formal financial guidance, so the most concrete benchmark is cash. Arvinas ended June with $567.9 million and reaffirmed a runway into the second half of 2028. Cash has fallen every quarter from $787.6 million a year earlier. Another orderly step down, helped by Rigel payments, would support that runway. A steeper drop would test it.
The pipeline will carry more weight than the income statement. Last quarter brought two setbacks. ARV806, the KRAS G12D degrader that management had championed for three straight quarters as a lead priority with data expected by mid-2026, was demoted to proceeding only with a partner. ARV102, the LRRK2 program for Parkinson's, slipped by roughly a year because of an FDA clinical hold and information requests, pushing the next trials into 2027. This update is the first chance to learn whether a partner conversation for ARV806 is real or whether the asset is quietly shelved. It is also the first chance to hear whether the FDA issues on ARV102 are resolving. The additional ARV102 biomarker data slated for the October MDS meeting should give management fresh material for either argument.
There are also commitments to verify. ARV393, the BCL6 degrader, remains on track for initial Phase 1 data by year-end, and enrollment in the glofitamab combination was described as strong. Management has already warned that FDA-mandated low starting doses mean most 2026 patients will be dosed below the predicted effective range. Any hint that the readout is slipping, or that expectations for it are being lowered further, would land hard. On the constructive side, investors should look for confirmation that ARV027 is progressing through multiple-dose cohorts toward proof-of-mechanism data in the first half of 2027, and that enrollment in the HPK1 degrader ARV6723 actually began. Clarity on medical leadership after the chief medical officer dropped off the last call would also help.
Sentiment has soured noticeably. Readings have moved from nearly neutral before the last report to about 42% bearish now. The stock has fallen 12.2% since the last report while the S&P 500 edged up, leaving Arvinas about 13 points behind the market. At $7.31, it trades well below its 200-day average of $9.79 and sits in the lower part of its post-earnings range, not far above the $6.74 low. Expectations are low, which lowers the bar, but the stock has little technical support if the news disappoints.
The quarterly loss itself is unlikely to move the stock much. What matters is whether management can show that its focus on disciplined capital allocation reflects deliberate strategy rather than retreat. Firm timelines for ARV393 and ARV027, a credible path for ARV102 and ARV806, and a cash trajectory consistent with the 2028 runway would keep the post-approval narrative intact. Further slippage would reinforce the market's suspicion that the Vepinu approval was the peak rather than the platform's starting point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| Oct-15 |
Big Pharma Is Pouring Billions Into a New Class of 'Protein Degrader' Drugs
ARVN
The Wall Street Journal
|
| Oct-07 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-03 | |
| Sep-01 | |
| Aug-04 | |
| Aug-03 | |
| Jul-28 | |
| Jun-04 | |
| May-29 | |
| May-18 |
