Braves Holdings Must Show Braves Vision Timing Noise Can Become Real Profit Rebound
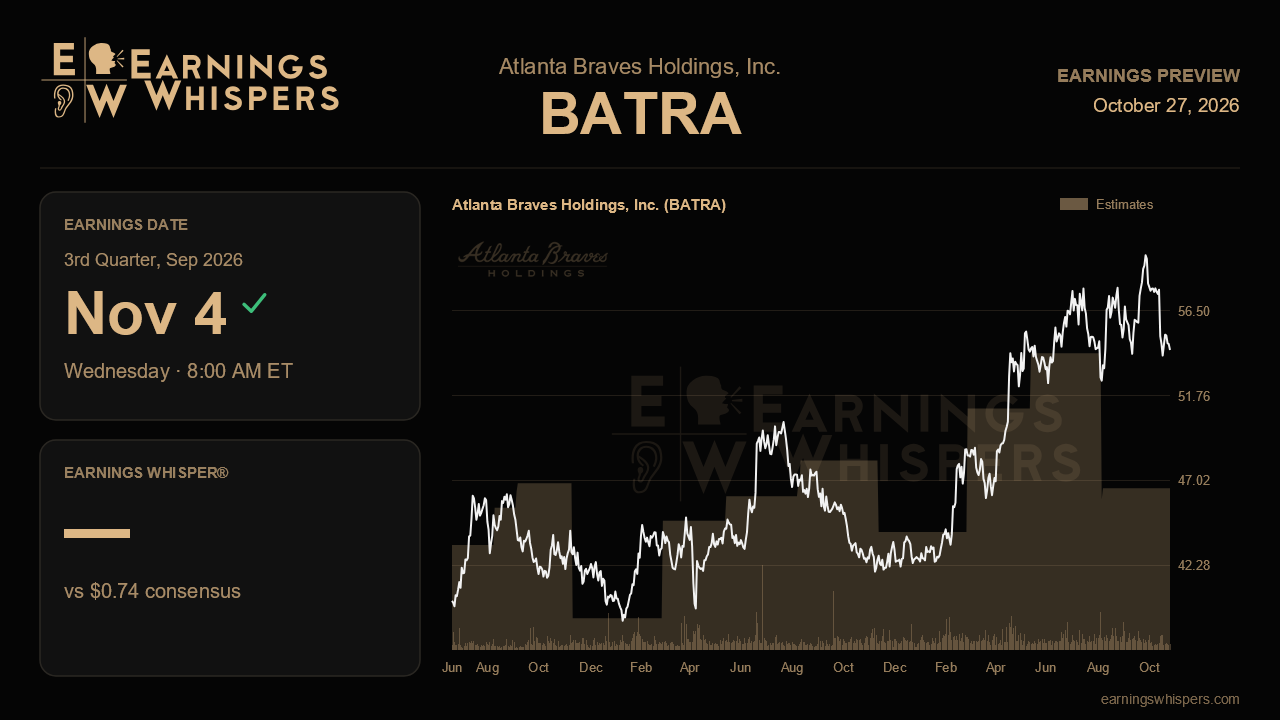
Last quarter, Atlanta Braves Holdings asked investors to look past an ugly income statement. Adjusted EBITDA fell to roughly $12 million from $66 million, and the company swung to an operating loss. Management's explanation was a calendar and accounting story rather than a demand problem: six fewer home games, plus revenue from Braves Vision's linear distribution being recognized on a slower schedule. The third-quarter report due before the open on November 4 is where that explanation either holds up or starts to look like an excuse.
The Street is leaning toward the benign interpretation. Consensus calls for earnings of $0.74 per share, up about 57.5% from $0.47 a year ago, a sharp turn from the $0.19 loss reported last quarter. There is no consensus revenue figure to anchor against, but the year-ago quarter brought in $311.5 million, and the second quarter produced $305.1 million despite the home-game shortfall. Management has not issued formal numeric guidance. Its standing commitment is that Braves Vision will match or beat the economics of the old regional sports network deal on an annualized basis. A profit jump of that size implies analysts expect at least some of the deferred media revenue and the scheduling headwind to swing back in the company's favor this quarter.
That makes media revenue the first line to check. It slipped to $73 million from $81 million last quarter on recognition timing. If the gap closes or reverses, the timing explanation holds. If media revenue stays soft, investors will have to weigh a new note of caution from the last call. Management said some cable distributors are losing subscribers faster than previously forecast, which points to a structural problem rather than a bookkeeping one. Upbeat language about the direct-to-consumer side, which management said is running ahead of early projections, will count for more if it comes with subscriber or revenue detail that offsets linear erosion. The cost side matters just as much. Production and administrative expenses for Braves Vision are now permanent, and player salaries are higher, so operating leverage depends on revenue growth outrunning a larger fixed base.
The ballpark and the real estate gave management its strongest evidence last time, and both should keep doing so. Per-game attendance rose in the first half, sellouts reached 17 through July, and special events such as the Savannah Bananas games and concerts lifted other baseball revenue by $13 million. The third quarter includes the first Braves Country Music Fest, which drew more than 100,000 visitors and should test whether event revenue is a repeatable growth engine. At The Battery, occupancy above 93%, record tenant sales and rising foot traffic set a high bar for continued gains in mixed-use revenue, which reached $29 million last quarter.
Liquidity deserves attention too. Cash fell to $116 million and revolver capacity shrank to about $205 million as the company borrowed to bridge slower Braves Vision collections. Rebuilding those balances would be the clearest proof that the cash-timing gap is temporary. Looking further out, the December 1 expiration of the collective bargaining agreement and the unresolved 162(m) salary-deduction issue remain overhangs that the quarter's results cannot settle.
Market positioning is cautious but improving. Sentiment remains bearish but less so, at 23.0% bearish versus 28.4% before the last report. The stock has gained 2.2% since then while the S&P 500 slipped 1.4%. At $54.31, shares sit above their 200-day average of $52.35 but well below the post-earnings high of $60.48, so the market has not fully priced in a clean recovery. The central question is whether the profit rebound comes from durable media and event revenue rather than one-time catch-up items. If it does, last quarter's slump will look like what management said it was.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-16 | |
| Sep-22 | |
| Sep-17 | |
| Sep-14 | |
| Sep-01 | |
| Aug-18 | |
| Aug-05 | |
| May-18 | |
| May-15 | |
| May-12 | |
| May-11 | |
| May-06 | |
| Apr-23 | |
| Apr-15 |
