Camtek's Raised Outlook Meets A Battered Stock As Q3 Tests The Advanced Packaging Surge
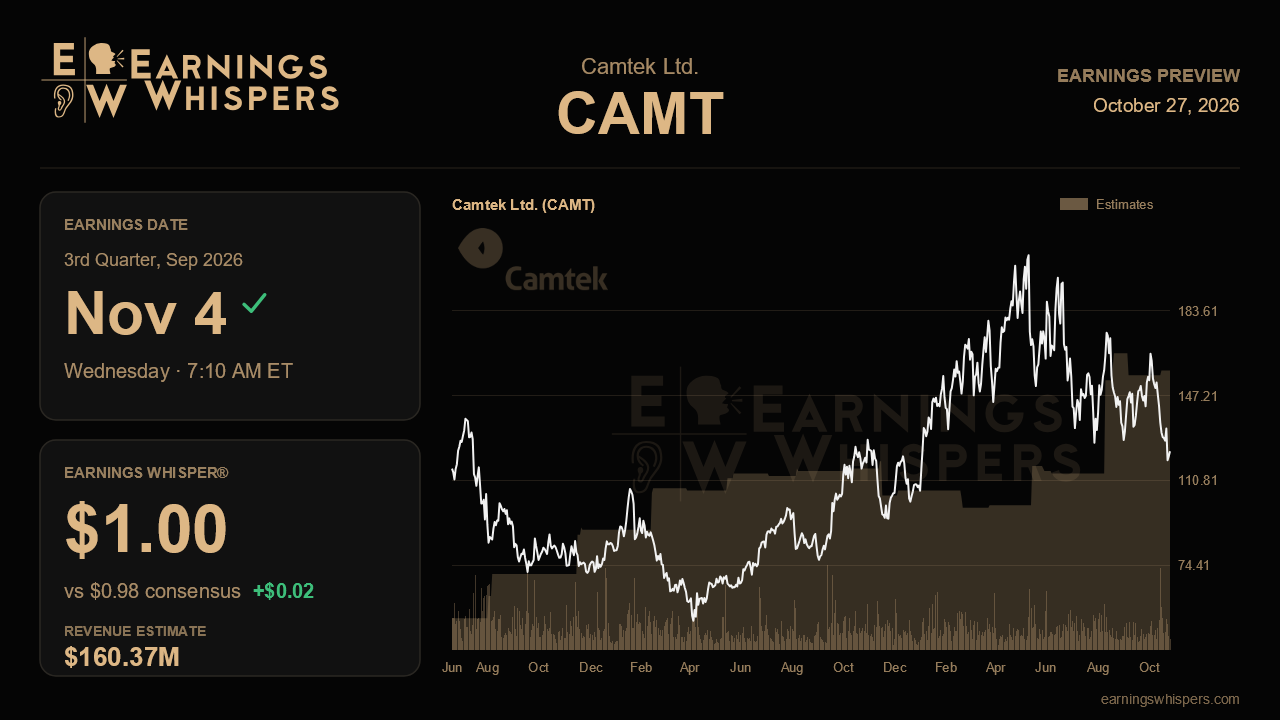
Camtek heads into its third-quarter report with an unusual disconnect. Management has spent four straight calls raising its sights, recently lifting its third-quarter revenue range again and putting a number above $800 million on 2027. Yet the stock has dropped more than 27% since the last report while the broader market was roughly flat. The business story has grown stronger and the share price has moved the other way, so this report has to show that the promised second-half acceleration is real, profitable and turning into cash.
The Street expects non-GAAP earnings of $0.98 a share on revenue of about $160.4 million, a gain of roughly 27% from the year-ago quarter's $126.0 million. Management's updated range of $160 million to $161 million is a step up from the earlier $158 million to $160 million, and consensus sits near its midpoint. That means a modest revenue beat is close to the base case rather than a stretch. The earnings whisper of $1.00 is only slightly above consensus, which points to a bar that is a bit higher than the published estimate but not dramatically so. The bigger signal is in the outer years. Management's roughly $595 million for 2026 is close to the Street's $593.4 million, but its 2027 call for more than $800 million is well above the $765.3 million consensus. That gap shows analysts have not fully accepted the company's view.
The operating case comes from last quarter's call, when management described record order intake above $600 million year to date. About 80% of those orders were tied to advanced packaging, more than half came from OSATs, over 20% came from HBM customers moving to HBM4, and roughly 5% came from photonics. Management projected advanced packaging revenue up about 45% in the second half versus the first, with the fourth quarter about 70% above the first. A clean third quarter near $160 million would be the first hard proof that this order book is shipping on schedule. Commentary on the size of the 2027 backlog, and on whether photonics and the new NanoProf metrology platform are drawing multi-system orders, would show whether the newer growth drivers are more than talking points.
Margins are the second test. Consensus implies earnings jumping about 40% from last quarter's $0.69 on revenue growth near 20%, so the estimate already assumes real operating leverage. Management has targeted a gross margin exit of 52% to 53% and an operating margin of 30% to 32% by year end, up from 27% in the second quarter. To hit those targets, the third quarter should show visible progress, helped by the new Eagle G5 and Hawk systems, which already made up about half of system revenue. Rising operating expenses from the Visual Layer acquisition, component costs and a strong shekel could slow that progress. A competitor push in the OSAT market would also become a concern if pricing commentary softens.
Cash conversion may be the quiet swing factor. Days sales outstanding jumped to 105 from 65 at the end of 2025, receivables climbed to $158 million, and operating cash flow was only $12.2 million as inventory was set to build. Another quarter of swelling receivables would invite questions about collection terms with large customers, even if revenue lands on target.
Sentiment has edged to modestly bullish from slightly bearish heading into the last report, but the chart tells a more cautious story. At about $123, the stock sits well below its 200-day moving average near $158 and just above its post-report low of $116.32, far from the $178 high of the range. The low price gives Camtek room to be rewarded if results confirm the story. It also suggests the market is skeptical about how long the advanced packaging cycle will last. The report will be judged less on whether Camtek meets its revenue guide and more on whether margins, cash flow and backlog commentary support the case that 2027 can clear $800 million.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-07 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-20 | |
| Jun-02 | |
| May-19 | |
| May-12 | |
| May-12 | |
| May-12 | |
| Apr-23 |
