Brookfield Renewable's FFO Streak Faces A Quality Test As Shares Slide Toward Range Lows
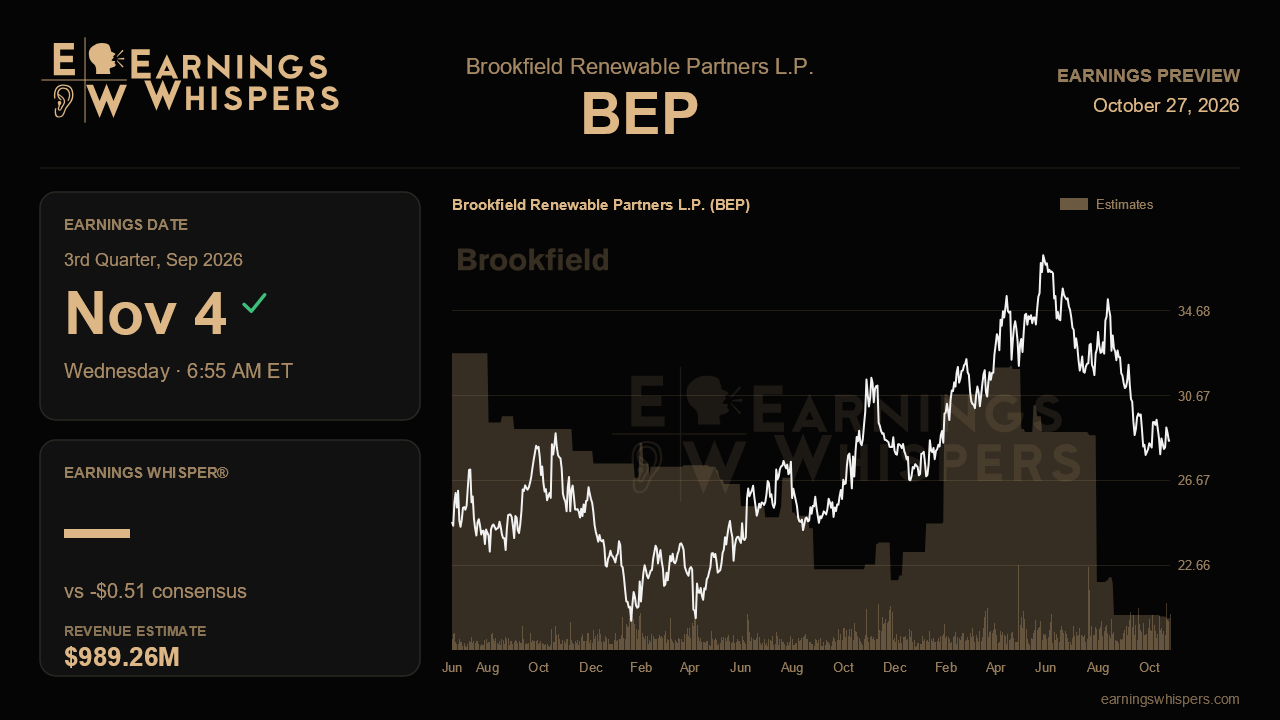
Brookfield Renewable heads into its third-quarter report with an awkward split between its business and its stock. Management has delivered four straight quarters of rising funds from operations per unit, raised its growth outlook, and added two significant new catalysts in nuclear and batteries. Yet the units have fallen 14.6% since the last report while the S&P 500 gained 2.8%. When results come out before the open on November 4, the key question is whether the operating story is as durable as management says, or whether the market is right to question how much of it rests on one-time gains.
The headline consensus numbers look harsh but say little about the partnership's economics. Analysts expect a GAAP loss of $0.51 per unit, compared with a $0.23 loss a year ago, and revenue of about $989 million. That would be a 38% drop from the year-ago $1.60 billion and well below last quarter's $1.71 billion. A revenue decline that steep deserves an explanation in the release. The cleaner measure remains FFO per unit, which climbed from $0.46 in the year-ago quarter to $0.62 last quarter. Management said near-term FFO per unit growth should exceed 10%. Measured against the year-ago figure, that implies something in the low $0.50s at minimum. Because last quarter's run rate sits well above that, anything that slips meaningfully back toward the year-ago level would undercut the sense of momentum.
The composition of FFO matters as much as the total. On the last call, an analyst noted that asset-sale gains, including $175 million in hydro last quarter, are becoming a larger and more regular part of earnings. Management treats capital recycling as a core, repeatable activity, and it brought in record proceeds in the first half. Skeptics see a recurring dependence on transactions. A strong quarter driven mainly by the underlying generation business would answer that concern directly. A quarter that relies again on large disposal gains, particularly if US hydrology stays as weak as it was in the first and second quarters, would likely sharpen the debate.
The new growth drivers also need to show progress. The Department of Energy's commitment of up to $17.5 billion in loan facilities moved the Westinghouse partnership from a financing framework toward individual projects, and management said it is working with seven utility partners that have identified sites. Firm long-lead equipment orders, or concrete progress toward them, would show that the nuclear opportunity is turning into real work. Westinghouse FFO grew more than 60% last quarter, excluding a prior-year licensing fee, so continued strength there is important. On batteries, the IPA acquisition roughly doubled operating and under-construction capacity to about 6 gigawatts and was described as immediately accretive. Investors should look for early evidence of that accretion. The release should also address the outcome of the October unitholder vote on combining BEP and BEPC into a single listed corporation, along with any remaining unresolved US tax-credit questions.
Sentiment has improved modestly, rising to 14.7% bullish from 8.5% before the prior report. That suggests some investors see value after the selloff. The chart is less encouraging. At $28.56, the units sit about 11% below their 200-day moving average of $32.02 and only about 4% above the post-earnings low of $27.45. The entire range since the last report has been below the previous quarter's $31.33 floor. A solid report could give the stock a reason to stabilize. Another disappointment could push it toward a test of that low.
In the end, this report comes down to earnings quality. If Brookfield can keep FFO per unit on its double-digit growth path with less help from asset sales, while showing tangible progress in nuclear and batteries, the gap between the business and the share price will be hard to justify. If the growth again depends mainly on transaction gains, the market's recent skepticism will look better founded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Sep-18 | |
| Sep-18 | |
| Aug-31 | |
| Aug-31 | |
| Aug-20 | |
| Aug-17 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-21 | |
| Jul-02 |
