Charles River's 34% Rally Puts Its DSA Bookings Recovery Under A Brighter Spotlight
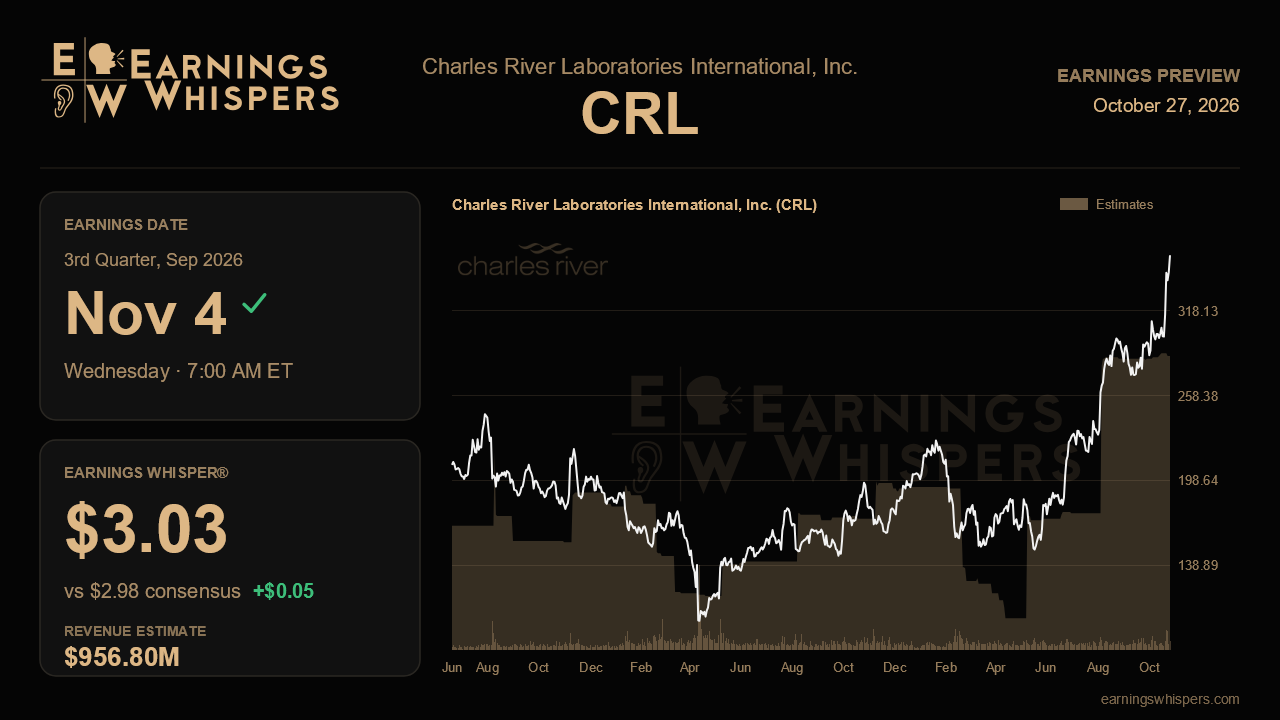
Charles River Laboratories heads into its third-quarter report with something it has not had in a long time: momentum, and a stock price that fully reflects it. Shares have climbed about 33% since the last report while the S&P 500 slipped, and they now sit right at their post-earnings high, roughly 63% above the 200-day moving average. Last quarter management argued that the long downturn in early-stage drug development spending had finally turned. The November 4 report, due before the open, is the first real test of whether that turn is durable or merely a good quarter.
Wall Street expects earnings of $2.98 per share on revenue of about $956.8 million. That implies EPS growth of nearly 23% from $2.43 a year ago, even as reported revenue is projected to fall almost 5%. The gap matters. Management now guides full-year organic revenue to flat to up 1%, so a headline revenue decline points more toward portfolio changes than toward weakening demand, and the earnings gain reflects margin work rather than volume. The earnings whisper of $3.03 sits modestly above consensus, a sign that some traders expect a small beat. Notably, full-year consensus of $11.05 per share and $3.85 billion in revenue both sit below management's raised ranges of $11.15 to $11.45 and $3.875 billion to $3.915 billion. If the company simply delivers on its own outlook, estimates have room to move higher.
The heart of the story is the Discovery and Safety Assessment segment. Net book-to-bill rose from 0.82 in the third quarter of 2025 to 1.19 last quarter, the third straight reading above 1.0 and the best in nearly four years, pushing backlog to $1.97 billion. Another reading above 1.0 would confirm that bookings are converting into a growing revenue base and support the upgraded call for low-single-digit DSA growth. A slip back toward or below 1.0 would revive the worry that the recovery is lumpy, something management itself cautioned when it described the rebound as gradual and uneven. Commentary on biotech funding, which management said was running near pandemic-era levels, and on whether pricing is moving beyond merely stable will help investors judge how much runway remains.
Margins are the second pillar. Operating margin jumped 420 basis points sequentially to 20.5% last quarter, and management said it could see at least 500 basis points of second-half improvement, driven by cheaper nonhuman primate sourcing from its Cambodia operation, divestiture benefits and lower corporate costs. The biggest sourcing benefit is slated for the fourth quarter, so the third quarter should show progress rather than the full payoff. Manufacturing margin, at 37.8%, was expected to approach 40%. Offsetting forces include a higher tax rate tied to proposed foreign legislation, worth about 20 cents a year, and corporate costs running closer to 6% of revenue.
Research Models and Services remains the soft spot, guided to a low-to-mid-single-digit decline as flat NIH budgets and slow grant processing weigh on North American academic demand. Stabilization there would be a bonus; further deterioration would test whether DSA strength can carry the whole company.
Sentiment has swung from slightly bearish before last quarter to clearly bullish now, and the stock's run means the market has already rewarded the recovery narrative. That raises the bar. Matching consensus may not be enough; investors will likely want another healthy book-to-bill, visible margin expansion toward the promised second-half step-up, and at least reaffirmed, if not raised, full-year guidance. The central question is simple: is DSA demand still compounding? If bookings hold above replacement levels while margins climb, the inflection story stays intact. If they fade, a stock priced for recovery has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Sep-24 | |
| Sep-24 | |
| Sep-17 | |
| Sep-11 | |
| Sep-08 |
