Lincoln Electric Beats As Volume Finally Leads Growth And Guidance Rises Again, But Price-Cost Squeeze Deepens
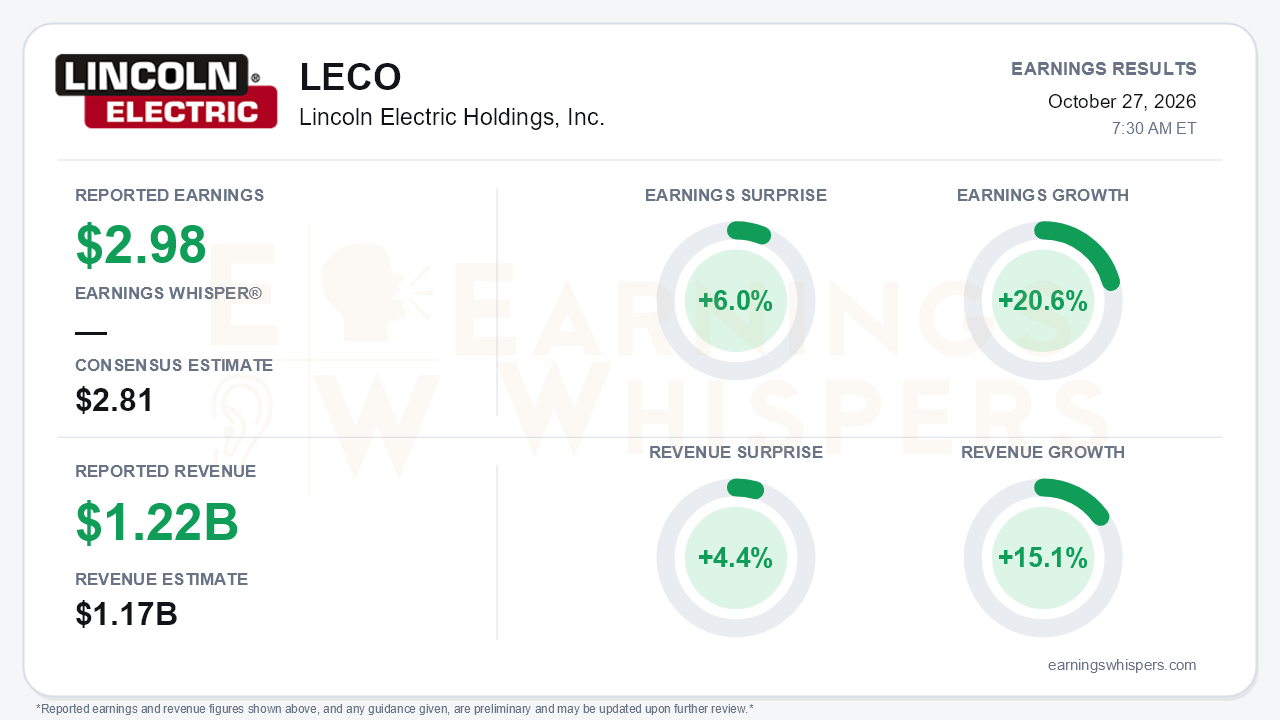
Lincoln Electric delivered the kind of quarter it had been promising: volume drove the growth. Adjusted EPS of $2.98 beat the $2.81 consensus by 6.0% and rose 20.6% year over year. That was a record, and it edged past Q2's $2.93 after Q1's $2.50. Revenue of $1.221 billion topped the $1.17 billion consensus by 4.4% and grew 15.1%, up from roughly 12% growth in Q2. The composition matters more than the beat. Volume contributed 8.8% and price 5.7%. Management said it was the first quarter in more than two and a half years in which volume outpaced price, a sharp turn from Q1's 2.6% volume decline and Q2's roughly 2% gain. The central tension is that the demand story improved decisively while the cost story got worse.
The quality of the beat deserves scrutiny. Gross margin fell 190 basis points to 34.8%, a much steeper decline than Q2's 50-basis-point slip, as input costs again outran pricing. Operating margin still expanded, rising to 17.3% on a GAAP basis and 18.0% adjusted. The reason was that SG&A was essentially flat in dollars while sales jumped $160 million, which cut SG&A to 16.9% of sales from 19.5%. That is real operating leverage, but it is not the same as pricing power. GAAP EPS of $2.63 rose 19%. The $0.35 gap to adjusted EPS mostly reflects roughly $13 million of tax expense tied to repatriating foreign earnings, plus restructuring charges. Cash generation softened:
- Free cash flow fell to $174.5 million from $205.1 million.
- Cash conversion dropped to 107% from 149%, as receivables and capex both rose.
The segments tell a divided story:
- **Americas Welding** was the engine. Volume rose 13.2%, U.S. sales grew more than 20%, and adjusted EBIT margin climbed 190 basis points to 20.1%.
- **International Welding** remains a drag. Volume fell 1.4% on weak European capital spending and Middle East disruption, and adjusted EBIT margin slid to 10.3% from 11.3%.
- **Harris Products** grew sales 28.9%, but almost all of that came from a 25.7% price contribution, with volume up just 3%. Its margin slipped to 17.3%, below management's range, on mix and operational inefficiencies.
On the call, management also flagged that silver deflation will pressure Harris pricing comparisons in 2027.
The call preserved a credible growth story and then some:
- **Sales guidance** for full-year 2026 moved up to low-teens growth. That is the fourth consecutive raise, from mid-single digits as of Q4 FY25, then high single digits, then low double digits.
- **Automation** sales reached $232 million with high-teens organic growth. Equipment organic growth accelerated to the low teens, and both automation and equipment backlogs hit records.
- **End markets**: all five grew, compared with four in Q2 and three in Q1.
- **Margin guidance**: the Q4 Americas margin guide rose to 20-21%, and the International guide to 12-13%.
- **Capex** was lifted to $140-150 million from $110-130 million.
Forward catalysts include the ExpertLink physical-AI welding automation platform, priced on a recurring subscription of roughly $3,000 per arm per year. Management also cited rising auto quoting tied to 2029-2030 model launches and early help from European defense spending. The dividend was raised 10.1% to $3.48 annualized.
Bears still have legitimate ammunition, and it centers on costs. Price-cost neutrality has now slipped three times: from full-year 2026, to the second half, to Q4 only. Year to date, the company is 100 basis points behind neutral. Management attributed the inflation to AI data-center demand straining energy, logistics and electronic components. It acknowledged being "one step behind" on costs and described the effort as a "game of whack-a-mole." Incremental margins of 22% remain short of the high-20s target set under the company's RISE strategy. The Harris margin guide was trimmed to about 18%, and Q4 corporate expense is now guided to $4-5 million versus $1-2 million previously. The same AI buildout feeding Harris's data center and HVAC demand is also inflating Lincoln's input costs.
Investors entered the report cautious. Earnings Whispers sentiment remained positive but eased modestly, from 0.20 to 0.16. Shares closed at $258.65 the day before the release, 2.9% below the $266.37 open following the July report and about 2.5% under the 200-day moving average. The stock rallied to $292.63 in late August and then gave back most of that move. It now sits 11.6% below that high and 6.4% above the inter-earnings low set the day of the prior report. Trend readings are mixed, with momentum positive while AVWAP remains negative. That fits a market that has rewarded the demand recovery inconsistently.
The bottom line is that Lincoln Electric answered the volume question emphatically, and the rising guidance and record backlogs suggest the cycle is turning in its favor. What it has not answered is when pricing will catch up to costs, a target management has now pushed out three times. Until gross margin stabilizes and incremental margins move toward the high-20s target, the quarter's top-line strength will carry an asterisk. For investors, the setup has shifted from waiting on demand to waiting on margin execution.
Read our earnings preview for Lincoln Electric Holdings, Inc.: https://www.earningswhispers.com/article/LECO/20713
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 9 hours | |
| 9 hours | |
| Oct-20 | |
| Oct-14 | |
| Sep-30 | |
| Sep-16 | |
| Sep-01 | |
| Aug-11 | |
| Aug-11 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-22 | |
| Jul-07 |
