Kennametal's Tungsten Windfall Peaks As Wall Street Weighs What Comes After
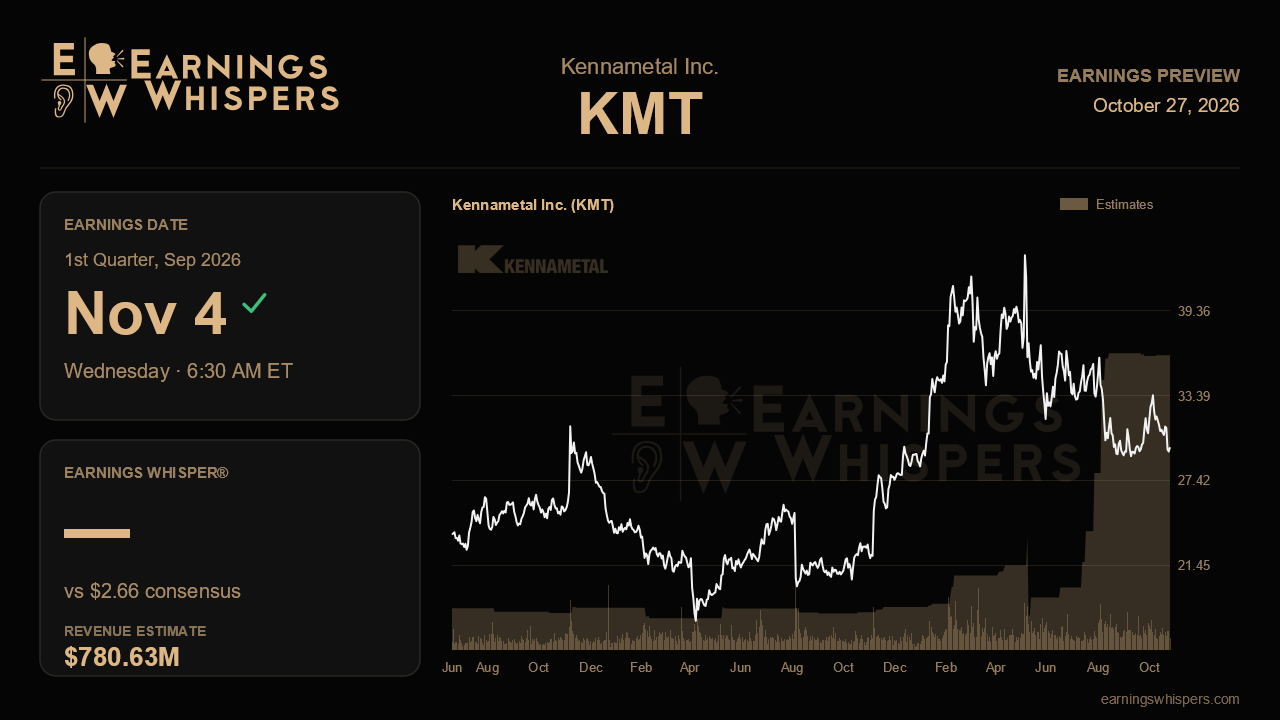
Kennametal heads into its fiscal first-quarter report with an odd setup: the company is expected to post one of the strongest quarters in its recent history, yet its stock has been treated as if the party is already over. That tension makes the November 4 release less about the headline beat and more about whether the underlying business can carry the load once the tungsten pricing windfall fades.
The Street is looking for earnings of $2.66 per share on revenue of $780.6 million, which would represent growth of roughly 682% in profit and about 57% in sales from a year ago, when Kennametal earned $0.34 on $498.0 million. Those are extraordinary comparisons, but they mostly reflect how much tungsten-driven pricing has reshaped the income statement. Management guided to earnings of $2.50 to $2.80 on revenue of $745 million to $775 million, so the EPS consensus sits right at the midpoint while the revenue estimate is slightly above the top of the company's range. That tells you analysts expect pricing and volume to come in firm but are not banking on outsized margin upside. A revenue figure that clears the guided range without a matching EPS beat would hint that costs, interest or currency are absorbing more than expected.
The broader fiscal 2027 outlook explains why this quarter matters so much. Management guided full-year earnings of $4.15 to $5.15, meaning the first quarter alone is expected to deliver more than half the year's profit. The price-versus-raw-material timing benefit, worth $3.11 per share in fiscal 2026, shrinks to just $0.39 this year and should be largely gone by the start of the fiscal third quarter, after which it turns into a headwind. Management framed a clean fourth-quarter EBITDA margin in the mid-teens, far below last year's 26.9%. In other words, this report is the peak, and investors will care more about the trajectory than the number itself.
That puts the spotlight on the operational story management told last quarter. Organic sales rose 42% in the June quarter, with infrastructure up 74% and metal cutting up 22%, and the company expected about 2.5% volume growth this year including one to two points of share gain after roughly three years of stagnant industrial production. Validation would look like evidence that volumes, not just price, are rising, particularly in energy, where management flipped its rig count assumption from a mid-single-digit decline to a high-single-digit increase, and in aerospace and defense, now expected to become the third-largest end market. Any color on carbon fiber composite cutting tools or AI data center power generation wins would help show the post-tungsten growth engine is real. Conversely, further softness in transportation or earthworks, or progress short of the $110 million restructuring savings target, would weaken the case.
Cash is the other pressure point. Free cash flow was negative $79 million last year, management flagged a roughly $200 million cash draw this quarter, and a new $500 million term loan was set to be fully drawn in the September period, lifting interest expense to about $50 million annually with buybacks on hold. A Bolivia currency hit adds another $0.23 drag. Signs that working capital is peaking would ease balance-sheet worries.
The market has been unforgiving. Shares have dropped 26.5% since the last report against a 1.4% slip for the S&P 500, and at $29.76 the stock trades well below its 200-day average of $34.66 and only a few percent above its post-earnings low of $28.74. Sentiment has improved from clearly bearish to nearly neutral, suggesting some of the pessimism may already be priced in. Ultimately, Kennametal needs to show that volume growth, share gains and cost savings can credibly replace the fading tungsten tailwind; if that bridge looks solid, the stock's slide may prove overdone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Oct-09 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 | |
| Sep-15 | |
| Sep-14 | |
| Aug-18 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-20 |
