Kraft Heinz Must Prove Its Heavy Brand Spending Is Buying A Real Consumption Recovery
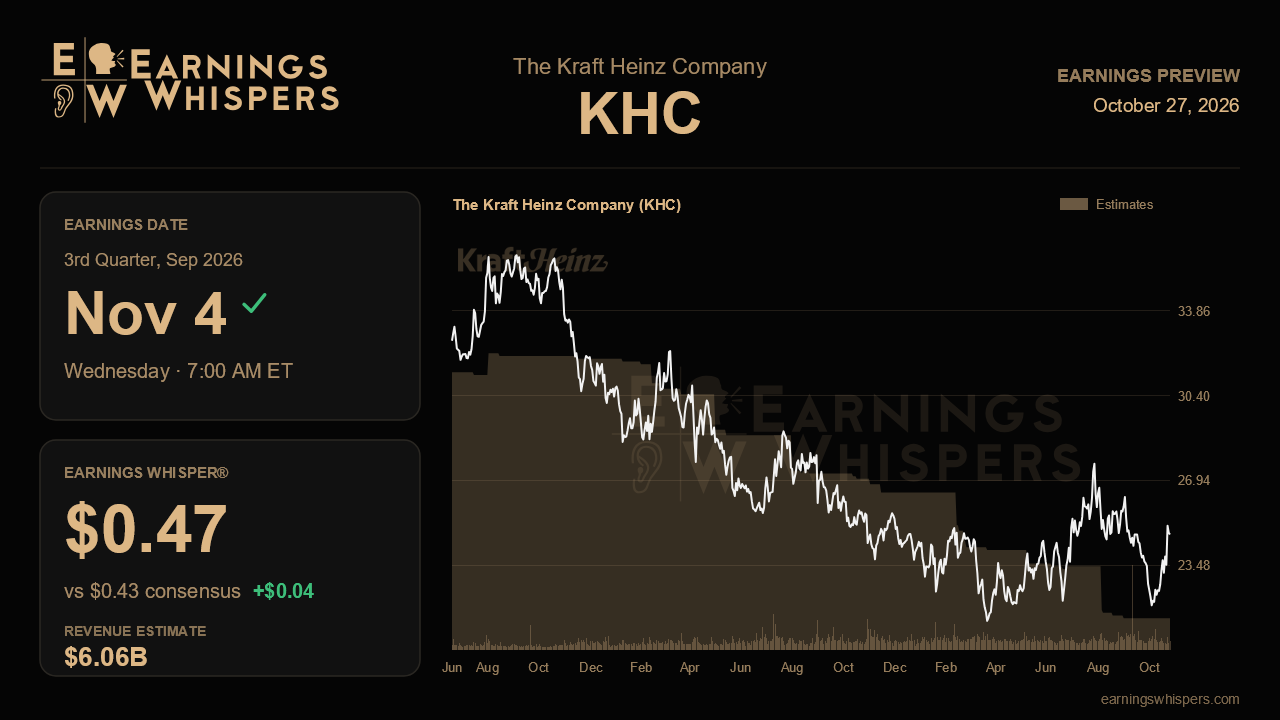
Kraft Heinz heads into its third-quarter report with an unusual setup: Wall Street expects earnings to fall sharply, and management has largely told it to. The company is spending heavily to revive its brands, with roughly $500 million of its enlarged $700 million investment budget still to be deployed across the back half of the year. This quarter should show whether that money is buying the consumption turnaround management described last time, or simply funding a costlier version of the same decline.
The Street is looking for earnings of $0.43 a share on revenue of about $6.06 billion, which would be a drop of nearly 30% in profit and a 2.8% slide in sales from a year ago. It also marks a steep step down from the $0.56 earned last quarter. That is a contraction story on paper, but much of it reflects deliberate spending rather than collapsing demand. The whisper number of $0.47 sits meaningfully above consensus, suggesting the more informed bar is higher than the published one. Full-year guidance of $2.03 to $2.09 a share brackets the $2.07 consensus near the upper half of the range, while the revenue consensus of $24.45 billion sits right at the bottom of management's freshly raised $24.44 billion to $24.82 billion outlook. In other words, analysts trust the earnings plan but remain skeptical about the top line.
That top line is where the prior call's narrative gets its real test. Management said U.S. consumption improved from about a 2.5% decline in the second quarter to roughly 1% in July, and it promised sequential improvement through the third and fourth quarters, with the best exit rate coming at year end. Some second-quarter shipments were also pushed into the third quarter, which should flatter reported sales. Confirmation would look like consumption holding near flat, market-share losses narrowing beyond the recent 20 basis point pace, and continued strength in Heinz condiments, emerging markets and away-from-home. A challenge would come if consumption slipped back toward the second-quarter pace despite heavier spending, or if the shipment benefit is the only thing propping up revenue.
The new catalysts deserve scrutiny too. The Disney and NFL partnerships were introduced only last quarter, so early evidence of activation matters, as does whether Power Mac and Cheese is sustaining its strong velocity now that it sits in 35,000 stores. On the risk side, retailers were expected to step up private-label price investment in the second half, which could widen price gaps just as Kraft Heinz is trying to win shoppers back. The roughly 100 basis point SNAP headwind persists, Oscar Mayer Deli Fresh remains a drag, and any update on 2027 inflation, already nudged up to a 4% to 5% range, will shape how much margin room the company has once this investment cycle matures.
The market has not given management much credit. Shares have fallen 8.3% since the last report, trailing the S&P 500 by seven percentage points, even as the operating tone improved. Sentiment has warmed considerably, though, moving from deeply bearish last quarter to only slightly negative now. At $24.73, the stock sits above its 200-day moving average and in the upper half of its post-earnings range of $21.76 to $27.05, not yet pressing on a breakout.
Ultimately, the quarter hinges on a simple trade. Investors have accepted lower near-term earnings in exchange for a credible path back to growth. If consumption and share keep bending upward while cash generation stays on track, the spending looks like an investment. If the trend stalls, it starts looking like a subsidy.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-22 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Sep-29 | |
| Sep-25 | |
| Sep-23 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 |
