CTS Beats And Raises Again As Record Margins Mask Slowing Organic Growth
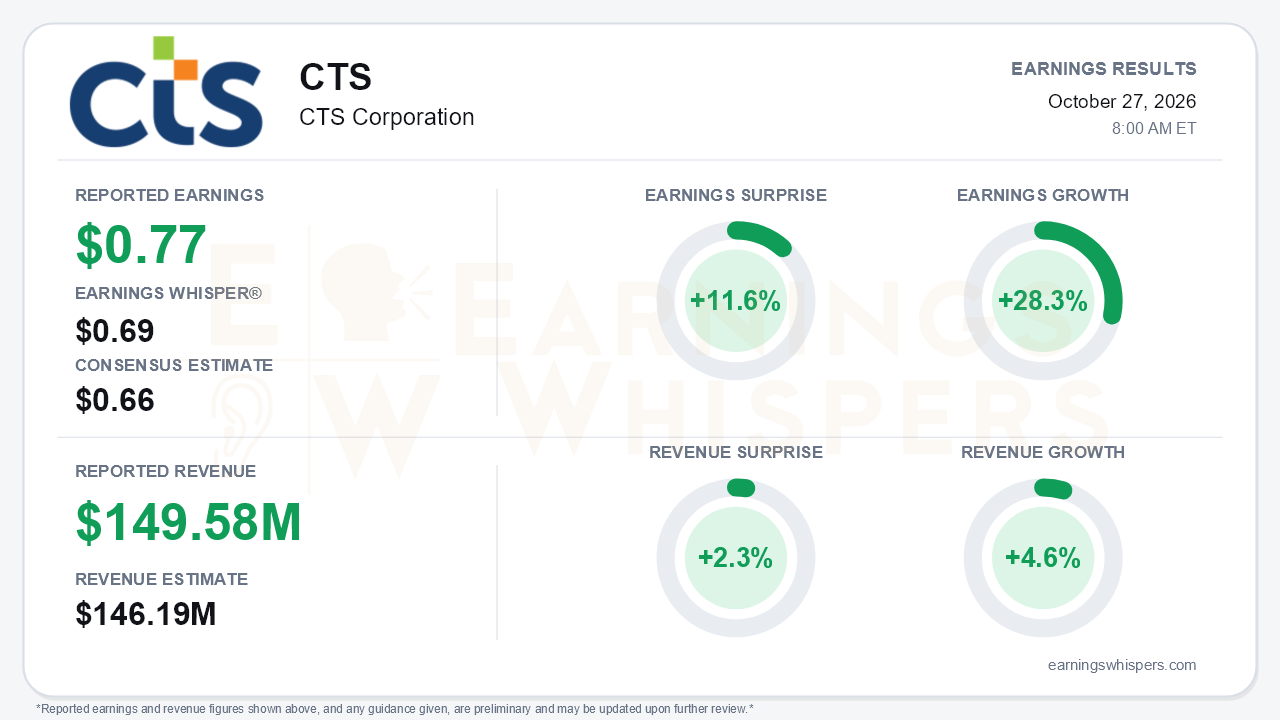
CTS Corporation delivered a clean beat on the numbers that matter most to the Street. Adjusted earnings of $0.77 per share topped the $0.66 consensus by 11.6% and cleared the $0.69 Earnings Whisper number. Earnings grew 28.3% year over year, and revenue of $149.58 million rose 4.6%, edging past the $146.19 million estimate by 2.3%. Management also raised full-year guidance for the third consecutive call. The central tension is that earnings are compounding much faster than sales. Organic top-line momentum has cooled each quarter this year, so the earnings story increasingly rests on margins that management itself says will not hold at Q3 levels.
The quality of the beat deserves some scrutiny, though not dismissal. GAAP diluted EPS was $0.61, up from $0.46. Two large, offsetting items sat inside that figure: a $12.5 million insurance recovery booked in other income, and roughly $12.7 million of discrete tax charges tied to a valuation allowance on foreign tax credits and uncertain tax positions. Those charges pushed reported tax expense to $20.5 million on $38.2 million of pretax income. The adjusted figure strips out both, which is reasonable. Investors should still note that roughly $0.04 of Q3 EPS came from foreign exchange. Operationally, the improvement is real. Adjusted gross margin hit a record 42.2%, up from 38.9% a year ago and 41.5% in Q2, while GAAP operating margin expanded to 17.1% from 14.6%. Free cash flow of $41.1 million was the standout, up from $24.2 million, lifting cash to $144 million from $82 million at year-end.
Beneath the headline, growth is decelerating. Total sales growth slowed to 5% from 7% in Q2 and 11% in Q1. Diversified end-market growth, the core of the portfolio-shift thesis, slowed to 7% from 15% and 18%. Medical cooled to 21% growth from 45%, fell 4% sequentially, and its book-to-bill dropped to 0.66 from 1.21; management attributed the drop to order timing. Industrial growth halved to 7% from 16%. Adjusted EBITDA margin slipped to 24.7% from 25.4% in Q2 even as gross margin set a record, reflecting higher SG&A, including stock-based compensation that nearly tripled year over year. Transportation turned positive at +2% after -2% in Q2, but that came from commercial vehicles. Light-vehicle production remains flat to modestly down.
The forward indicators are more encouraging than the trailing growth rates. Total book-to-bill improved to 1.18 from 1.10, with diversified at 1.3 and industrial at 1.36. Aerospace and defense was the clear bright spot: sales rose 30% sequentially to $24 million as government funding flowed, and book-to-bill reached 1.91, delivering the second-half pickup management flagged last quarter. Scaled production of a sensing solution for U.S. Navy undersea warfare, data-center demand in industrial, and transportation wins in seat tracks with Japanese OEMs add further optionality. The Millar acquisition, at roughly $50 million in cash for about $30 million in annual revenue, deepens the medical sensing push and is gross-margin accretive. However, it is not expected to add to EBITDA initially or to EPS until the second half of 2027, and it carries customer concentration.
Guidance is where the margin caveat matters. Full-year sales guidance rose to $580-$590 million from $565-$585 million, and adjusted EPS guidance rose to $2.78-$2.88 from $2.55-$2.70. With $2.13 already earned through nine months, the new range implies Q4 adjusted EPS of roughly $0.65-$0.75, a sequential step down from $0.77. That is consistent with the CFO's warning that gross margin should normalize below 42% as Q3's above-normal mix and roughly $1.4 million FX benefit fade.
The market had been treating CTS skeptically heading into the report. Shares opened at $62.67 after the July release and peaked at $67.99 in early August. They then slid to $53.92, a 14.0% decline, leaving the stock 5.4% below its 200-day moving average and just 2.4% above the inter-earnings low set days before the report. Investor sentiment nonetheless improved meaningfully, rising from essentially neutral (0.0036) to a modestly positive 0.2519. The internal trend readings are mixed, with momentum positive while AVWAP remains negative, which fits a stock whose fundamentals have outpaced its price action.
The bottom line is that CTS produced a high-quality beat-and-raise backed by record margins, strong cash generation, and firming orders in A&D and industrial. Still, bears have legitimate ammunition in decelerating organic growth, a soft medical order book, and a management-flagged margin pullback. With the stock pressed near its quarterly low, the report gives bulls a credible rebuttal. The next test is whether bookings convert into reaccelerating sales before margins normalize.
Read our earnings preview for CTS Corporation: https://www.earningswhispers.com/article/CTS/20689
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 9 hours | |
| 9 hours | |
| Oct-23 | |
| Oct-12 | |
| Sep-30 | |
| Aug-26 | |
| Aug-14 | |
| Aug-14 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jun-25 | |
| Jun-16 |
