Hut 8 Heads Into Q3 With A $26.6 Billion Backlog And A Stock That Has Lost 39%
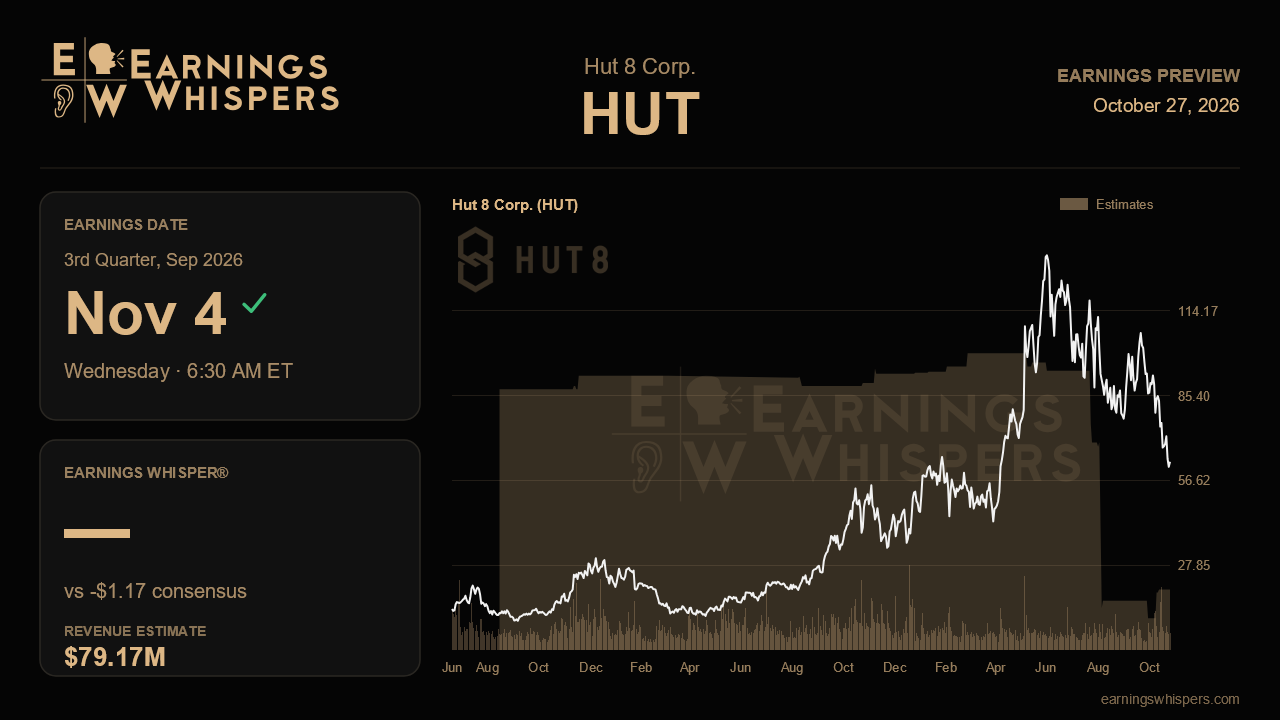
Hut 8 has spent the past several quarters convincing institutional lenders that it is building a power-first AI infrastructure platform, and the bond market has largely bought the pitch. The stock market, at least lately, has not. Shares have fallen about 39% since the company last reported, while the S&P 500 was roughly flat. That gap is the central tension heading into the third-quarter report on November 4: management's contracted story keeps compounding, but the income statement it reports today still reflects a Bitcoin business with mark-to-market swings and a growing pile of pre-revenue costs.
Wall Street expects a loss of $1.17 per share, far deeper than the $0.07 loss a year ago and the $0.26 loss last quarter. Revenue is forecast at $79.2 million, a modest sequential gain from $74.9 million but about 5% below the year-ago figure. That is a contraction quarter on the top line, which matters less than it sounds. Nearly all current revenue comes from compute and mining, while digital infrastructure brought in just $1.3 million last quarter, because the lease cash flows from Riverbend and Beacon Point do not start until data halls energize around the second quarter of 2027. With no formal guidance to anchor against, the steep loss estimate likely reflects analysts' assumptions about digital-asset marks, interest expense on two fully funded campuses, and elevated overhead rather than a judgment on the AI build-out itself.
That makes the operating detail more important than the headline numbers. Last quarter, contracted AI capacity jumped to 949 megawatts across Riverbend and Beacon Point Buildings 1 and 2, with aggregate base-term contract value near $26.6 billion. The company also priced a $4.25 billion investment-grade Beacon Point bond one notch above the earlier Riverbend deal, 20 basis points tighter, with a longer amortization schedule. Validation this quarter would look like confirmation that Riverbend construction remains on schedule for 2027 delivery, progress on the roughly 200 megawatts that moved into exclusivity, and ideally a new lease or financing drawn from a development pipeline of about 8.7 gigawatts. Management also highlighted rising inbound acquisition and behind-the-meter interest, so any concrete transaction would show that pipeline is converting rather than merely growing.
The risks flagged last time are the ones that could challenge the narrative. Texas regulatory scrutiny, prompted by Governor Abbott's letter and evolving ERCOT rules, was new last quarter, and any sign that permitting or community-protection requirements are slowing timelines would hit at the core of the story. General and administrative expense reached $76.1 million, with $43.6 million in stock-based compensation; investors will want evidence that the cash portion is building capability rather than becoming a fixed burden. Construction-period interest also deserves attention, since interest income on raised capital and capitalized interest only partly offset it. On the mining side, adjusted EBITDA excluding marks rose to $10.4 million last quarter, and holding gross margin near the mid-60s would show the legacy business can keep funding the parent while the campuses rise.
Sentiment has edged up to about 19% bullish from roughly 14% before the prior report, a mild improvement that sits awkwardly beside the share price. At $62.97, the stock trades well below its 200-day moving average of $82.28 and only about 7% above its post-earnings low of $58.75, a far cry from the prior quarter's range topping out above $140. Expectations embedded in the price appear to have reset sharply lower.
The question this report must answer is whether execution is keeping pace with the contracts. A deep GAAP loss is largely expected. What would matter is evidence that the Riverbend timeline, Texas approvals and cost discipline are all holding, because the $26.6 billion backlog is worth only as much as the company's ability to energize those data halls on schedule.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| Oct-26 | |
| Oct-25 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 |
