Millrose Lifts AFFO Outlook And Diversifies Past 40% Non-Lennar, But Leverage And A Lennar Rental Deal Cloud A Record Quarter
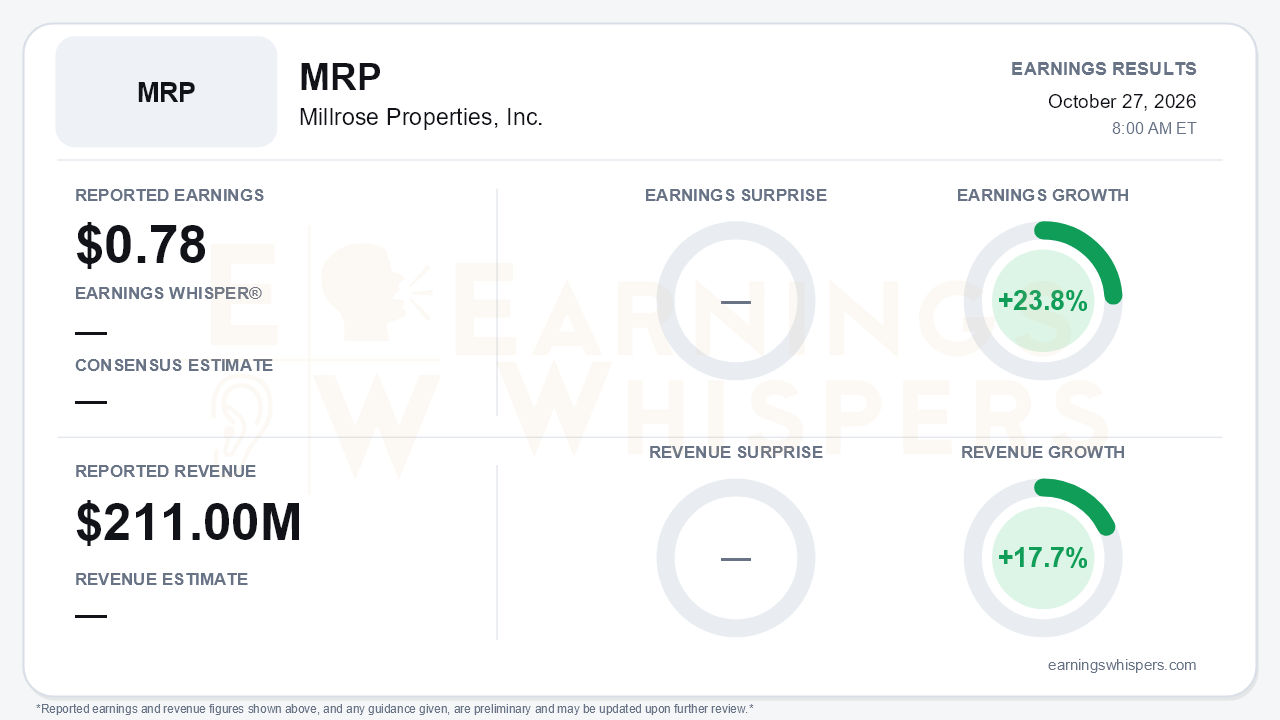
Millrose Properties (NYSE: MRP) posted record third-quarter net income of $130.0 million, or $0.78 per share. Earnings grew 23.8% from a year ago, and revenue rose 17.7% to $211.0 million. On the metric that matters most for this REIT, AFFO reached $0.80 per share. That compares with $0.77 in the second quarter, $0.76 in the first and $0.74 a year earlier, making it the sixth consecutive quarterly increase. Management raised its year-end quarterly AFFO run rate to $0.82 to $0.84 per share. Yet the quarter's central tension is not the earnings line. The cash-flow engine is clearly strengthening, but the company is funding that growth with more leverage, a rental pilot purchased from its anchor counterparty, and a revised payout framework. On the call, those moves pushed management into a defensive posture.
The quality of the headline growth deserves some scrutiny. GAAP EPS growth outpaced AFFO growth largely because amortization of deferred financing costs fell to $2.8 million from $16.4 million a year ago, which flattered the year-over-year GAAP comparison. The underlying driver is still solid:
- Option fee revenue climbed to $209.5 million from $170.3 million a year ago and $195.4 million in the second quarter.
- That gain more than offset a collapse in development loan income to $1.5 million from $8.9 million.
- Interest expense rose to $47.1 million.
- The implied quarterly income run rate on period-end invested capital is $221 million, comfortably above reported revenue. That gives the raised guidance a credible arithmetic foundation rather than leaving it as an aspiration.
The bigger operating story is diversification. Invested capital rose to about $9.2 billion from $8.8 billion. Lennar balances edged down to $5.87 billion as takedowns of $621 million exceeded redeployment of $546 million. Meanwhile, capital under Other Agreements grew $521 million to $3.4 billion. That business is also the higher-return book, yielding 10.8% versus 8.5% on Lennar capital. The Other Agreements yield turned back up after slipping to 10.6% in the second quarter, and management expects roughly 11% in the fourth. Counterparties now number 22, up from 15 at the end of last year. The roughly $1.1 billion Dream Finders/Beazer financing closed October 20 and has two parts:
- About $580 million of land banking on roughly 7,000 mostly short-duration homesites.
- A $488 million preferred position carrying a 12% dividend.
Pro forma for the deal, about 42% of the asset base sits outside the Lennar agreement, ahead of the greater-than-40% target set in February. Management also said builders are reloading land after same-store demand declined through June, and that industry margins have largely troughed.
Bears nonetheless have legitimate ammunition:
- **Leverage.** Debt-to-capitalization reached 36%, up from 26% at year-end, and is about 40% pro forma for Dream Finders. Both figures sit above the 33% target. Management's language has shifted from adhering to that target to being comfortable temporarily exceeding it. September's $1.0 billion senior notes, priced at 6.5% and 6.75%, lock in funding but at a meaningful cost. Liquidity stands at $0.8 billion.
- **The rental pilot.** The single-family rental pilot, 1,233 homes bought from Lennar for about $333 million, drew conflict-of-interest questions. Only about 10% of those homes are leased, and lease-up carry costs are expected to peak in the fourth quarter. The related rent-to-own initiative is now paused pending investor input, leaving strategic ambiguity.
- **Affordability.** A 10-year Treasury yield above 5% renews pressure on buyers, with management citing mortgage denial rates above 30% among prospective buyers.
Capital allocation added another layer. Management introduced a framework of distributing 90% of AFFO plus allocating 10% to buybacks while shares trade below book value, replacing the prior commitment to distribute 100% of AFFO. That change initially read as a dividend cut. Management clarified that the $0.79 quarterly dividend, itself raised again from $0.77, is not being reduced. The new $250 million repurchase program is to be funded without borrowing. Even so, the dividend of $131.2 million essentially consumed the quarter's $133.5 million of AFFO. Book value per share is flat at $35.24, so the buyback is as much a signal about valuation as a capital return.
The market setup reflects that skepticism. Shares opened at $28.99 after the August report, essentially in line with the current 200-day moving average of $28.83. Both levels sit well below the $35.24 book value that management is now explicitly using as a reference point for repurchases. Management acknowledged the market appears to be pricing in an earnings or dividend cut. The fundamentals reported this quarter do not support that reading, but the governance and leverage questions explain why investors have been reluctant to pay up.
The bottom line is that Millrose delivered what a yield-oriented investor should want: rising AFFO, a raised outlook, a sixth straight dividend increase and faster diversification into higher-yielding counterparties. The discount to book is less about earnings power than about trust. Elevated leverage, a Lennar-sourced rental experiment and a shifting payout framework have given the market reasons to question capital discipline. Delivering the $0.82 to $0.84 run rate while bringing leverage back toward target is likely what it will take to close that gap.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-17 | |
| Oct-15 | |
| Oct-13 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-23 | |
| Sep-22 |
