Watsco Misses As Margin Erosion Overwhelms A Real Volume Recovery, Even As Acquisitions Reshape The Story
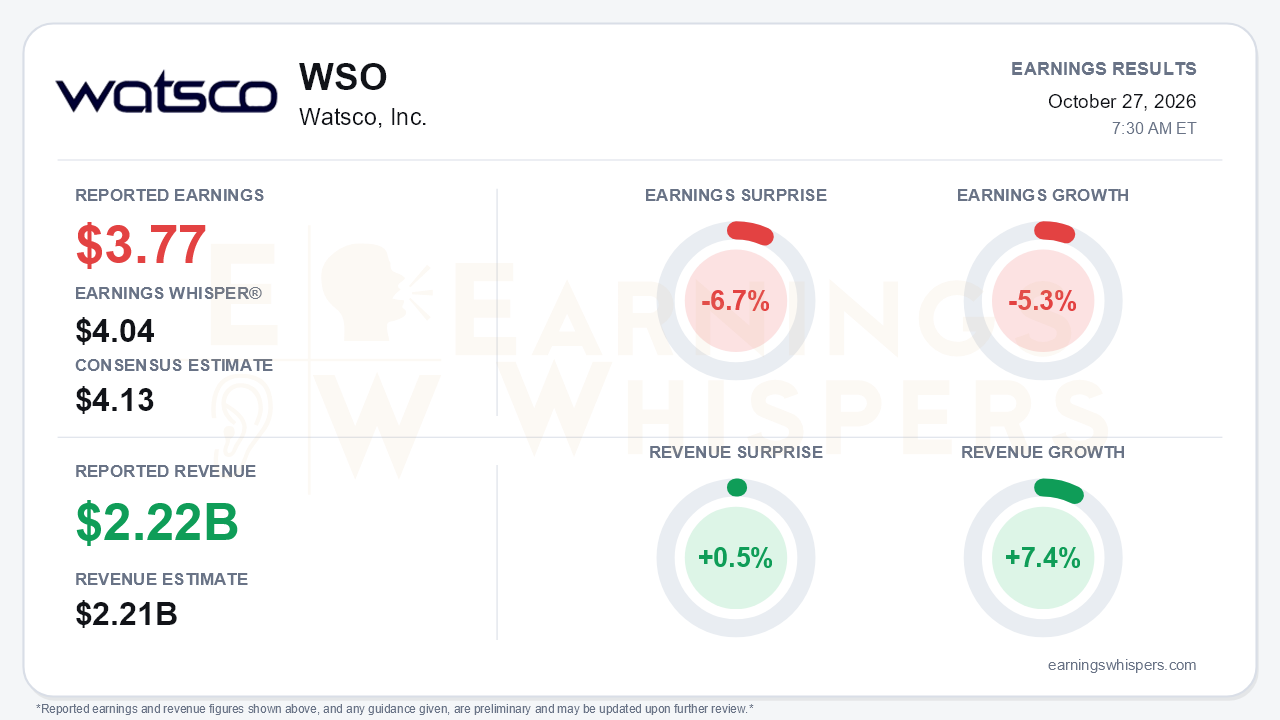
Watsco's third quarter shows a recovery in volume that has not yet produced earnings growth. The HVAC/R distributor reported earnings of $3.77 per share, missing the $4.13 consensus by 6.7% and falling short of the $4.04 Earnings Whisper number. Earnings fell 5.3% year over year. Revenue rose 7.4% to a record $2.22 billion, edging past the $2.21 billion consensus by 0.5%. Sales growth sped up meaningfully from the 2% pace of the second quarter, but earnings kept shrinking. That is the central tension: demand is clearly healing, while the profit Watsco earns on each dollar of that demand keeps slipping.
The miss came from gross margin, not the top line. Gross margin fell to 26.4% from 27.5% a year ago, which was also the second-quarter level, and from 28% for full-year 2025. Operating margin dropped to 10.1% from 11.4% a year earlier and from 11.2% in the second quarter.
Management attributed the erosion to several factors:
- a mix shift toward larger customers;
- stronger growth in residential new construction than in replacement;
- smaller, more conventional OEM pricing actions than in 2025;
- equipment outgrowing higher-margin non-equipment products;
- lapping last year's refrigerant shortage;
- dilution from Jackson Supply, whose margins run below Watsco's roughly 27% level.
Costs added pressure. SG&A rose 8% in total and 5% on a same-store basis, outpacing 4% same-store sales growth, and variable costs climbed about 10%. Diluted share count also rose to 38.6 million from 37.9 million. Management argued that third-quarter margin is more in line with historical seasonality and reflects current market conditions. That framing implies the margins of recent years were the outlier, a point bears will seize on given the call's reference to a 30% gross margin goal.
The operating trends, by contrast, were the best in some time:
- Same-store sales rose 4%, up from 1% in the second quarter.
- Residential equipment grew 7%, on 5% unit growth and a 2% higher average selling price, versus 5% growth in the second quarter.
- Add-on and replacement improved from roughly flat to up low single digits.
- Residential new construction swung from a second-quarter slowdown in Florida and Texas to growth in the low double digits.
- Organic sales have improved every month since May, and October total revenue was up double digits including acquisitions.
Commercial HVAC equipment remained a weak spot, down 5%. Management also acknowledged that industry units are still 10-15% below two years ago and that consumer affordability remains a concern. The recovery is real, but it is coming off a depressed base.
The forward story now leans heavily on acquisitions. Jackson Supply contributed $78 million in sales and grew 16% in its first quarter under Watsco. The Granite Group, acquired in October, adds roughly $500 million in annual sales and 82 Northeast locations, deepening an explicit push into dual-trade HVAC/plumbing. Together the two deals add about $730 million in annualized revenue, roughly 10% of the business. However, Jackson is already diluting margin, and Granite brings plumbing mix plus $140-150 million of added inventory.
Other catalysts include:
- expected 2027 OEM price increases tied to metal and freight inflation, which could help restore margin;
- the SupplySync institutional platform, now transacting with pilot customers;
- continued digital gains, with OnCallAir GMV reaching $2.0 billion.
E-commerce growth, however, has cooled to 12% year to date from 16% in the first quarter.
The balance sheet remains a strength. Cash and short-term investments total $649 million with no debt, and nine-month operating cash flow rose 79% to $304 million. Investors should look at where that cash came from. It was driven largely by a $383 million swing in payables that offset a $397 million inventory build, and third-quarter operating cash flow of $325 million actually trailed last year's $355 million. Inventory rose despite management's second-quarter remark that it had peaked.
The market had already priced in much of the margin concern. Shares entered the report at $305.33, down 11% from the open following the July report. They sat 16.9% below the 200-day moving average and roughly 10% above the 52-week low of $277.34 set on October 9. Investor sentiment was negative heading in and weakened only slightly, from -0.30 to -0.32, so expectations were already subdued rather than newly broken. The trend readings are mixed: the price trend is negative, while the AVWAP signal is positive.
The bottom line is that Watsco delivered the volume inflection bulls were waiting for but failed to convert it into earnings. Gross margin has fallen through a level that management now frames as normal, not cyclically depressed. The recovery in units, a steady October, acquisition-driven scale and potential 2027 price increases offer a credible path forward. Until mix pressure, Jackson dilution and SG&A growth stop outrunning sales, however, the quality of Watsco's growth will remain in question even as its quantity improves.
Read our earnings preview for Watsco, Inc.: https://www.earningswhispers.com/article/WSO/20733
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-12 | |
| Oct-09 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Aug-26 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jul-01 |
