Bladex Raises Growth Guidance Sharply On A $1B Panama Loan, But Flat EPS And A Lower Margin Outlook Complicate The Story
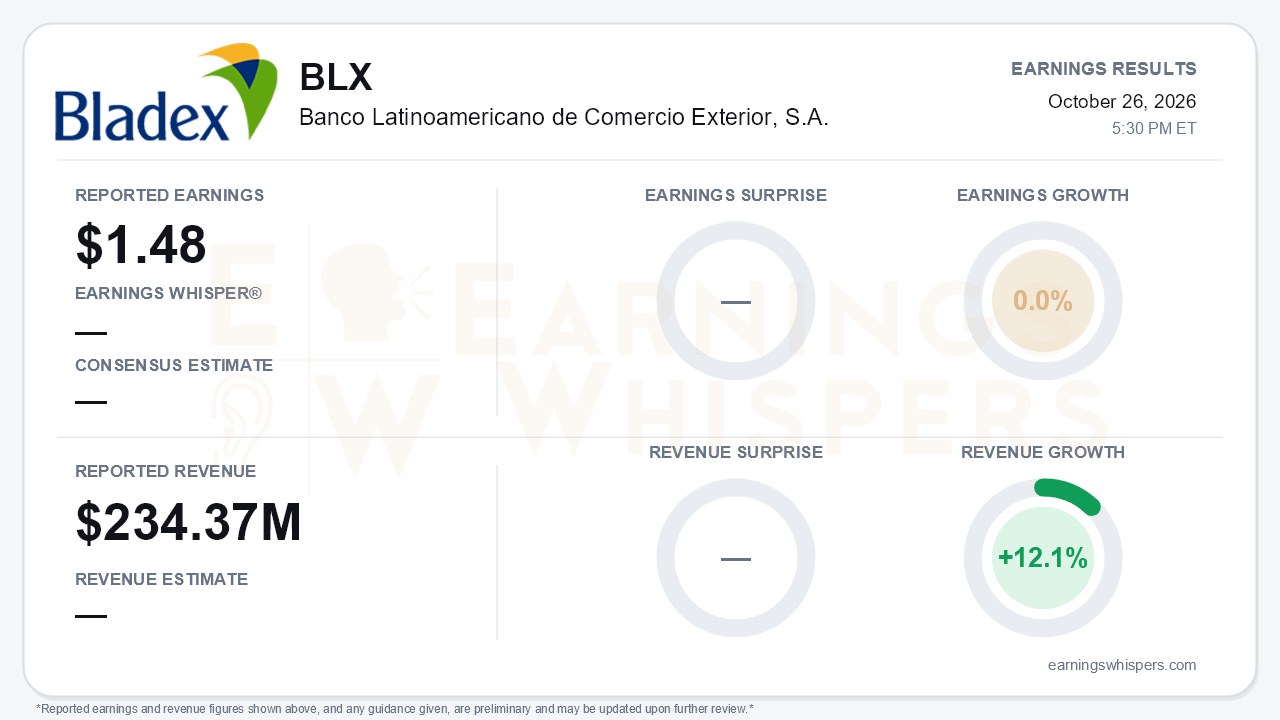
Bladex (NYSE: BLX) reported third-quarter earnings of $1.48 per share, unchanged from a year ago (0.0% growth). Revenue came in at $234.37 million, up 12.1% year over year on the Earnings Whispers basis. No consensus or Earnings Whisper estimate was available, so the quarter has to be judged on its trajectory rather than a beat-or-miss scorecard. That trajectory is the central tension. Net profit rose 15% to $63.2 million, and the balance sheet grew at a pace Bladex has not shown in years. Yet per-share earnings went nowhere year over year and fell 16% from 2Q26's $1.77. Management also trimmed its margin outlook while lifting its volume targets.
The gap between profit growth and flat EPS deserves scrutiny. The bank's EPS is calculated after deducting distributions on the AT1 instrument issued in late September 2025, so common shareholders saw none of the 15% profit gain on a per-share basis. Nine-month EPS of $4.56 is slightly below last year's $4.60, even though nine-month profit rose 9%. Note that Bladex's own total revenues, which net out interest expense, were $99.1 million, up 20% year over year but essentially flat from 2Q26. That is a different measure from the Earnings Whispers revenue figure. Within that $99.1 million, net interest income hit a record $79.8 million (+9% QoQ, +18% YoY). Net fees and commissions fell 30% sequentially to $16.3 million as an exceptional second quarter normalized. Provisions climbed to $10.4 million from $8.6 million in 2Q26 and $6.5 million a year ago. Operating expenses rose 20% year over year, though the 25.8% efficiency ratio remains lean.
The call explained how the business is changing, and the volume story is real. The commercial portfolio reached a record $15.0 billion, up 15% sequentially and 38% year over year. Growth has been building through the year: commercial portfolio growth was 13% year over year in Q1 and 20% in Q2. A $1 billion, one-year sovereign loan to the Republic of Panama drove much of the jump. Even excluding Panama, loans grew 7% sequentially and 29% year over year. Management raised full-year commercial portfolio growth guidance to roughly 35% (about 25% ex-Panama), far above the original 13-15% target. Deposit growth guidance rose to around 20%, and the efficiency target improved to about 27%. Asset quality also moved the right way sequentially:
- Stage 2 exposures fell to $82 million from $162 million in Q2 and roughly $300 million in Q1.
- No new Stage 3 credits emerged.
- Reserve coverage of impaired credits rose to 1.4x from 1.2x.
The margin picture is where bears have legitimate ammunition. Third-quarter net interest margin improved 6 basis points sequentially to 2.30%. However, deferred-fee acceleration from loan prepayments running two to three times normal flattered that figure, and the bank acknowledged the benefit is not recurring. Full-year NIM guidance was cut to about 2.25% from about 2.30%. A full quarter of the low-spread Panama loan will dilute fourth-quarter margins. Management also described LatAm credit markets as 'exuberant,' with ongoing spread compression on high-quality assets. Other risks flagged include:
- Panama now represents 17% of exposure.
- Post-election volatility and rising corporate defaults in Brazil.
- Seasonally higher fourth-quarter expenses.
- Management's statement that 2026's growth pace is exceptional and not expected to repeat, with no commitment on 2027 growth.
The year-over-year balance-sheet comparisons show what this growth has consumed:
- Assets-to-equity rose to 9.2x from 7.6x.
- Tier 1 capital slipped to 16.2% from 18.1%.
- The liquidity coverage ratio fell to 148% from 171%.
- Impaired credits rose to 0.4% of the portfolio from 0.2%.
- Reserve coverage dropped from 5.4x to 1.4x.
None of these levels is alarming, and Tier 1 fell only 40 basis points sequentially despite roughly $2 billion of asset growth. Still, Bladex is clearly trading capital and liquidity cushion for growth. The forward catalysts are tangible: the Panama loan should add meaningfully to fourth-quarter NII, and takeout facilities from structured deals are expected in late 2026 and early 2027. Other potential drivers include bridge-to-bond financing as LatAm debt markets slow, a cash management pilot onboarding early next year, and client derivatives, which doubled to $2.6 million ahead of a treasury platform launch.
Market context is limited. Bladex's quarter-end market capitalization of $2.07 billion was 11% below the end of 2Q26, implying the shares weakened during the quarter even as the balance sheet expanded. The stock opened at $59.77 after the July report, comfortably above its current 200-day moving average of $53.91. Current price and sentiment readings were not available to show where the shares stand heading into the fourth quarter.
The bottom line is that Bladex delivered a growth-heavy quarter with credible operating momentum. That includes record NII, a sharply higher volume outlook, better credit metrics, and a growing fee platform. However, the headline expansion masks thinner economics: flat EPS after AT1 costs, a margin guide moving lower, rising leverage and concentration, and management's own warning that this pace will not repeat. Investors should weigh the near-term NII lift from the Panama loan against the question of what earnings power remains once that one-year asset runs off.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-07 | |
| Sep-15 | |
| Sep-08 | |
| Aug-24 | |
| Jul-27 | |
| Jul-15 | |
| Jun-22 | |
| Apr-27 | |
| Apr-20 | |
| Apr-13 | |
| Mar-25 |
