Option Care Health's 30% Rally Puts CID Census Recovery To The Test
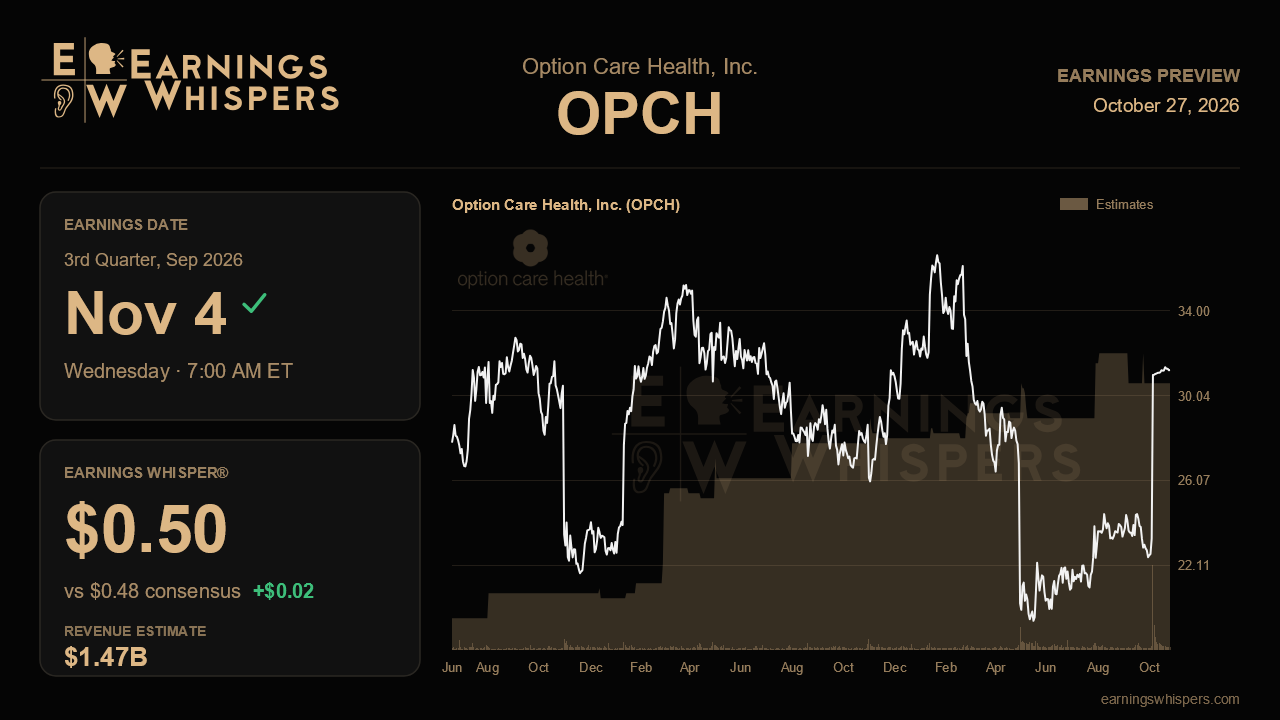
Option Care Health enters its third-quarter report with an awkward setup: the stock has priced in a recovery that management only began to describe three months ago. Since the infusion provider reported second-quarter results, shares have climbed about 30%, beating the S&P 500 by 27 percentage points. That rally followed a call in which management dropped its defensive tone from the spring reset tied to Stelara biosimilars and chronic inflammatory disease (CID). This report, due before the open on November 4, will show whether that turn was a real inflection or a single good quarter.
The Street expects non-GAAP earnings of $0.48 a share on revenue of $1.47 billion. That would be roughly 20% earnings growth from the $0.40 earned a year ago, on revenue up only about 2.4%. The gap between those two figures tells the story. Option Care is currently a margin story, not a top-line story. The earnings whisper of $0.50 sits a bit above consensus, which hints that some investors expect another modest beat. A two-cent gap is not a dramatic signal, but it does raise the bar slightly.
The guidance comparison is more revealing. Management narrowed its 2026 adjusted EPS range to $1.85 to $1.92 by lifting the floor, while keeping revenue guidance at $5.675 billion to $5.775 billion. Full-year consensus of $1.84 sits just below that guided floor, which suggests analysts remain cautious. Revenue expectations of $5.71 billion fall in the lower half of the range. If the third quarter lands as expected and management repeats the outlook, the Street may need to lift its numbers. A narrowing toward the upper half of the EPS range would further support the recovery case.
Operationally, the most important number is CID patient census. On the last call, management said census grew sequentially, the first sign that the first-quarter decline had bottomed. Management had previously admitted losing patients to competitors as formularies shifted toward biosimilars. A second straight quarter of census growth would support the stabilization story. A flat or falling count would revive concerns about competition and pressure from pharmacy benefit managers, including the mid-year CVS Stelara change. A related test is whether management keeps the CID gross-profit headwind at $55 million, well above the $25 to $35 million it first projected. Any further increase would undercut the idea that the worst is over.
Beyond CID, the bullish case depends on Acute care continuing its streak of high-single-digit growth above the market, and on IG/Neuro and Rare & Orphan sustaining gains. Chronic revenue was only flat year over year last quarter, so any improvement there would matter. The ambulatory infusion clinic expansion also deserves attention, after five new sites and a 20% jump in visits. So does cost discipline: SG&A fell 3% last quarter, helped by AI-driven automation in nurse routing, patient onboarding and claims processing. These efficiencies are what turn flat revenue into rising profit, so evidence that they are continuing matters as much as the headline numbers. Cash flow is also worth checking after the strong second quarter, given the $150 million buyback and $525 million left in the authorization.
Sentiment has improved but has not turned bullish. Bearish readings eased from 52% before the last report to about 36%. Meanwhile, the stock trades near $31.23, well above its 200-day average of $26.39 and just below its post-earnings high of $31.38. That puts the shares at the edge of a breakout, and the entire recent trading range sits above last quarter's peak of $22.83. Stocks positioned this way tend to punish uncertainty. The central question is whether CID census keeps growing while margins expand. If both hold, the recovery story stays intact. If either falters, the rally will have gotten ahead of the results.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-18 | |
| Oct-15 | |
| Oct-12 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 |
