Royalty Pharma Nears Record High As Third Straight Guidance Raise Becomes The Real Test
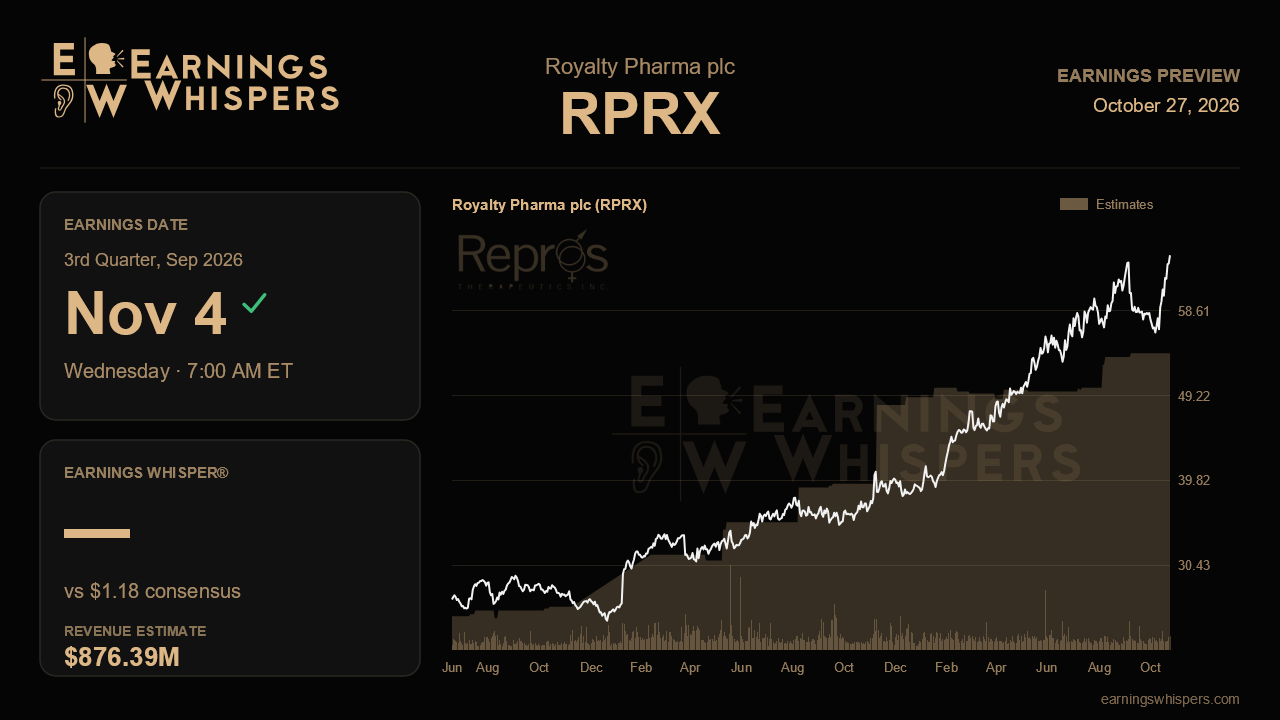
Royalty Pharma heads into its third-quarter report on November 4 with something it has not always enjoyed: momentum on both the operating side and in the stock. Management has raised its 2026 outlook twice in a row, the shares are pressing against their post-earnings high, and sentiment has swung decisively bullish. That combination makes this report less about whether the royalty machine is working and more about whether it is working well enough to justify another lift in expectations.
The consensus calls for earnings of $1.18 per share, essentially flat against $1.17 a year ago and below the $1.32 posted last quarter. Revenue is expected at roughly $876 million, a jump of about 44% from the year-ago $609 million. That headline growth figure looks far more dramatic than the business itself, and it sits awkwardly next to the near-flat earnings estimate, so readers should anchor on portfolio receipts, the cash metric management actually guides to. On that front, the company now expects 2026 receipts of $3.40 billion to $3.50 billion, up from $3.325 billion to $3.45 billion and an initial range of $3.275 billion to $3.425 billion. The Street's $3.44 billion full-year estimate sits comfortably inside that range, slightly below the midpoint, which leaves room for a modest upside surprise without requiring heroics.
The most important number in the release will be recurring royalty receipt growth. Last quarter it rose 14% even as Promacta and Imbruvica continued to fade, and management responded by lifting its full-year royalty growth outlook to 7% to 10%, up from 4% to 8% one quarter earlier and 3% to 8% at the start of the year. That is a steep progression, and it raises the bar. A third-quarter figure comfortably in the high single digits or better would confirm that newer products are more than offsetting the legacy roll-offs. A sharp slowdown would suggest the second quarter flattered the trend. Headline receipts growth decelerated to 6% last quarter because of a large prior-year milestone comparison, and with milestones and other contractual receipts expected to fall to about $60 million this year from $128 million in 2025, that optical drag should persist. The distinction between timing noise and underlying demand matters here.
Beyond the numbers, the pipeline narrative needs maintenance. Management added the Chloramatug royalty with AstraZeneca in ATTR cardiomyopathy, with peak royalties estimated at $110 million to $190 million, and highlighted Revolution Medicines' completed FDA submission for daraxonrasib in pancreatic cancer. Updates on regulatory timelines there, plus any read on the slower-than-expected event rate in the pivotal Pelacarsen trial due this year, will shape how investors value the roughly $2 billion of peak royalty potential across 19 development-stage therapies. Cost discipline is another quiet support: operating costs ran at 4.8% of receipts last quarter versus 8.9% in 2025, and keeping that ratio low preserves the earnings leverage. Policy overhangs, including drug-pricing proposals, China licensing legislation and the Vertex arbitration now pushed to around mid-2027, remain the obvious sources of cautious commentary.
The market has already rewarded the story. Shares are up 8.8% since the last report while the S&P 500 slipped 1.4%, and at $64.76 the stock trades within about 1% of its post-earnings high of $65.35 and well above its 200-day moving average near $52.57. Bullish sentiment has roughly doubled from the prior quarter. That positioning cuts both ways: confirmation could push the stock through resistance, but a merely in-line quarter may feel like a letdown.
Ultimately, the narrative hinges on whether royalty receipts keep growing fast enough to support the top half of the raised range. If management can tighten guidance upward again or signal the high end is within reach, the improving story stays intact. If it simply reiterates, a richly positioned stock may need to digest its gains.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-16 | |
| Oct-09 | |
| Sep-15 | |
| Sep-11 | |
| Sep-09 | |
| Sep-04 | |
| Aug-25 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-22 |
