Reynolds Faces Its Pricing Test As Commodity Costs Squeeze Third-Quarter Profits
Reynolds Consumer Products heads into its third-quarter report with a problem that productivity alone may not solve. Management has spent the past year wringing costs out of its plants and protecting margins, but a roughly $200 million annualized jump in aluminum and resin costs has pushed much of the company's 2026 plan onto price increases scheduled for the back half of the year. This is the first quarter where that bet starts to show up in the numbers, and it lands on a consumer the company itself has described as stretched.
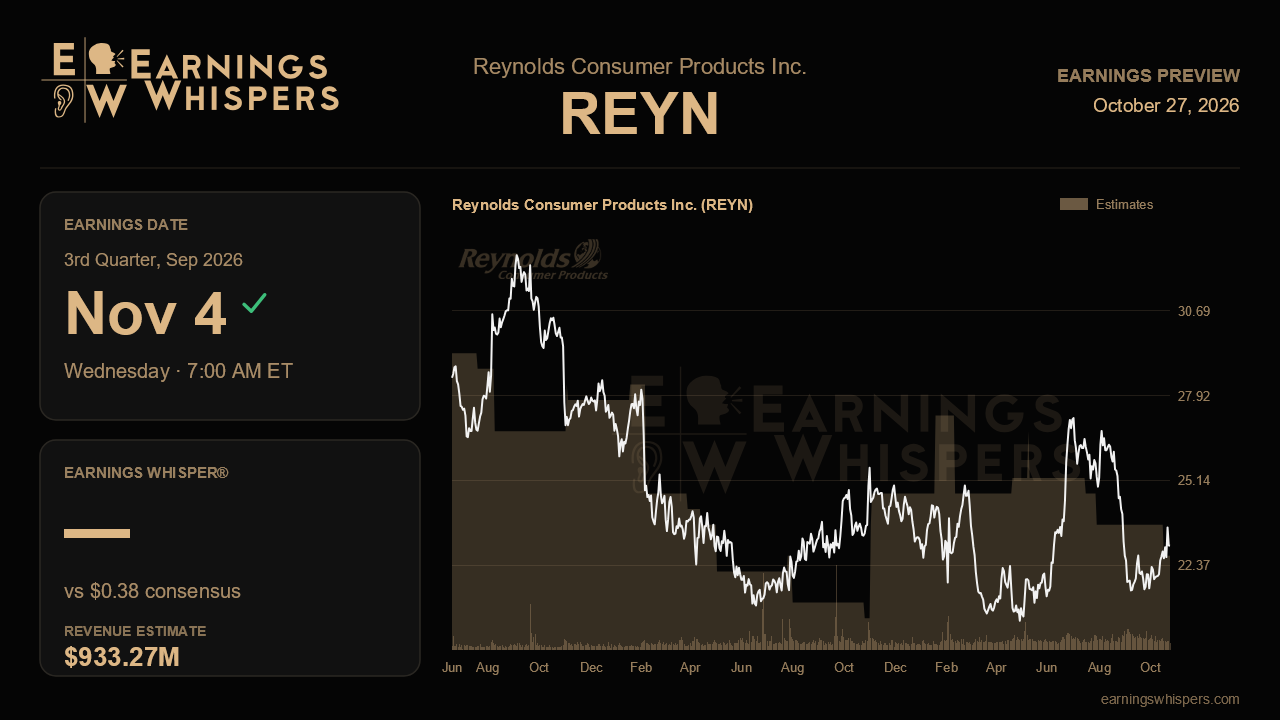
Wall Street expects earnings of $0.38 per share on revenue of about $933.3 million. That revenue figure is essentially flat with the $931 million posted a year ago, while the profit estimate represents a decline of roughly 9.5% from last year's $0.42. Put those together and the message is clear: analysts expect costs to outrun pricing this quarter, compressing margins even as sales hold steady. The full-year framework management laid out earlier, revenue ranging from down 3% to up 1% and adjusted EBITDA of $660 million to $675 million, roughly flat with 2025, already signaled a year of treading water. The latest call offered no visible update to that outlook, so any reaffirmation, narrowing or trim will carry real weight.
The most important detail will be how the revenue mix breaks down. Flat sales could mean pricing is landing and volumes are holding, which would be a solid outcome. It could also mean price increases are being offset by sliding volume, steeper promotions and lost private-label business, which would be a far less comfortable picture. Management flagged escalating promotional intensity in trash and food bags that worsened into the spring, and private-label dual-sourcing losses shaved about three points off first-quarter results. If promotions remain heavy, the company may find it difficult to make new list prices stick in its biggest categories. Foam and tableware, a discretionary business that has been shrinking, is another place where a pressured shopper will show up first.
There is a credible counterweight. Cost discipline has been the company's strongest suit, with first-quarter gross margin improving by about 60 basis points and adjusted EPS rising 20%. Leverage has fallen to around 2.1 times, and free cash flow last year reached $316 million. On the growth side, e-commerce is becoming a real contributor, with Hefty Ultra Strong ranking among the top Prime Day sellers and Hefty food bags growing about 30% online. Continued distribution wins across the newly realigned Hefty segments and the Reynolds Countertop Prep Paper launch give management something to point to beyond cost cuts. Evidence that these initiatives are adding measurable volume would help validate the claim that share is holding in most categories.
The market has not given Reynolds much benefit of the doubt. Shares have fallen about 6.9% since the last report while the S&P 500 gained 3.4%, a gap of more than 10 points. At $23.01, the stock sits just below its 200-day moving average and in the lower half of its post-earnings range of $21.27 to $26.94. Sentiment remains bearish, though modestly less so than heading into the prior report, suggesting low expectations rather than outright alarm.
Ultimately, this report hinges on whether pricing is beginning to cover commodity inflation without breaking volume. A modest earnings decline paired with stable volumes, firmer gross margin trends and a reaffirmed full-year range would keep the steady-compounder narrative intact. Heavier promotional spending, further private-label erosion or a cut to the EBITDA outlook would suggest the cost squeeze is winning, and that the back-half recovery the plan depends on is slipping away.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Aug-26 | |
| Aug-17 | |
| Jul-29 | |
| Jul-29 | |
| Jul-23 | |
| Jul-08 | |
| May-06 | |
| May-06 | |
| Apr-30 | |
| Apr-16 | |
| Apr-15 | |
| Mar-24 |
