Acme United Beats On A Tariff-Refund Boost, But Accelerating Organic Growth Is The Real Story
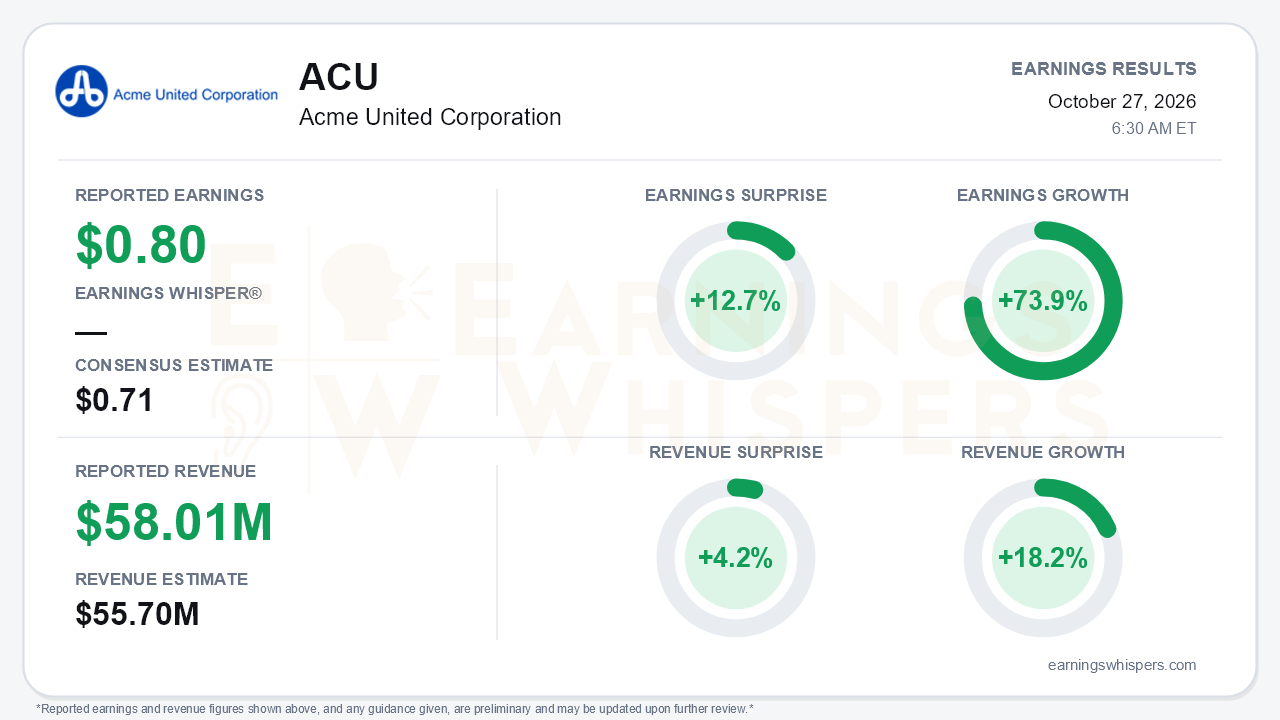
Acme United (NYSE American: ACU) reported third-quarter earnings of $0.80 per diluted share, beating the $0.71 consensus by 12.7% and growing 73.9% from a year ago. Revenue rose 18.2% to a record $58.01 million, topping the $55.7 million consensus by 4.2%. The headline beat is real, but it is heavily flattered. The cleaner story is underneath: organic sales growth accelerated for a third straight quarter, and gross margin recovered as tariff-burdened inventory cleared. That is the central tension. The earnings surprise overstates the quarter, while the operating trajectory may be better than the surprise alone suggests.
The quality of the beat deserves scrutiny. Acme received $6.0 million in IEEPA tariff refunds. It recognized $4.0 million as a reduction to cost of goods sold, worth roughly 690 basis points of gross margin, and booked the remaining $2.0 million as an accrued liability. Two items partially offset that gain:
- $1.8 million of costs tied to closing the DMT sharpening facility, about 310 basis points of gross margin.
- $1.0 million of refund-related variable compensation in SG&A.
The quarter also included roughly $0.4 million of tax benefits from stock option exercises. The call analysis put adjusted EPS at $0.55, up 20% from $0.46. That figure would sit below the $0.71 consensus, although it is unclear whether estimates incorporated the refund. Either way, investors should treat the GAAP number as a one-time high-water mark rather than a new run rate.
Stripped of those items, the trend still improved. Organic sales growth, excluding the My Medic acquisition, stepped up from 6% in the first quarter to 8% in the second and 10% in the third. Total growth followed the same path, rising from 14% to 16% to 18%.
- **U.S.:** Sales rose 20%, about 10% organically, on strong back-to-school demand and full promotional activity.
- **Canada:** Growth accelerated to 12% in local currency from 3% in the second quarter, driven by first-aid products.
- **Gross margin:** Underlying margin was roughly 42.1%, compared with 39.1% a year ago. That matches management's earlier prediction that tariff-burdened inventory would clear by the third quarter.
Management's tone moved from "difficult" in the first quarter to "excellent" now. Management pointed to 2027 first-aid business already booked and Spill Magic growth of about 34% year to date.
Bears still have legitimate ammunition:
- **Europe:** Growth slowed sharply to 7% in local currency from 19% in each of the first two quarters.
- **SG&A:** Expenses climbed to 37.6% of sales, compared with about 32% in the second quarter, on My Medic advertising and the refund-related compensation.
- **Costs:** Management said freight from China has tripled and that transportation and raw material costs are rising.
- **Easy comparisons:** Management conceded that Westcott is lapping easy comparisons against a tariff-disrupted 2025.
- **Consumer:** Management flagged consumer stress from energy costs, interest rates and mortgages as a caveat for 2027.
- **Balance sheet:** Inventories rose to $69.0 million from $60.2 million, and receivables are up about 20%. The release puts net bank debt at $29.7 million, against $23.1 million a year earlier. The call analysis cites $29.5 million, a minor discrepancy.
- **Cash flow:** Trailing free cash flow of $13.8 million includes the $6.0 million refund, and the call figure of about $13 million slipped from about $15 million cited last quarter.
The forward catalysts are concrete:
- The DMT plant closure is expected to save more than $1.0 million annually starting in 2027.
- An RFID-enabled smart compliance first-aid kit ships in January 2027.
- My Medic, which generates most of its profit in the fourth quarter, should finally show up in earnings this quarter.
- Management expects to convert roughly $8 million to $10 million of buffer inventory to cash during 2027.
- Management expects at least one acquisition within 12 months.
No formal numeric guidance was provided.
The market setup is more complicated than the surprise implies. Shares closed at $63.58 the day before the report, up 32.5% from the $48.00 open after the July release. That left the stock about 27.7% above its 200-day moving average and just 2% below the 52-week high of $64.87 set on September 29. Investors entered the print having already rewarded the recovery. Investor sentiment improved from -0.28 to -0.21 but remained negative, a modest shift that suggests skepticism has eased without disappearing. The Earnings Whispers trend signals are mostly positive on price, momentum and AVWAP, while sequential growth reads neutral. That mix fits a stock that has rallied ahead of fundamentals that are improving but not yet uniformly accelerating.
The bottom line is that Acme United's 12.7% beat was manufactured largely by a one-time tariff refund, but the business beneath it is genuinely strengthening. Organic growth is accelerating and gross margin is recovering, and management is leaning into 2027 with booked orders and cost savings. With the stock already near its highs and sentiment still cautious, the next test is whether My Medic's fourth-quarter seasonality, European growth and rising freight costs allow underlying earnings to justify the rally without help from refunds.
Read our earnings preview for Acme United Corporation: https://www.earningswhispers.com/article/ACU/20675
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Sep-22 | |
| Sep-18 | |
| Sep-16 | |
| Jul-30 | |
| Jul-23 | |
| Jul-23 | |
| Jul-15 | |
| Jul-15 | |
| Jun-17 | |
| May-20 | |
| May-15 | |
| Apr-24 |
