Travelzoo Misses Badly On Earnings As Membership Push Deepens Losses, But Record Club Adds And A $30 Million 2027 Fee Target Keep The Thesis Alive
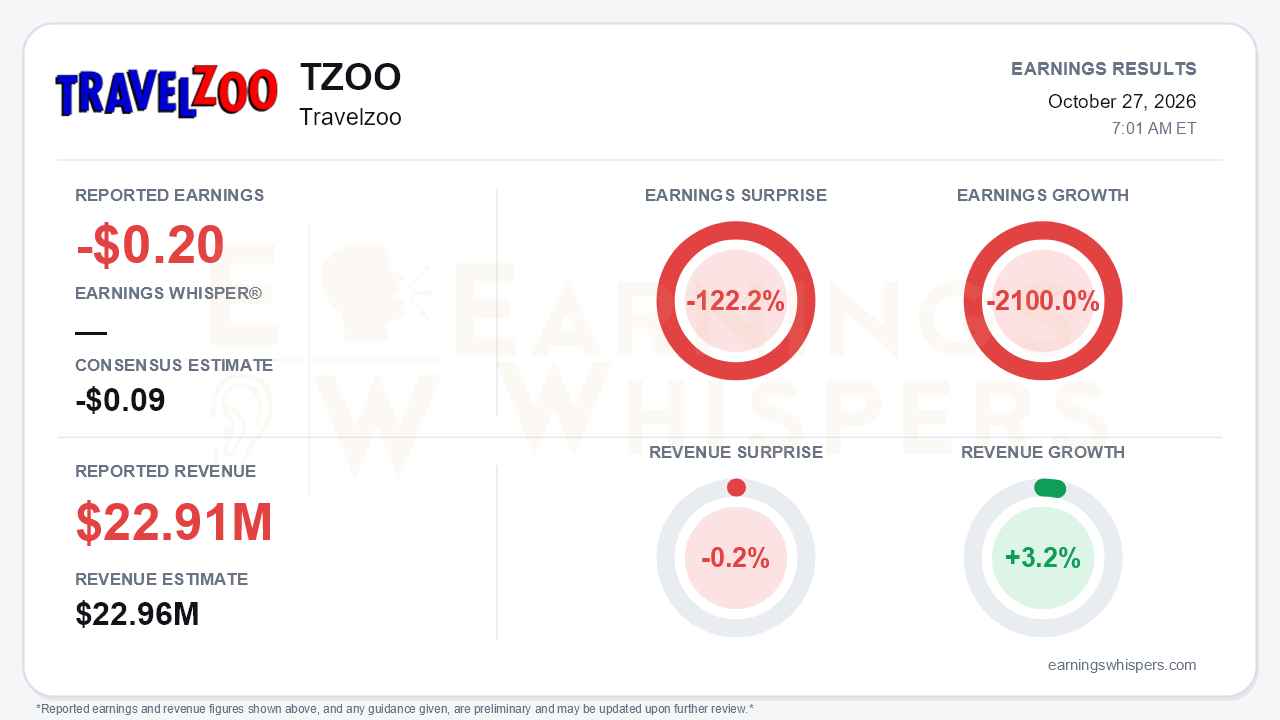
Travelzoo (NASDAQ: TZOO) reported a third-quarter loss of $0.20 per share, well short of the -$0.09 consensus. That is a 122.2% miss and a swing from a $0.01 profit a year ago, which works out to a 2100.0% year-over-year earnings decline. Revenue of $22.91 million rose 3.2% but slipped 0.2% below the $22.96 million consensus. The headline is plainly negative. The central tension is that Travelzoo is deliberately expensing its way through a business-model transition. Marketing costs hit the income statement immediately, while membership fees are recognized ratably over 12 months. Q3 showed both the cost of that strategy and the strongest evidence yet that it is building something.
The quality of the loss deserves scrutiny, because it extends beyond marketing. Sales and marketing jumped to $14.6 million from $12.2 million, and cost of revenues climbed 27% to $5.7 million. As a result, gross profit actually fell to $17.2 million from $17.7 million despite higher revenue. North America, historically the profit engine, swung from a $1.1 million operating profit to a $1.4 million loss. Europe's loss nearly doubled to $1.2 million, or 18% of revenue. The GAAP operating loss was $2.6 million, and the non-GAAP loss was $2.1 million versus a $1.1 million profit a year earlier. A $436,000 tax benefit kept the net loss from looking worse. Jack's Flight Club revenue fell 15%, which management attributed to fewer members acquired in the first half. Meanwhile, total Travelzoo stockholders' deficit widened to roughly $15.0 million.
Beneath the losses, the operating trends improved. Revenue growth returned to +3% after Q2's 3% decline, which management tied to geopolitical conflicts. However, growth remains below Q1's +5% and the +9% posted in Q4 2025, so this is a recovery rather than a clean acceleration. Club Members rose 65% year over year on the largest quarterly additions in company history. That growth rate is lower than earlier triple-digit rates, but those came off a much smaller base. The more encouraging detail was efficiency. U.S. acquisition cost fell to $54 from $62 in Q2 even as spend increased, and 90-day transaction revenue held at $15 per member. Cash also rebounded to $8.8 million from $7.6 million, as promised on the prior call. Operating cash flow was $1.8 million versus a $374,000 outflow a year ago, accounts receivable normalized, and the company still repurchased about 257,000 shares.
The forward story is where management leaned in. Deferred revenue stands at $13.5 million, up from $8.7 million at year-end. Management newly framed membership fee revenue rising from about $17 million to roughly $30 million in 2027, and reiterated an expected $1.20 incremental EPS effect in 2027. Guidance for year-over-year revenue growth in Q4 was maintained. Those targets are management expectations, not results, and bears have legitimate ammunition:
- Deferred revenue growth decelerated in Q3 because new members start on trials and convert only after 30 days.
- Acquisition cost remains roughly double Q1's $27.
- Travelzoo META has now slipped from Q2 to Q3 to Q4 2026, which erodes credibility on timelines.
Management also flagged AI-agent discoverability of paywalled Club Offers via ChatGPT and Google as an opportunity. At the same time, AI travel agents and European unrest are disruptive forces in deal discovery.
Management's tone was noticeably more confident than on the defensive Q2 call, and investor sentiment moved modestly in the same direction. Sentiment improved from -0.085 to -0.058, still slightly negative and far from enthusiastic. The stock tells a harsher story. Shares entered the report at $5.12, down 24.4% from the $6.77 open after the July report and 35.1% below the inter-earnings high of $7.88 set that same day. They sit 31.5% below the $7.47 200-day moving average and just 4.6% above the October 16 low of $4.89. The Earnings Whispers trend signals remain mostly negative, with price, momentum, and AVWAP readings all weak. The market has been pricing in skepticism about the transition rather than giving credit for member growth.
The bottom line is that Travelzoo delivered a genuinely poor GAAP quarter, with a wide earnings miss, shrinking gross profit, and segment losses in both major regions. The underlying membership machine nonetheless looked healthier, with record adds, falling acquisition costs, rising deferred revenue, and better cash. The investment case now rests almost entirely on whether 2027 membership revenue materializes near management's roughly $30 million framing. With shares near their quarterly lows and well below long-term trend, investors are clearly demanding proof rather than promises. Continued META delays and stubbornly high acquisition costs would make that proof harder to deliver.
Read our earnings preview for Travelzoo: https://www.earningswhispers.com/article/TZOO/21332
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-24 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-15 | |
| Oct-01 | |
| Sep-22 | |
| Sep-11 | |
| Aug-27 | |
| Aug-27 | |
| Aug-27 |
