United Therapeutics Must Show Tyvaso Can Hold Ground As Rally Outpaces Sentiment
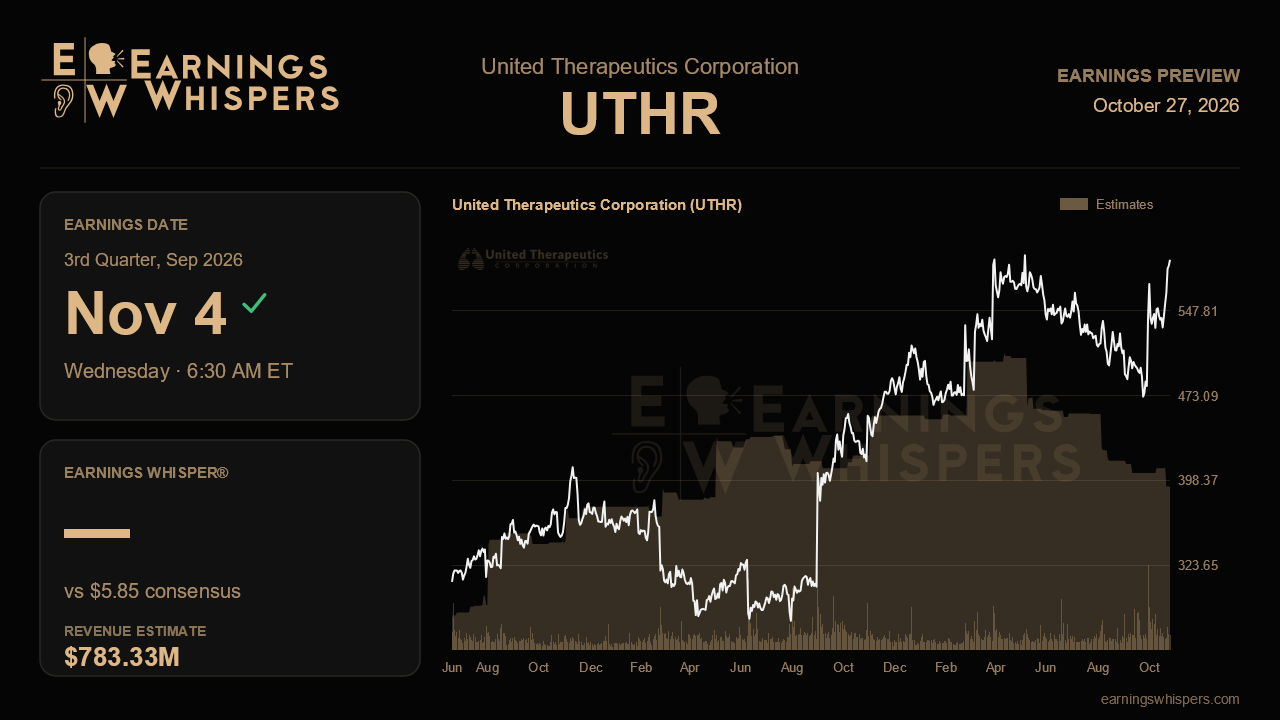
United Therapeutics heads into its third-quarter report with an unusual disconnect. The stock has climbed roughly 17% since the last earnings release while the S&P 500 slipped, yet the commercial story that sent it there has rarely looked shakier. Last quarter management called revenue below its own expectations, conceded that nebulized Tyvaso is feeling competitive pressure, and stopped reaffirming its 2026 growth outlook. The rally has been built on the pipeline. This report will show whether the base business can stop leaking while investors wait for 2027.
Wall Street is not asking for much. Consensus calls for earnings of $5.85 per share on revenue of $783.3 million. That revenue figure matches the second quarter almost exactly and sits about 2% below the year-ago $799.5 million, so analysts are effectively modeling a third straight quarter of stagnation. The earnings estimate is more striking: an 18% decline from last year's $7.16 and well below the $7.27 posted last quarter. Part of that gap likely reflects the cost of a sales force management roughly doubled, with reps in the field by early July, along with heavy spending on late-stage programs. With no formal guidance in place, the consensus is the only bar, and it is a low one.
The central operating question is Tyvaso. Total Tyvaso revenue has drifted lower for several quarters, landing at $453 million in the second quarter, and management's description of nebulized Tyvaso as pressured by competition reversed earlier assurances that the Yutrepia launch was having no material effect. Against that, the company said Tyvaso DPI starts, referrals, and total and commercial patient counts all hit records exiting the quarter. If those demand metrics are real, they should begin translating into revenue now, especially with a larger sales force calling on prescribers. A Tyvaso line that stabilizes or ticks up would validate the argument that DPI growth can offset nebulizer erosion. Another sequential decline would suggest the competitive damage is outrunning the record patient counts, and would raise fresh doubts about what the expanded commercial team is buying.
The longer-range target matters too. The company's goal of a $4 billion annualized revenue run rate by the end of 2027 was once framed as achievable on the existing portfolio alone. Last quarter it became a path that has certainly narrowed and now leans on launches of nebulized Tyvaso in idiopathic pulmonary fibrosis and Rilinopag in pulmonary arterial hypertension, both filed with potential approvals in 2027. Any update on regulatory timelines for those filings, progress toward completing enrollment in the TETON study in progressive pulmonary fibrosis, and news on the initial six-patient UKidney EXPAND cohort expected this year will help investors judge how much of the target rests on hope. The new Thymune acquisition and the cleared Express uHeart study add optionality but little near-term revenue.
Positioning is a curious mix. Sentiment has cooled sharply, sliding to barely positive from about 22% bullish ahead of the last report, even as the share price trades near $593, just under its post-earnings high of $593.50 and well above its 200-day average near $529. The stock is testing a breakout, though it still sits below the prior quarter's peak above $609. That combination suggests the market has priced in the pipeline while remaining skeptical of the near term.
Ultimately, this quarter turns on whether management's sober new emphasis on execution shows up in the numbers. Flat revenue and a cost-driven earnings dip are already expected. What the stock needs is evidence that record DPI demand is finally reaching the top line and that competition in nebulized Tyvaso has been contained. Without that, the narrative rests entirely on 2027 approvals, and a stock pressing against its highs may have little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 |
