PECO Hits The Whisper With Its Strongest Growth Of The Year, But A Softer Q4 Setup And A Sliding Stock Temper The Story
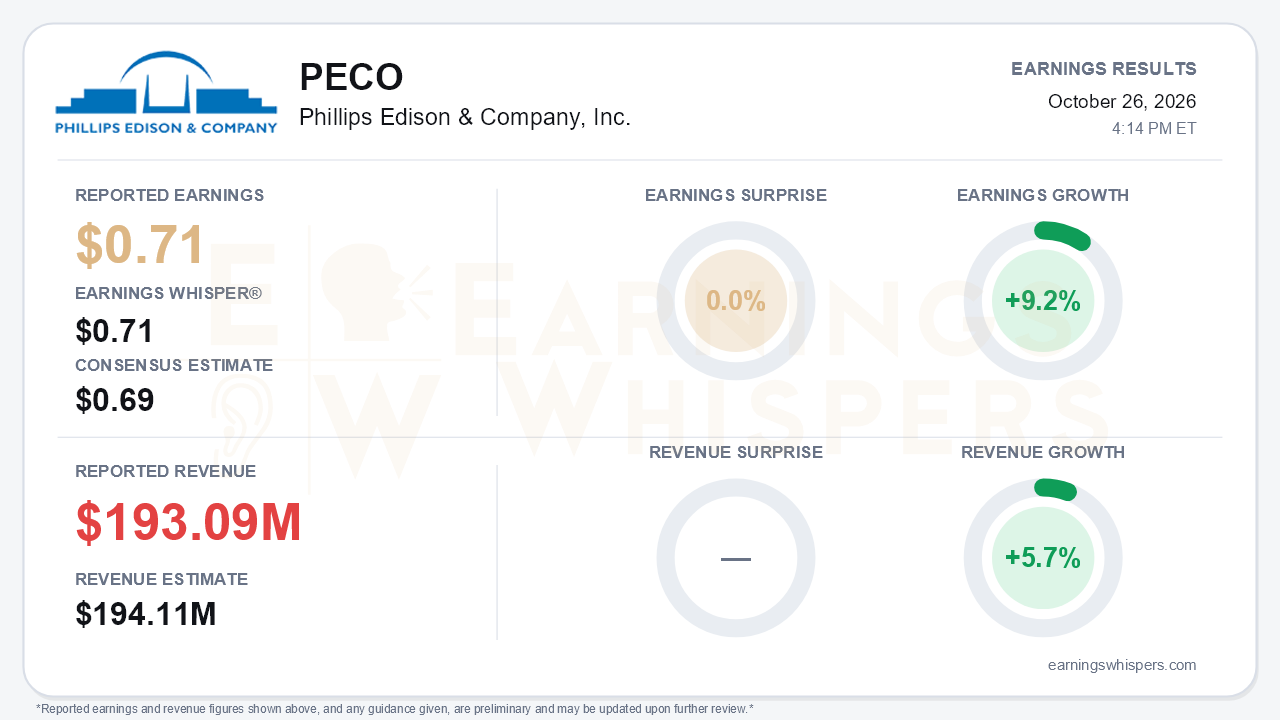
Phillips Edison & Company delivered exactly what the most demanding expectations required, and its growth rate improved again. Core FFO of $0.71 per share matched the Earnings Whisper number and topped the $0.69 consensus. Earnings grew 9.2% year over year, up from 7.8% in the second quarter and 6.2% in the first, making this the grocery-anchored landlord's strongest quarter of 2026. Revenue of $193.09 million rose 5.7% but missed the $194.11 million consensus by 0.5%. That modest top-line miss is not the central issue. The central tension is that the operating story keeps strengthening while the stock has done the opposite, falling 12.4% since the last report.
The quality of the quarter is mostly solid, with some caveats. Same-center NOI rose 5.3%, accelerating from 3.8% in Q2 and 3.5% in Q1. Same-center revenue grew 4.4%, while operating expenses rose only 1.9%. Reserves for uncollectibility were roughly flat. GAAP net income of $0.49 per share, up from $0.20, flatters the picture because it includes $40.6 million in disposal gains, which is why FFO is the better gauge here. Leasing volume deserves scrutiny. PECO signed 238 leases covering 1.1 million square feet, down from 270 leases and 1.7 million square feet a year ago. Comparable new-lease spreads fell to 26.3% from 33.7% in Q2 and 36.2% in Q1, which management attributed to deal timing. Renewal spreads, by contrast, hit a record 25.2%, and retention improved to 92.2% from 88% in Q1. Pricing power on existing tenants is intact.
Guidance is where the headlines diverge. Earnings Whispers characterizes the update as a narrowing, and that is technically accurate. The Core FFO range moved to $2.75 to $2.79 from $2.73 to $2.79, and the Nareit FFO range moved to $2.68 to $2.72 from $2.67 to $2.72. The top ends did not move. Management framed the update as a fourth consecutive raise. The Core FFO growth midpoint has stepped from 5.4% to 5.8% to 6.2% to 6.5% over four calls, and the same-center NOI midpoint edged up to 3.75%. Both readings hold, but the arithmetic matters. Against $2.09 of year-to-date Core FFO, the $2.77 midpoint implies a fourth quarter around $0.68, below Q3's $0.71. Full-year same-center NOI guidance of 3.5% to 4.0%, compared with 4.3% year to date, likewise implies a sharp Q4 moderation, which management tied to the timing of expense recoveries. Nareit FFO growth guidance was held at 6.3%.
The forward-looking developments are where the call preserved a credible growth story. Management raised gross acquisition guidance three times this year, to $600 million to $700 million. It has closed $519 million year to date, with roughly $250 million more awarded or under contract. The expanded Northwestern Mutual joint venture, scaled to about $800 million and funded in tranches through January, lets PECO match-fund acquisitions without leaning on equity. That matters because the company issued ATM shares at about $42, well above today's $38.60. A new $350 million term loan at SOFR plus 80 basis points lifts pro forma liquidity to about $950 million. Other catalysts include:
- a Kroger ground-up development partnership;
- a $1 billion Everyday Retail target pulled forward to 24 months;
- a development and redevelopment pipeline grown to about $90 million;
- a 6.2% dividend increase;
- a December 16 business update that management has flagged as previewing strong 2027 growth.
Management's tone was notably assertive, citing "no signs of weakness" heading into 2027. Bears still have legitimate ammunition. Fixed-rate debt fell to about 85% from 95.9% after a $200 million swap expired and the floating-rate loan was added. In-line leased occupancy slipped to 95.1% from 95.5% as lower-occupancy acquisitions entered the portfolio. Management also flagged isolated tenant credit events, including Leslie's and a Wendy's franchisee, along with rising competition for acquisitions.
Investors have cooled noticeably. Earnings Whispers sentiment stays positive but fell from 0.47 to 0.13, a meaningful step down. Shares opened at $44.05 after the July report and now sit 1.3% below the 200-day moving average of $39.12. The trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative, consistent with improving fundamentals failing so far to stop the stock's slide.
The bottom line is that PECO's quarter was better than its in-line label suggests. FFO growth, same-center NOI and renewal economics all accelerated, and the external-growth machine is now funded more cheaply. The market setup is more complicated than the clean whisper match implies. Q4 guidance points to a sequential step down, new-lease spreads and leasing volume softened, and both sentiment and price have deteriorated. The December 2027 outlook now carries the burden of showing that Q3's acceleration is durable rather than a timing-aided peak.
Read our earnings preview for Phillips Edison & Company, Inc.: https://www.earningswhispers.com/article/PECO/20664
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-28 | |
| Sep-08 | |
| Sep-08 | |
| Sep-01 | |
| Aug-17 | |
| Aug-05 | |
| Aug-03 | |
| Jul-24 | |
| Jul-23 |
