Ares Capital Misses As Core EPS Slips Below The Dividend, Leaning On The MFIC Deal And A Rebounding Pipeline To Change The Story
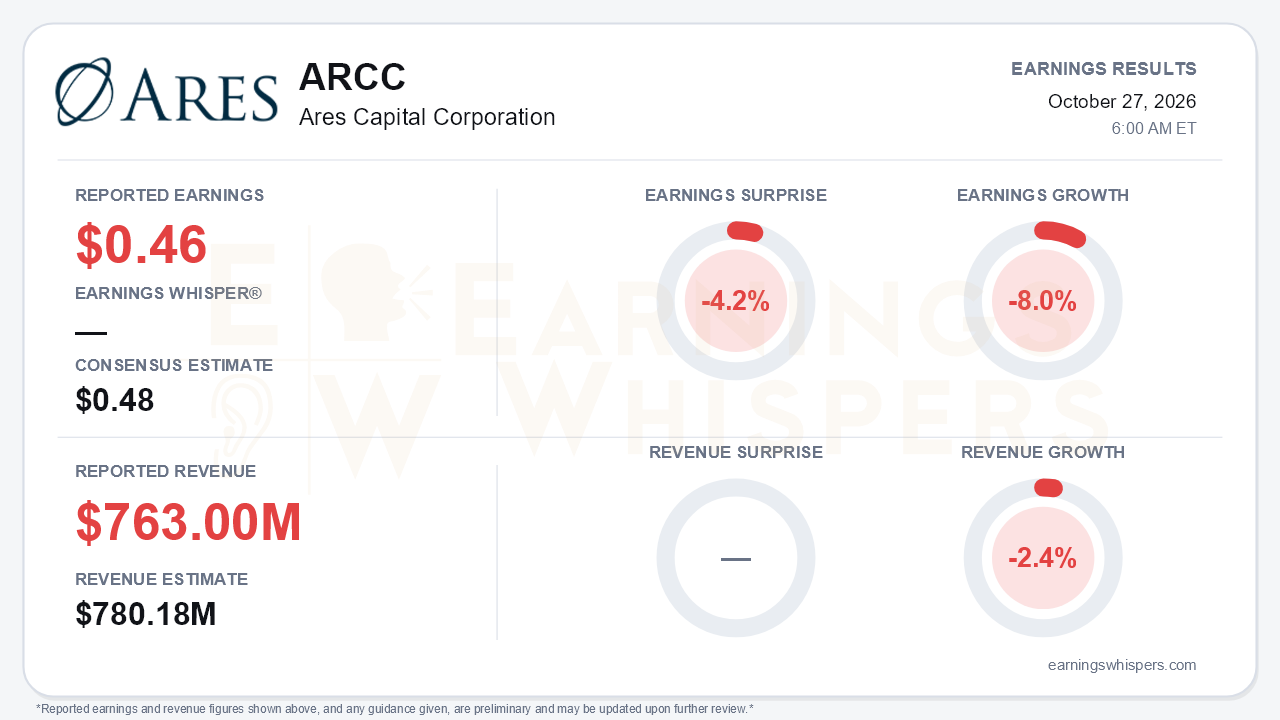
Ares Capital (NASDAQ: ARCC) reported third-quarter core earnings of $0.46 per share, 4.2% below the $0.48 consensus and down 8.0% from a year ago. Revenue of $763.0 million missed the $780.18 million estimate by 2.2% and fell 2.4% year over year. The miss is modest, but it carries a specific consequence. Core EPS now sits below the $0.48 quarterly dividend, so the payout depends on roughly $1.37 per share of spillover income. That is the central tension. Management paired a quarter of softer earnings power with an acquisition and a stronger pipeline meant to rebuild it.
The quality of the quarter deserves scrutiny in both directions. Core EPS has drifted steadily lower, from $0.50 a year ago to $0.47 in each of the first two quarters and now $0.46. Lower capital structuring fees were a specific drag. GAAP EPS of $0.44 was a sharp improvement from $0.24 in Q2 and $0.13 in Q1, which suggests the heavy markdowns earlier in the year have largely stopped. NAV per share tells the same story. It edged down only to $19.31 from $19.35, after falls of $0.24 in Q2 and $0.35 in Q1. Book value is stabilizing rather than recovering, and it remains well below where the year began. Non-accruals were flat sequentially at 2.4% at cost and 1.4% at fair value. They are still up from 1.8% a year ago.
The call explained why earnings power faded. Originations fell to $2.1 billion from $2.6 billion in Q2, $3.2 billion in Q1 and $3.9 billion a year earlier. Management cited elongated M&A processes and macro and geopolitical volatility. Net leverage drifted to 1.06x from 1.12x, and portfolio fair value slipped to $29.2 billion. Borrower fundamentals are cooling as well. Organic LTM EBITDA growth across the portfolio decelerated again to about 7%, down from roughly 8% in Q2, 9% in Q1 and more than 10% a year ago. Software, previously a standout, is now growing only in line with the portfolio.
The forward picture is more constructive than the quarter itself. Q4-to-date commitments of $1.1 billion compare with about $200 million at the same point earlier this year, and the backlog stands near $2.5 billion. Management described those levels as historically strong. New first-lien spreads widened 50 basis points sequentially at half a turn lower leverage, which points to better risk-adjusted terms on new loans. Funding costs are also falling. Management cited about 70 basis points of savings from commercial paper, a 35-basis-point securitization reset and a $750 million seven-year note priced at T+185. Liquidity rose to about $7 billion, and management estimates each 100-basis-point rise in base rates adds about $0.02 per share per quarter starting in Q4.
The MFIC acquisition is the headline catalyst. ARCC will pay $10.88 per MFIC share, made up of roughly $9.67 in ARCC stock and $1.21 in cash funded by Ares Management. The price represents a 30.1% premium to MFIC's last close but a meaningful discount to MFIC's preliminary $12.86 NAV estimate. That discount underpins management's expectation of modest accretion to core EPS. The deal adds about $2.5 billion of assets and 229 companies, with only 12 overlaps, and lifts the pro forma portfolio above 800 companies and $31 billion in investments. A $750 million Wells Fargo financing commitment supports the transaction, and closing is targeted for the first half of 2027. The risks are real, however:
- MFIC's tail assets sit in the core middle market, where spreads are compressing.
- Any accretion arrives only after closing.
- Maturity walls of about 10% of the portfolio in 2028 and 13% in 2029 add refinancing risk if higher rates pressure borrowers.
Investor sentiment improved from -0.16 to -0.10 ahead of the report but remains negative. That reflects lingering caution rather than conviction. Shares closed at $18.61 before the announcements, down 2.6% since the open after the prior report. That left the stock 2.4% below its 200-day moving average and 8.0% below its late-August high of $20.23. It sits just 1.7% above its October 7 low of $18.30, so the stock entered the report near the bottom of its inter-earnings range. Price and AVWAP trend readings remain negative, although sequential growth readings have turned positive.
The bottom line is that ARCC delivered a quarter in which underlying earnings power kept eroding, with core EPS below the dividend, slower originations and decelerating borrower growth. At the same time, management laid out a credible path to reverse that slide. The Q4 pipeline, wider spreads, lower funding costs and an accretive acquisition priced below MFIC's NAV give bulls a reasonable argument. Bears still have legitimate ammunition until core earnings re-cover the $0.48 payout without leaning on spillover.
Read our earnings preview for Ares Capital Corporation: https://www.earningswhispers.com/article/ARCC/20678
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-09 | |
| Oct-02 | |
| Sep-15 | |
| Sep-08 | |
| Aug-31 | |
| Aug-12 | |
| Jul-31 |
