Five Star Bancorp Beats As Margin Re-Expands, But Dilution And Stalled Deposits Cap The Per-Share Payoff
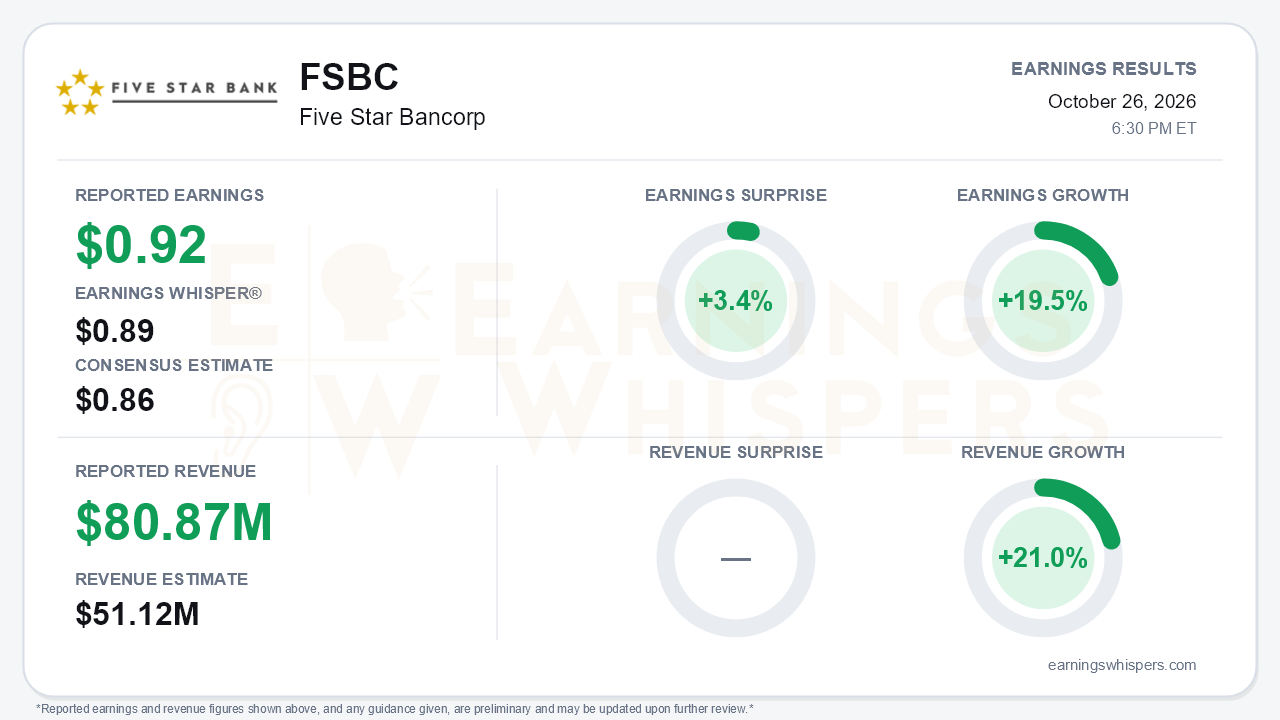
Five Star Bancorp (NASDAQ: FSBC) earned $0.92 per share in the third quarter, ahead of the $0.86 consensus and the $0.89 Earnings Whisper number, a 3.4% beat. Earnings grew 19.5% year over year, and revenue of $80.87 million rose 21.0%. The headline understates the operating improvement and overstates the per-share progress at the same time. Net income rose 34% from a year ago and nearly 13% sequentially to $21.9 million. EPS, however, rose just a penny from the second quarter's $0.91 because the July equity offering added about 11% to the weighted share count. That is the central tension: the business is earning materially more, but shareholders are sharing it across a larger base.
The revenue surprise needs context. The reported $80.87 million matches gross interest and fee income plus non-interest income. The $51.12 million consensus appears to be built on a net revenue basis, so the 58.2% surprise mostly reflects a difference in definitions rather than a blowout. On a net basis the quarter was still solid. Net interest income rose 10.5% sequentially and 29.4% year over year to $50.9 million. Net interest margin widened six basis points to 3.69%, reversing second-quarter compression, as loan yields rose to 6.14%. The efficiency ratio improved to 39.13% from 40.91%, and pre-tax, pre-provision income climbed 13% to $32.0 million. Fee income slipped to $1.7 million, and even that total included a special FHLB dividend.
The roughly $130 million raise is the quarter's most important structural change. CET1 jumped to 12.52% from 9.97%, and book value per share rose 14% to $25.15. That removes the concern raised on the year-end call that growth above 10% would eventually require a capital event. The cost showed up right away: ROAE fell to 15.04% from 16.67%. Management is now deploying that capital into a slowing balance sheet. Loan growth moderated to about 16% annualized from roughly 29% in the second quarter. Management cited slower real estate acquisition financing, and analysts flagged record payoffs. Deposits grew only $25.1 million, against $330 million in the second quarter and $268 million in the first. The company attributed part of the slowdown to seasonal outflows from government deposits. As a result, the loan-to-deposit ratio rose to 97.5% from 94.2%.
Funding is the risk bears will focus on. The average cost of deposits has risen for two straight quarters, to 2.19% from 2.13% in the first quarter. Management said new relationships are being priced in the "high twos," and the bank's asset-liability profile is liability-sensitive if rates move higher. The call also delivered genuine positives. September's margin ran six to seven basis points above the quarterly average as assets repriced faster than deposits. A repricing runway remains: $135 million of loans at 4.27% reprice in the fourth quarter and $694 million at 5.00% in 2027, while new production is coming on at 6.53%. Management issued its first explicit 2027 loan growth target of 10-12% and tightened its expense guide to 1.45-1.50% of average assets. Expansion continued with a Lodi branch, a Calabasas office, four Palo Alto bankers and five more business development officers. One detail argues against simple margin euphoria: the margin comfort range is now 3.65-3.75%, a lower floor than the 3.70-3.75% range given in the first quarter. Credit looks stable. Nonperforming loans edged down to 0.28%, with most of the balance tied to a single well-secured $11.4 million credit, although watch-rated loans have grown since year-end.
Investors did not enter the report enthusiastic. Earnings Whispers sentiment fell to -0.39 from -0.17 at the prior report, a meaningful move further into negative territory. The decline likely reflects dilution and the funding slowdown more than the core earnings trend. The stock has gone nowhere since the last report: at $44.50, shares are down 0.7% from the $44.82 open after July's release. They sit about 4.5% above the $42.60 200-day moving average, so the longer-term trend remains intact even as the stock has stalled. Earnings Whispers sequential growth and momentum readings are positive, while AVWAP remains negative, consistent with a stock that has absorbed new supply without breaking down.
The bottom line is that Five Star delivered a clean beat with real operating leverage: margin, net interest income, efficiency and capital all improved. The equity raise, however, converted strong net income growth into modest per-share progress and lower returns on equity. Meanwhile, deposit gathering stalled just as loan demand cooled and funding costs crept higher. The 2027 growth guide and repricing tailwinds keep the earnings story credible. The next test is whether the bank can fund 10-12% loan growth without giving back the margin gains, and skeptical sentiment suggests investors want proof before rewarding it.
Read our earnings preview for Five Star Bancorp: https://www.earningswhispers.com/article/FSBC/20652
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-16 | |
| Oct-13 | |
| Sep-30 | |
| Sep-14 | |
| Aug-03 | |
| Jul-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-17 | |
| Jul-15 | |
| Jul-09 |
