Zimmer Biomet's Sales-Force Overhaul Faces Its First Post-Raise Test As Margins Linger
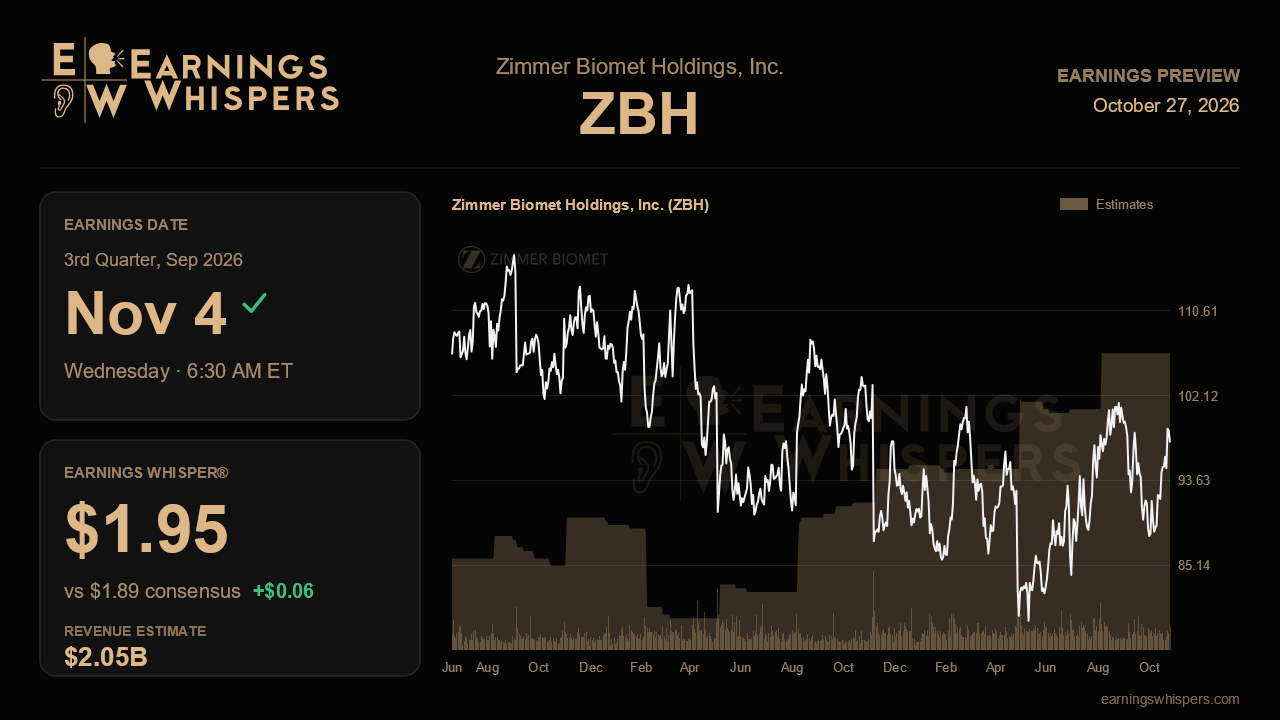
Three months ago Zimmer Biomet finally gave investors the beat-and-raise they had been waiting for, lifting its revenue outlook, earnings guidance and buyback in one stroke after several quarters of cautious reaffirmations. The market has not taken the bait. Shares are down 3.5% since that report, trailing a 1.4% slip in the S&P 500, and sentiment has turned noticeably more bearish. That leaves the third-quarter report, due before the open on November 4, with a specific job: proving that the improved tone was the start of a trend and not a one-quarter reprieve.
The bar itself is modest. Analysts expect earnings of $1.89 per share, essentially flat against the $1.90 earned a year ago, on revenue of $2.05 billion, up 2.4%. The Earnings Whisper of $1.95 sits about three percent above consensus, a sign that more optimistic investors expect another clean beat. Full-year forecasts of $8.54 per share and $8.59 billion in revenue land almost exactly at the midpoint of management's reaffirmed ranges of $8.47 to $8.59 and $8.55 billion to $8.63 billion. The Street, in other words, has accepted the raised outlook but is not pricing in another lift. A top-line beat that pushes management toward the upper end of its ranges would matter more than a few cents on the bottom line.
The flat earnings forecast against rising sales captures the central trade-off. Zimmer is spending heavily to rebuild its US sales organization, and that investment drove a 210 basis point decline in second-quarter adjusted operating margin. Management now expects full-year operating margin to fall a little more than 50 basis points, so the back half needs to show the pressure easing rather than deepening. If margins compress again on a similar scale while sales growth merely holds steady, the argument that the commercial overhaul pays for itself will look stretched.
On the revenue side, the evidence to watch is whether US momentum is broadening. US organic growth of 4.6% last quarter rested on hips, which have now re-accelerated for several straight quarters, and on technology, where US sales jumped more than 50% on record robot placements. Robot capital sales are lumpy, so a cooling in that growth rate is not alarming by itself, but placements should eventually pull through implant volumes. Knees are where that thesis gets tested. Global knee sales were flat last quarter, with US growth of just 1.4% and international declines tied partly to a roughly 20% drop in China. A visible pickup in US knees would be the clearest sign that the new sales force and ROSA installations are translating into share. Continued stagnation would suggest the hip strength is doing most of the work.
Newer catalysts deserve a progress check as well. The iodine-coated hip in Japan was supply constrained and commanding a hefty price premium, and the next-generation ROSA Shoulder moved to full release. Updates on supply relief for the hip, early shoulder adoption, and the expected Monogram regulatory filing ahead of a planned 2027 launch would show whether the pipeline is advancing on schedule. In the surgical and trauma segment, Paragon 28's mid-teens growth needs to keep offsetting persistent softness in trauma and restorative therapies.
Technically, the stock sits above its 200-day moving average near $91.53 and in the upper half of its post-earnings range, roughly 5% below the $102.86 high, so it is not yet pressing a breakout. The real question for November 4 is whether US execution can lift knees and stabilize margins at the same time. If it can, the doubts that have built since the last raise look misplaced. If growth stays concentrated in hips and robots while margins keep sliding, investors will likely keep treating the turnaround as unproven.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-21 | |
| Oct-21 |
Healthcare Stocks Are Rallying, and Flashing a Warning for the Rest of the Market
ZBH
The Wall Street Journal
|
| Oct-13 | |
| Oct-12 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 |
