Allient's Record Backlog Faces A Conversion Test As Shares Slide After Last Quarter
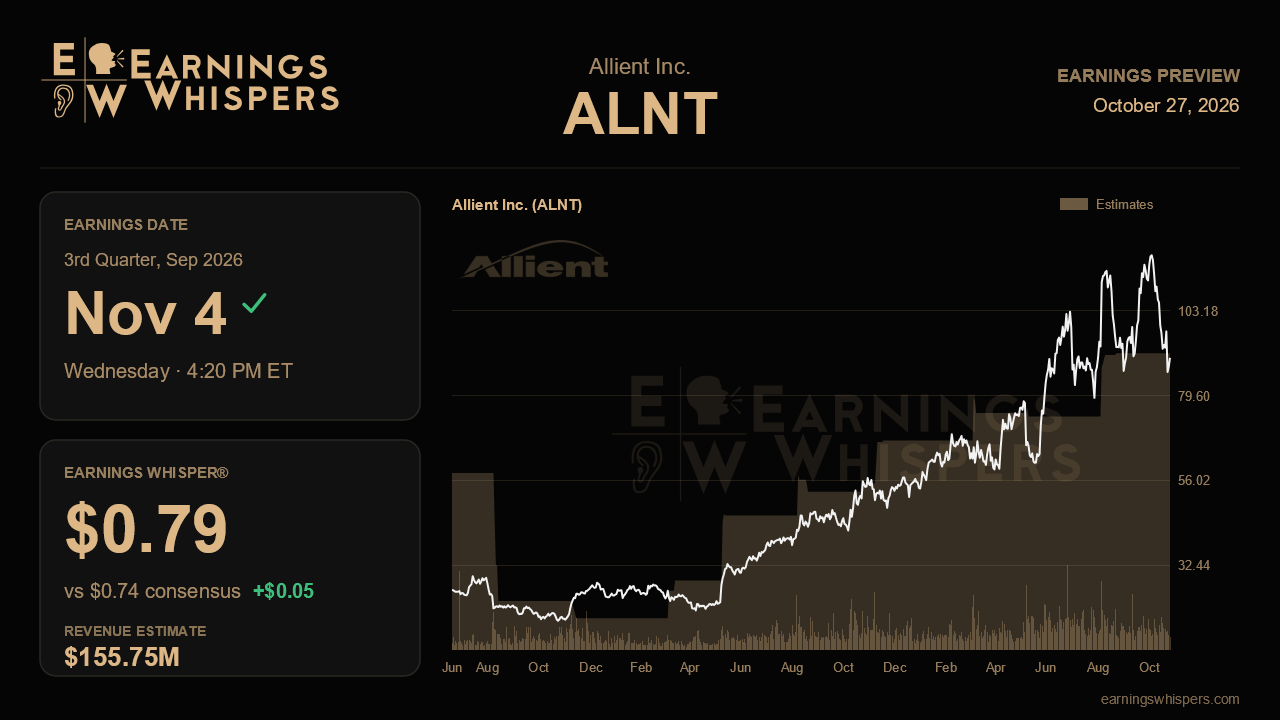
Allient enters its fiscal third-quarter report with a gap between what its order book says and what its share price says. Last quarter the motion control and power quality specialist posted record bookings of $201.3 million, a 1.31 book-to-bill ratio and a backlog that swelled to $298 million. The stock has since fallen 12.7%, trailing the S&P 500 by about 12 percentage points. The report due after the close on November 4 is the first chance to show that the demand surge is turning into shipments and profits rather than simply piling up on paper.
The Street expects earnings of $0.74 a share on revenue of $155.8 million. That would be EPS growth of about 25% and revenue growth of roughly 12% from a year ago, a solid result for an industrial component maker. On a sequential basis the picture is more cautious. Revenue is forecast to edge up only slightly from last quarter's $153.8 million, while EPS is expected to fall from the $0.80 adjusted figure Allient just delivered. That dip suggests analysts took management's warning about mix-driven margin swings seriously. The Earnings Whisper of $0.79 sits above consensus and roughly matches last quarter's result, so the informal bar is that Allient can hold its new earnings level rather than slip back. No formal guidance is available to check those numbers against.
The most telling figure may be revenue relative to backlog. A company that booked about $47 million more than it shipped last quarter should be able to grow sales faster than the low single digits sequential consensus implies, unless lead times are long or capacity is the constraint. That leads to data center and infrastructure power quality, which management broke out for the first time at $16.3 million in quarterly sales, up 60%. Management said this business should keep outgrowing the company, with added capacity arriving late in the third quarter or early in the fourth. Steady growth in that line, plus confirmation that the expansion is on schedule, would support the idea that Allient is becoming partly a data center infrastructure story. A flat result or a slipped timeline would weaken that idea.
Margins are the second test. Gross margin hit a record last quarter on mix and better absorption, and adjusted EBITDA jumped to 15.4% of sales from 12.4%. Holding most of that gain would show the improvement is structural, helped by ongoing cost takeout. A sharp reversal would suggest last quarter benefited from unusually favorable mix. Aerospace and defense, which swung to 16% growth after several weak quarters, needs to show that conversion of quotes into orders is lasting. Investors should also listen for early reaction to the drone and unmanned propulsion launch at AUSA in October. Vehicle, down 7% on soft power sports demand, is the obvious soft spot, and the question is whether it stabilizes or keeps falling. Cash flow, inventory and the unfinished Dothan transition are housekeeping items, but they matter more now that capital spending guidance has risen for a second straight time to $12 million to $15 million.
Sentiment has drifted slightly more bearish than before the last report, though both readings are close to neutral. The more meaningful signal is the price. At $90.11 the stock sits near the bottom of its post-earnings range of $83.73 to $121.42, though still above its 200-day moving average of $81.78. That position points to a market that has given back much of last quarter's enthusiasm without abandoning the longer-term uptrend.
The main question is whether last quarter's step change was the start of a durable upturn or a single strong quarter. If Allient shows backlog converting into revenue, data center sales still climbing, capacity arriving on time and margins mostly intact, the recent selloff will look premature. If orders cool sharply or margins fall back toward earlier levels, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Sep-05 | |
| Aug-21 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| May-11 | |
| May-06 | |
| May-06 | |
| May-06 | |
| Apr-30 | |
| Mar-10 | |
| Mar-10 |
