Amcor Must Prove Its Volume Turn And Cash Recovery Are Real After Breakout Quarter
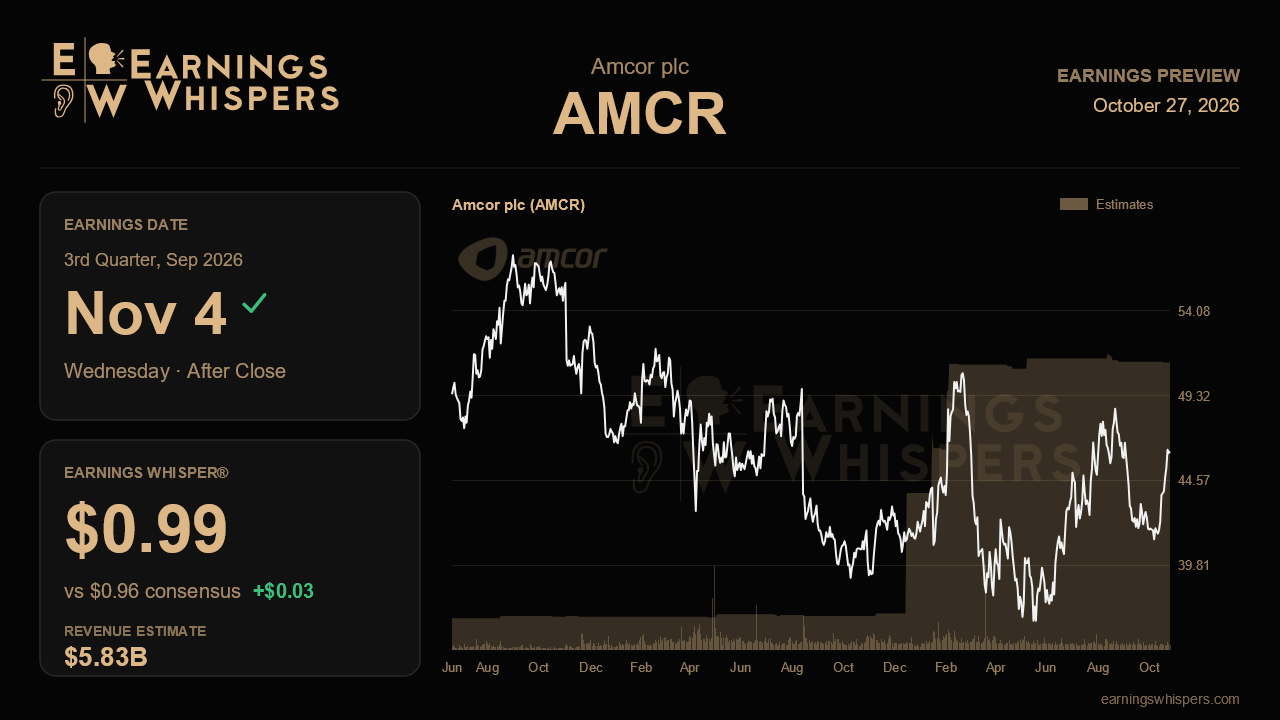
Amcor heads into its September-quarter report with a story that finally looks like it is working, and a stock that has not fully believed it. Last quarter brought the first positive volume print in a year, synergies ahead of plan and a fresh promise of double-digit earnings growth in calendar 2027. Yet the shares have slipped 3.8% since that report, trailing a 1.2% decline in the S&P 500. The upcoming release, due after the close on November 4, is the first real check on whether the inflection was a turning point or a single good quarter.
The Street is looking for adjusted earnings of $0.96 a share on revenue of about $5.83 billion. The headline year-over-year EPS growth figure of roughly 405% is not a useful gauge, since the year-ago comparison of $0.19 reflects a very different, deal-distorted base. Revenue growth of about 1.5% is the more honest signal: modest, and consistent with a business that has shed five non-core operations while integrating Berry. The sequential step down from $1.23 and $6.40 billion largely reflects seasonality and those divestitures rather than deterioration. The earnings whisper sits a touch higher at $0.99, a small premium suggesting some appetite for an upside surprise but not an aggressive bar.
The more interesting comparison is with management's guide of $1.80 to $1.90 for the six-month transition period ending in December. Consensus of $0.96 for the first half of that window is slightly above an even split of the midpoint, implying the Street expects a solid start or a softer December quarter. That guide already absorbs a $0.10 to $0.12 drag from higher interest and taxes, so a clean beat here would need to come from operations, not below-the-line help.
Volumes are the first test. Flexibles rose about 1% and rigid packaging about 0.5% in the June quarter, a roughly 200 basis point swing after three straight quarters of declines, and the CFO said July held that pace. A September quarter that stays positive across regions would validate the turn; a slide back toward flat or negative would suggest the improvement was more comparison than demand. Healthcare deserves a look too, since softer lower-margin subcategories were masked by richer pharma mix. Synergies are the second pillar. Amcor delivered $285 million in its first year, about 10% ahead of plan, and growth synergy wins climbed every quarter to roughly $140 million, half the three-year target. Continued progress there, alongside margins holding near the improved levels seen last quarter despite ongoing input cost pass-through, would support the 2027 framework.
Cash is the soft spot. Free cash flow of $1.3 billion for fiscal 2026 missed a range that had already been cut once, with Middle East disruption tying up about $500 million in working capital, mostly receivables. Management called this timing and targeted more than $500 million of recovery over twelve months. Early evidence of receivables unwinding would go a long way toward restoring credibility on cash and the path to roughly 3x leverage.
Sentiment has warmed noticeably, with bullish readings rising to about 48% from 27% ahead of last quarter, and the stock trades comfortably above its 200-day average near $42.93, though about 6% below its post-earnings high of $48.94. The bar is higher than it was, but not lofty. The verdict will hinge on whether positive volumes persist and working capital starts flowing back; deliver both, and the double-digit 2027 story gains real footing.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-23 | |
| Sep-18 | |
| Aug-25 | |
| Aug-18 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 |
