Dutch Bros Must Show Its Comp Slowdown Is Just Pricing Math After A 25% Slide
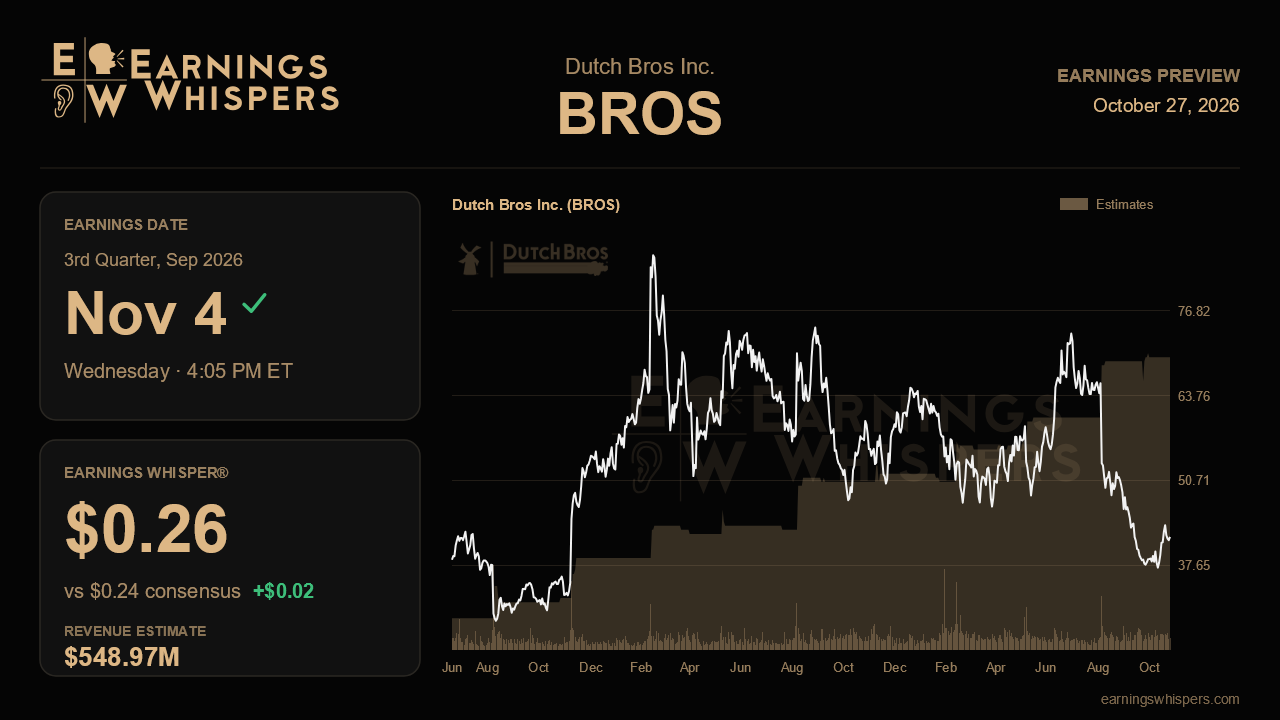
Dutch Bros heads into its third-quarter report with an odd disconnect. Management has raised its full-year outlook three times in a row, margin pressure has shrunk every quarter, and executives sounded more confident than ever on the last call. Yet the stock has dropped about 25.6% since that report, while the S&P 500 was roughly flat. The quarter ahead is the one management flagged as the softest-looking stretch of the year. So the question is simple: will the expected slowdown in same-shop sales prove to be the pricing math the company described, or the first sign of a cooling customer?
The Street expects adjusted earnings of $0.24 per share on revenue of $549.0 million. That revenue figure would be about 29.6% above the year-ago $423.6 million, which is strong growth helped in part by the newly acquired Phoenix shops. It would also be essentially flat with the second quarter's $550.9 million, so a modest top-line beat seems achievable. EPS would rise sharply from $0.15 a year ago, but it would come in below last quarter's $0.33. The Earnings Whisper of $0.26 sits a couple of cents above consensus, suggesting the informal bar is a bit higher than the published one. Full-year consensus revenue of $2.08 billion actually sits below management's raised $2.10 billion to $2.13 billion range. Either analysts have not fully updated their models, or they doubt the back half. A quarter that keeps the company on pace for its range would close that gap in management's favor.
The central operating issue is same-shop sales. After an 8.3% company-operated comp in the second quarter, guidance implies system comps of only 4% to 5% in the third. Management tied that slowdown mostly to a point of price rolling off in July, leaving less than one point of effective pricing for the rest of the year, and to lapping the food launch. That explanation only holds if traffic stays healthy. Company-operated transaction growth already slowed to 3.4% from 6.9%, and system transactions grew just 1.7%. A ninth straight quarter of positive traffic, ideally steadier than last quarter, would support the pricing story. Traffic that stalls or turns negative, especially with analysts pointing to Starbucks moving into blended energy drinks, would point to a demand problem.
Several newer catalysts should also start showing up in the numbers. Food began rolling out to franchise shops this quarter, so any narrowing of the widening gap between company and franchise comps would be an early sign it works beyond the company-run fleet. MIST energy drinks, now a permanent menu item, should keep pushing energy beverages higher as a share of sales. Phoenix should add to revenue and EBITDA, putting it on track for the roughly $25 million and $5 million management expects over the second half. Development matters too. After a record 48 openings, steady new-shop growth would back up the claim that about 90% of the pipeline for 2,029 shops in 2029 is already secured.
On margins, management guided to only about 20 basis points of full-year EBITDA margin pressure, despite roughly 60 basis points of coffee cost pressure and about 50 basis points from higher occupancy costs. Holding company-operated contribution margins near last quarter's roughly 31%, with SG&A leverage on track for about 90 basis points, would show that $385 million to $390 million in EBITDA is still realistic.
Sentiment has edged from slightly bearish to modestly bullish, but the chart tells a gloomier story. At $42.02, the stock sits well below its 200-day moving average of $53.79 and much closer to its post-earnings low of $36.51 than its high of $56.46. That lowers the bar somewhat, but it also shows how little benefit of the doubt the market is giving. The report will be judged less on EPS than on traffic. If transactions hold up while pricing fades, the guidance story stays intact. If they slip, three straight raises may count for little.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 | |
| Sep-25 | |
| Sep-22 | |
| Sep-18 | |
| Sep-16 | |
| Sep-14 | |
| Sep-08 | |
| Sep-07 |
