Dutch Bros Misses The Whisper And Trims Guidance As Traffic Stalls, Even While It Ramps Toward 250 Openings In 2027
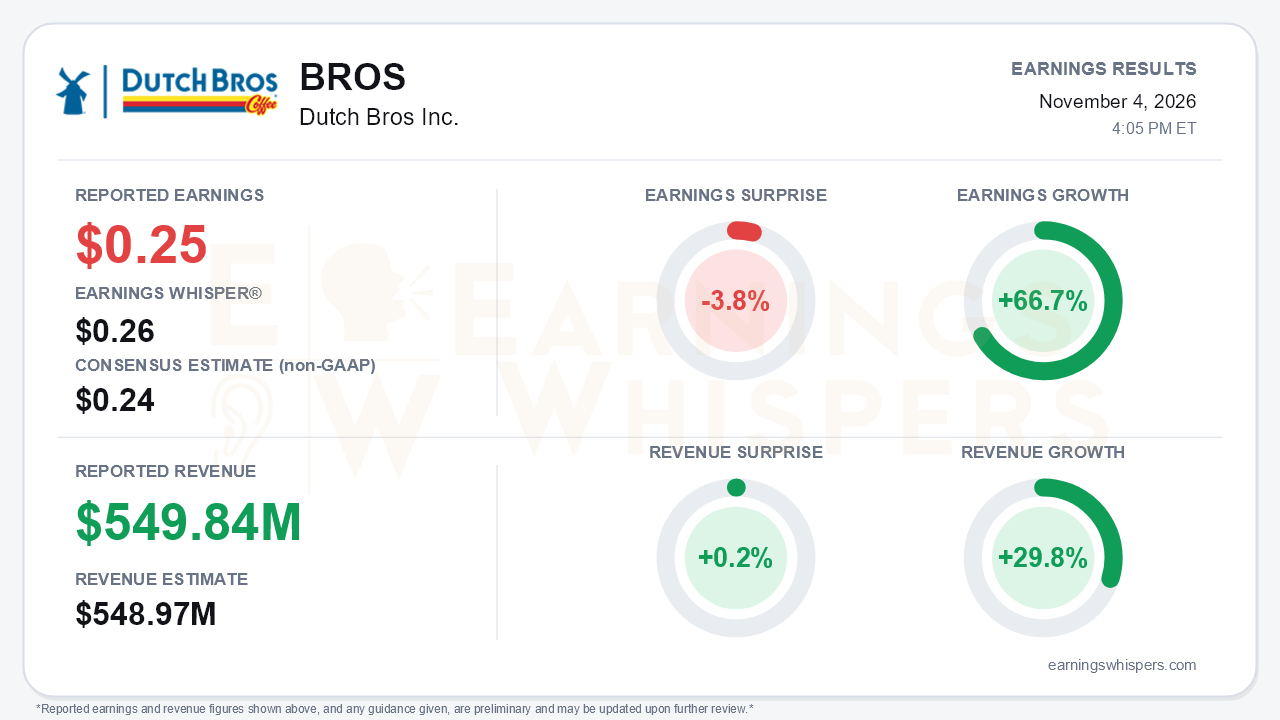
Dutch Bros reported third-quarter adjusted earnings of $0.25 per share on revenue of $549.84 million. That was a penny above the $0.24 consensus but short of the $0.26 Earnings Whisper number, a 3.8% miss against the expectation that mattered most. Revenue edged past the $548.97 million consensus by 0.2% and grew 29.8% year over year, while earnings grew 66.7%. Those growth rates look strong, but they are not the story. The central tension is that Dutch Bros is accelerating unit growth into a slowing consumer. For the first time after two straight raises, management cut its full-year outlook.
The quality of the quarter deserves scrutiny. Same-shop sales slowed for a third straight quarter:
- Systemwide comps went from 8.3% in Q1 to 5.8% in Q2 to 4.4% in Q3.
- Company-operated comps fell from 10.6% to 8.3% to 5.4%.
The mix beneath those numbers is weaker still. Systemwide customer visits rose just 0.4%, against 4.7% a year ago. Company-operated traffic grew 1.0%, against 6.8%. Ticket growth of 4.0% to 4.4% did nearly all the work. Revenue growth also got help from the Phoenix East Valley franchise reacquisition, completed in late July, which moved franchised shops onto the company-operated line.
Margins were mixed:
- Adjusted EBITDA rose 29.6% to $101.1 million, but its 18.4% margin was flat year over year.
- Company-operated shop contribution of 28.1% was slightly better than a year ago but well below roughly 31% in Q2.
- Per the call, cost of goods was flattered by about $4 million in tariff refunds.
- Occupancy and other costs jumped to 18.0% of shop revenue from 17.0%.
- Labor leverage (26.7% vs. 27.5%) and adjusted SG&A leverage (12.7% vs. 13.6%) did the offsetting.
GAAP diluted EPS rose to $0.20 from $0.14.
The call made the guidance shift explicit:
- Same-shop sales are now 'at least 5%,' versus 5% to 6% trending toward the midpoint in Q2. Management indicated the low end implies Q4 system comps of roughly 2.5%, against tougher traffic comparisons.
- Adjusted EBITDA guidance fell to about $380 million from $385 million to $390 million, though it remains above the original $370 million to $380 million range.
- Revenue is now 'at least $2.1 billion,' effectively the bottom of the prior range.
- Q4 shop margins were guided below Q3.
The tone changed too. Q2's 'confidence has never been greater' gave way to repeated references to consumer volatility and Q3 'choppiness,' which management partly tied to rising gas and utility prices.
Development is where management is pressing harder. The company opened 48 shops in the quarter, matching Q2, and reaffirmed at least 185 system openings for 2026. It introduced a preliminary 2027 goal of about 250 and claimed full real-estate visibility to 2,029 shops by 2029. New shops are annualizing around $2 million, above the $1.8 million underwriting level. Supporting the plan:
- Capex guidance rose again, to $370 million to $390 million.
- Order Ahead reached about 17% of visits and Dutch Rewards about 74%.
- Energy drinks rose to 27% of mix.
- New levers include a DoorDash delivery pilot, a matcha relaunch in 2027, and hot food tests.
Bears have legitimate ammunition here as well. Management flagged:
- Elevated cannibalization in 2027 as openings concentrate in existing states.
- New-shop volumes normalizing toward underwriting.
- Occupancy pressure of about 100 basis points continuing into next year.
- Coffee costs that will flow through with a two- to three-quarter lag, with possible further price increases.
With ticket already carrying comps, more pricing raises the traffic risk. The balance sheet is absorbing the buildout. Cash fell to $194.6 million from $269.4 million at year-end, and management put liquidity at about $625 million, down from about $699 million after the Phoenix buyout.
The market had largely priced in a softer quarter. Shares peaked at $56.46 on the open after the August report and fell to a 52-week low of $36.51 on October 12. Entering the report, they traded at $43.58, down 22.8% from that post-report open and about 18% below the $53.23 200-day moving average. The stock had rebounded roughly 19% off its low. Investor sentiment improved only marginally, from slightly negative to neutral, which is consistent with a cautious rather than euphoric setup. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative, reflecting a business still growing quickly inside a stock that has been under pressure.
The bottom line is that Dutch Bros delivered roughly 30% top-line growth and a credible expansion story, but the earnings miss versus the whisper, decelerating traffic, and the first guidance cut of the year undercut it. The 250-shop 2027 plan shows management doubling down on unit growth just as same-shop momentum, margins, and the consumer backdrop are softening. Whether new-shop productivity holds up against rising cannibalization is now the key question for the stock.
Read our earnings preview for Dutch Bros Inc.: https://www.earningswhispers.com/article/BROS/21794
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| Nov-02 | |
| Nov-01 | |
| Oct-30 | |
| Oct-27 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 |
