Avino Must Prove Its Cost Overruns Were Temporary As Shares Sink Toward Lows
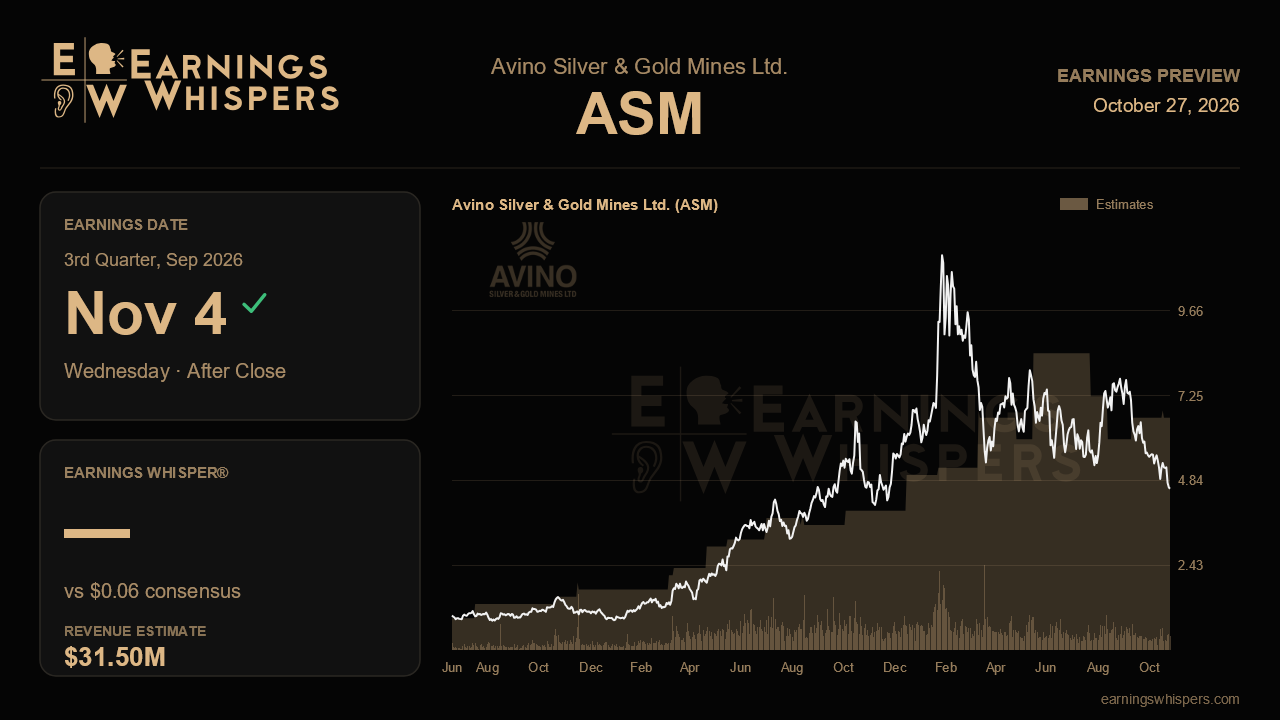
Avino Silver & Gold Mines heads into its third-quarter report with an awkward split between its operations and its share price. Last quarter, management argued that a sharp sequential drop in revenue, margins and free cash flow came mostly from silver prices, a stronger peso and timing quirks, not from anything wrong at the mines. The market has not bought that story. The shares have fallen about 38% since the last report while the S&P 500 barely moved, and at $4.60 they sit just above the post-earnings low of $4.51 and far below the 200-day moving average near $6.91. This report is about showing that the second-quarter stumble really was temporary.
The Street expects earnings of $0.06 a share on revenue of about $31.5 million. That would be roughly 50% revenue growth from a year ago, yet earnings are expected to slip about 14% from $0.07. The gap between those two figures tells the story. Analysts see a much bigger top line but are not yet trusting Avino to turn it into more profit. Sequentially, the forecast implies a solid revenue rebound from $26.8 million with flat earnings, which suggests consensus has built in continued cost pressure. The company did not issue fresh guidance after the last report. Management did say it broadly stood by its 2026 targets, so the cost line is where that claim will be tested.
Costs are the biggest swing factor. In the second quarter, cash cost per ton of about $74.72 and all-in cost of roughly $96 per ton both ran above the guided range. Management blamed a heavier mix of La Preciosa development material and mining of lower-grade oxidized surface areas. It said costs should normalize as grades improve and production mining begins. The key evidence will be whether Level 3 development at Abundancia and Gloria, which was nearly finished last quarter, has started delivering higher-grade long-hole ore. A move back toward the guided cost range would support management's account. Another quarter above it would suggest the overruns are structural, not a passing feature of the ramp.
The revenue line also has some timing effects that should unwind. A $5 million provisional pricing adjustment hit the prior quarter, and higher concentrate inventory at quarter end pushed some sales into later periods. If those concentrates were sold, third-quarter revenue should get a mechanical lift, which may explain part of the consensus rebound. Investors should separate that catch-up from underlying production. Equivalent silver output eased to 535,000 ounces from 568,000, so a return toward or above Q1 levels would be reassuring. The peso, which strengthened 12% to 15% last quarter, remains an outside risk to margins that management cannot control.
La Preciosa is the longer-term story, and its tone shifted slightly last quarter. Development output there rose 59% sequentially to about 100,000 equivalent ounces, and both mill circuits began taking its ore three months early. Management also stopped committing to a firm date for the 500-ton-per-day target, pending optimization work and a trade-off study on a standalone plant. Any update on that study, or a clearer timeline, would carry real weight. The record $145 million cash balance and the ongoing buyback give Avino room to wait, but they do not replace a clear plan.
Sentiment has cooled, with bullish readings down to about 14% from nearly 24% before the last report, and the stock's collapse shows how much skepticism is now priced in. That lowers the bar somewhat, but it does not remove it. The central question is simple: does Avino's growing production base finally convert into margin expansion? If costs fall back toward guidance as grades improve, the second quarter will look like a pause. If they do not, the market's harsher reading will gain support.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-26 | |
| Oct-15 | |
| Sep-09 | |
| Aug-12 | |
| Aug-12 | |
| Jul-22 | |
| Jun-08 | |
| May-27 | |
| May-14 | |
| May-13 | |
| May-04 | |
| Apr-23 | |
| Apr-23 | |
| Apr-20 |
