Chord Energy's First 75% Payout Quarter Puts Its Free Cash Flow Streak To The Test
Chord Energy heads into its third-quarter report with a promise to keep. Three months ago management lifted its return-of-capital floor to at least 75% of free cash flow starting this quarter, a sharp step up from payouts of roughly 50% to 69% in recent periods. The results due after the close on November 4 will be the first under that framework. They will show whether the cash engine that has beaten expectations for four straight quarters can carry a bigger shareholder commitment while costs drift higher and a pricing tailwind fades.
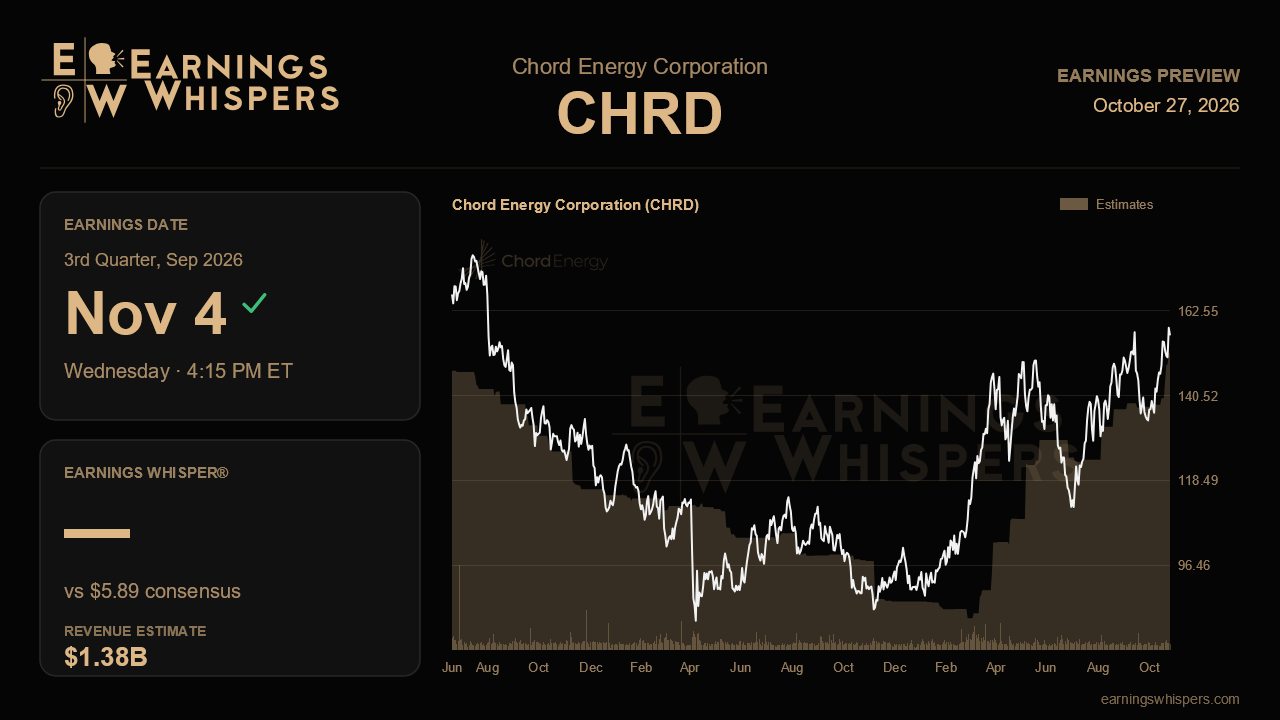
The Street is looking for earnings of $5.89 a share on revenue of about $1.38 billion. That would be a 150.6% jump from the $2.35 earned a year ago, against revenue growth of just 5.2%. The gap between those two growth rates is the story. Chord is not being asked to grow its top line much. It is being asked to convert a roughly flat, maintenance-plus production base into far more profit per barrel. Consensus also sits below the $6.44 the company posted last quarter, and revenue expectations fall well short of the prior period's $2.17 billion. Analysts are already building in a softer sequential print, so the bar is not set at perfection.
The prior call offers a clear map of what matters. Management raised its full-year oil volume target to 161,000 barrels a day, about 2,000 barrels above the original framework. It credited short-cycle work on existing wells rather than a bigger drilling budget, which held near $1.4 billion. Third-quarter volumes tracking at or above that pace would confirm the gains are durable rather than a one-time lift. The price of those barrels is the counterweight. Lease operating expense guidance rose to $10.30 per barrel of oil equivalent, driven by expanded chemical treatments, costlier workovers and higher non-operated costs. Management framed that spending as a high-return investment. This quarter should start to show the payoff in production. If unit costs keep climbing without a matching volume response, the efficiency narrative weakens.
Realizations are the other swing factor. Chord's Bakken crude has recently sold near parity with, or at a modest premium to, West Texas Intermediate. Management warned that this advantage would erode over the rest of 2026. A faster-than-expected fade would pressure revenue just as the company commits a larger share of cash to buybacks and dividends. Longer term, the call highlighted 26 four-mile wells drilled to date and the basin's first trimul frac. Management suggested that technique could cover 20% to 50% of the 2027 program. Early commentary on 2027 capital efficiency could matter as much as the quarter itself.
The market has already rewarded the story. Shares have climbed 19.3% since the last report while the S&P 500 slipped 0.6%. At $156.15 the stock sits about 20% above its 200-day moving average and within roughly 2.5% of its post-earnings high of $159.96, close enough to be testing a breakout. Sentiment has nonetheless edged more bearish, at 15.0% negative versus 11.7% a quarter ago. That mix suggests a stock that has run ahead of some investors' conviction. Clean confirmation could push it through resistance, but a stumble would meet little cushion.
The central question is whether Chord's free cash flow comfortably covers the new 75% payout after absorbing higher operating costs and a narrowing crude premium. Steady volumes, contained unit costs and a buyback pace that matches the pledge would keep the narrative of self-funded, incremental improvement intact. A cash shortfall that forces management to lean on its $612 million balance sheet to meet the payout floor would raise doubts the recent rally has not priced in.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-13 | |
| Oct-02 | |
| Sep-16 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| May-28 | |
| May-07 |
Frackers Are Finally Ready to Drill. Trump Won't See a Return of the Go-Go Days.
CHRD
The Wall Street Journal
|
| May-05 | |
| Apr-21 |
