Clover Health's Q3 Test: Can Cost Trends Hold As Guidance Implies A Second-Half Slowdown?
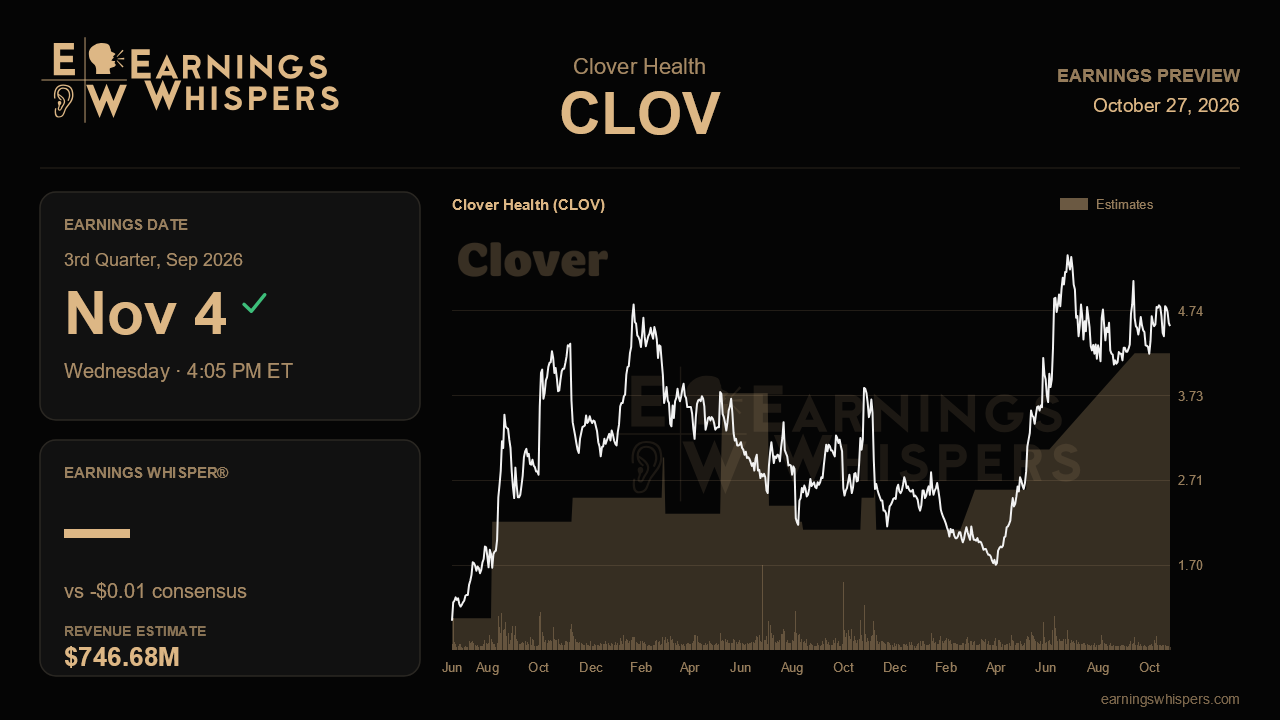
Clover Health enters its third-quarter report with an unusual puzzle. The Medicare Advantage insurer has already earned more than its full-year profit targets would seem to require, yet Wall Street expects a small loss. That gap reflects the shape of management's own outlook rather than skepticism about the turnaround, and the report on November 4 should show whether the second-half step down is the planned, seasonal kind or an early sign that the cost improvements behind this year's rally are fading.
Analysts are looking for a loss of about a penny per share on revenue of roughly $746.7 million. That would be about 50% revenue growth from the $496.7 million posted a year ago and close to the $743.2 million reported last quarter, when Clover earned $0.06 per share. The year-ago quarter was a $0.05 loss, so a penny loss would still show progress, but it would also mark a sharp sequential retreat. Management's math explains why. After raising every major 2026 target last quarter, the company guides to adjusted EBITDA of $70 million to $85 million and GAAP net income of $20 million to $35 million. With $81 million of adjusted EBITDA and $55 million of net income already booked in the first half, those ranges imply roughly breakeven EBITDA and a net loss for the back half, driven by a typical fourth-quarter seasonal loss and heavier spending around the annual enrollment period.
Revenue is where the expectations look conservative. Full-year guidance now sits at $2.92 billion to $3.00 billion, up from $2.81 billion to $2.92 billion, yet the consensus of $2.91 billion sits slightly below the bottom of that range. With average membership guidance lifted to 156,000 to 158,000 and enrollment up 48% year over year last quarter, a third-quarter top line that clears the Street would be the easiest way to validate the raise. Revenue that merely matches consensus would suggest analysts were right to discount management's range.
The more important evidence sits below the top line. Last quarter's confidence rested on cohort maturation, with the 2025 class of members showing the roughly $70 per member per month gross profit improvement management expects in a second year, alongside favorable inpatient, dental and Part D trends. Outpatient utilization remains the swing factor. Management said it peaked in March and moderated in the second quarter but stayed elevated versus prior years. If medical costs keep behaving, the company has room to beat a modest bar. A renewed uptick, or unfavorable prior-period development like the modest hit seen in the first quarter, would challenge the narrative that last year's stumble was the trough. Continued SG&A leverage, which improved to 15% of revenue, would also help offset enrollment-season spending.
The market has not paid up for the improvement. Shares have slipped 6.8% since the last report, trailing the S&P 500 by about six percentage points, and at $4.56 the stock sits mid-range between its post-earnings low of $4.04 and high of $5.21, though comfortably above its 200-day average of $3.50. Sentiment is moderately bullish, a sign that optimism exists but is tempered, likely in part by CMS's intent to appeal the court ruling that lifted Clover to a 4.5-star rating for payment year 2027. Any update on that appeal could matter as much as the quarter itself, since the higher rating underpins management's growing confidence about next year.
Ultimately, the quarter will be judged on whether the expected profit dip is purely seasonal and investment-driven. If cost trends stay contained, revenue tracks toward the upper part of guidance and the balance sheet, which held $443 million of cash with no debt at midyear, keeps funding growth internally, the turnaround story stays intact heading into 2027. If medical costs are what erodes earnings, the stock's recent hesitation will look prescient.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-19 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-24 | |
| Sep-24 | |
| Sep-15 | |
| Aug-31 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 |
