Cirrus Logic Must Prove Its Smartphone Strength Can Outrun A Stalled PC Story
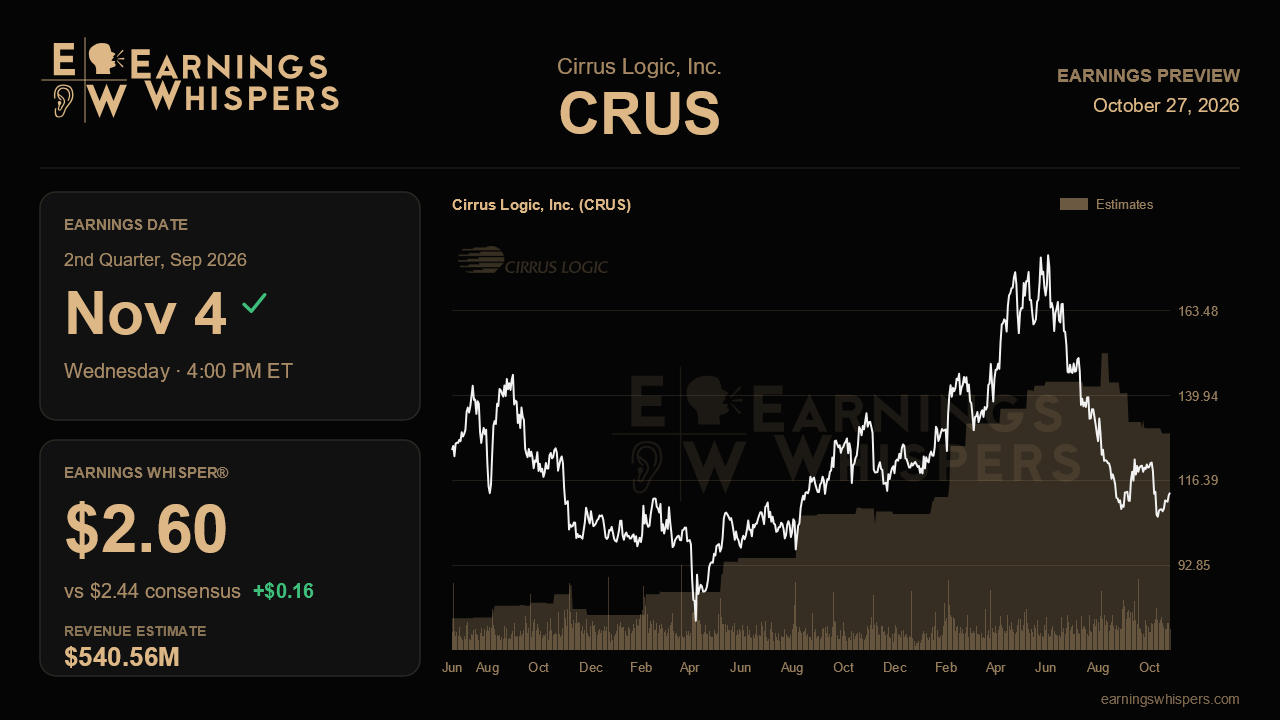
Cirrus Logic heads into its fiscal second-quarter report with a split personality. Its core smartphone audio and mixed-signal business looks as healthy as it has in years, yet the stock has been marked down hard since management walked back its PC growth ambitions last quarter. The November 4 report, due after the close, is the first chance to see whether the bigger engine can carry the company while the smaller one sputters.
The Street is looking for non-GAAP earnings of $2.44 a share on revenue of about $540.6 million. That revenue figure sits squarely at the midpoint of management's $510 million to $570 million guidance range, and it is notably below the roughly $569 million consensus that prevailed before the guide was issued. Analysts have effectively reset to the company's own numbers rather than leaning toward the top of the range. Revenue would still be down about 3.6% from the $561 million posted a year ago, and the consensus EPS figure is slightly below last year's $2.51, so this is a quarter of mild contraction on paper. The Earnings Whisper of $2.60, however, sits meaningfully above consensus, suggesting the more engaged crowd expects Cirrus to clear the bar with some room to spare.
The heart of the bullish case is seasonality. Management argued last quarter that the traditional swing between strong and weak quarters is structurally tightening, largely because camera-related content is ramping earlier in the product cycle. Guidance implies a jump of roughly 17% from the record $460 million June quarter, a much smoother path than the steep seasonal declines of the past. Revenue at or above the midpoint would validate that thesis. Equally important will be the outlook for the December quarter: if the new pattern holds, the sequential lift into the holiday period should look less dramatic than in prior years without implying weaker demand. A guide that looks too soft could reopen the question of whether revenue was simply pulled forward.
Margins deserve a closer look than the headline number. Management guided gross margin to 52% to 54%, but that range includes a one-time benefit from favorably priced GlobalFoundries wafers that will fade, while pricing concessions to its largest customer continue. Operating expenses are also climbing with R&D hiring, and capital spending is rising for test equipment. A strong print driven by the wafer tailwind matters less than what management says about gross margin once that benefit rolls off. Free cash flow, which slumped to an 11% margin in the June quarter, should rebound seasonally; a weak recovery would be a warning sign.
The PC business is where credibility is on the line. After repeatedly promising strong growth for fiscal 2027, management cut that view, blaming constrained supply of a key platform, memory shortages, pricing pressure and OEM delays, and insisting the issue is timing rather than demand. Evidence that the NVIDIA RTX Spark wins remain on track to ship this calendar year, along with progress on low-power AI PC codecs, would support that framing. Any further walkdown would make the timing argument harder to accept. Updates on the 3D sensing power chip and the newly sampled smart-meter front end would also help show that the diversification pipeline is real.
Sentiment has drifted slightly more bearish than before last quarter's report, and the shares have fallen 7.5% versus a nearly flat S&P 500. At $113, the stock sits well below its 200-day average near $139 and in the lower half of its post-earnings range, far beneath the $125 to $180 band it occupied the prior quarter. That leaves a lowered bar. The central question is whether smartphone strength and tighter seasonality are durable enough to offset fading margin tailwinds and a delayed PC ramp; if they are, the market's skepticism may prove overdone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-06 | |
| Sep-14 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| Jul-14 | |
| May-28 |
