Dave's Raise Streak Meets A Skeptical Tape As Bigger Cash Advances Test Credit
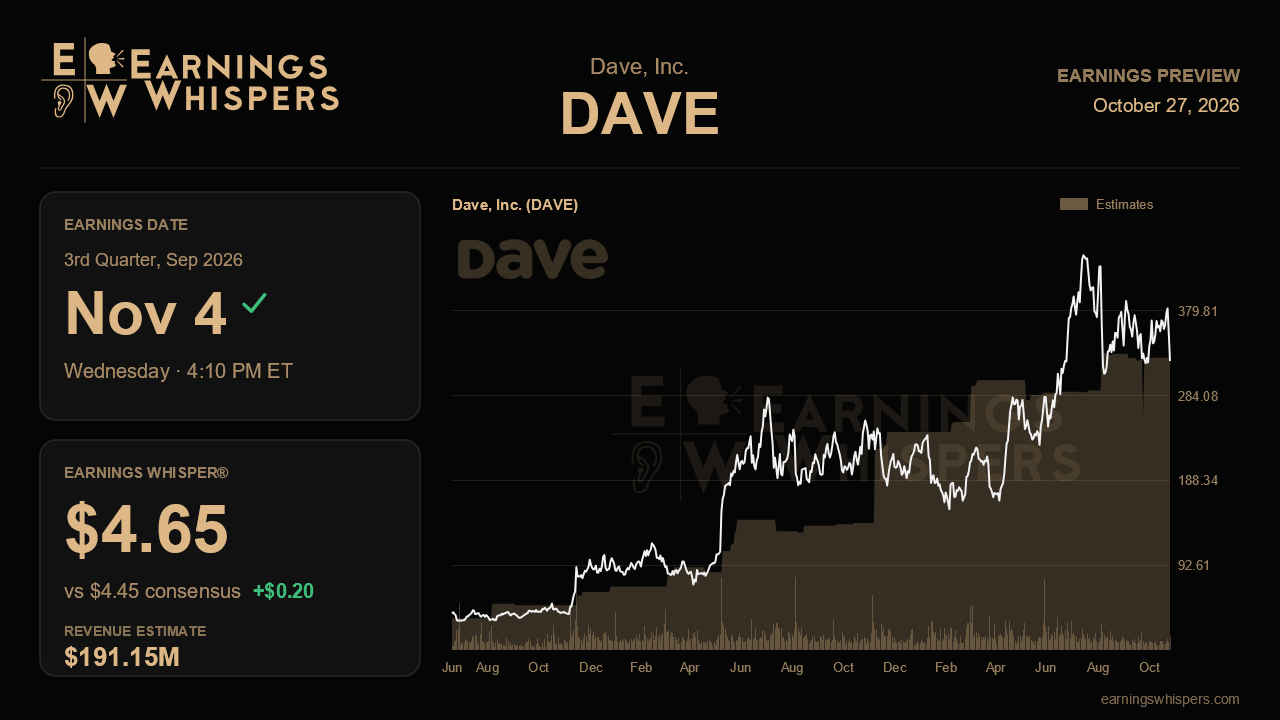
Dave has raised its full-year outlook nine quarters running, yet its shares have fallen more than 16% since the last report while the S&P 500 barely moved. That gap is the story heading into the third-quarter release after the close on November 4. The business keeps beating its own targets, but the market appears unsure how long the momentum can last as the company pushes larger advances, removes fee caps and spends more heavily on marketing. This report is the first full quarter to show whether those growth levers can work together without loosening credit discipline.
The Street expects non-GAAP earnings of $4.45 per share on revenue of $191.2 million. That revenue figure implies growth of about 27% from a year ago and roughly 12% from the second quarter's $170.8 million. The growth rate has slowed from the 60%-plus pace of late 2025 as Dave laps its fee-model overhaul, and management has said that slowdown was expected. The Earnings Whisper of $4.65 sits about 20 cents above consensus, so a matching result would probably disappoint the more optimistic holders. The year-ago comparison of $6.34 per share looks unflattering, which puts the weight on revenue, margins and guidance rather than year-over-year earnings growth.
Guidance raises the bar. Management now expects 2026 non-GAAP earnings of $17.00 to $17.50 per share on revenue of $725 million to $735 million, up from $16.25 to $16.75 and $710 million to $720 million a quarter earlier. The original targets at the start of the year were $14 to $15 and $690 million to $710 million. Published full-year consensus of $16.66 and $714.1 million still sits below the raised range. That suggests either stale estimates or doubt that the second-half plan holds. Either way, a clean beat and another raise would leave estimates room to move higher. Holding guidance flat would break a pattern investors have come to count on.
The second-quarter call sets up several operating tests. New member growth reaccelerated to 951,000, the fastest pace in about four years, while customer acquisition cost held near $19 despite a 43% sequential jump in ad spend. Sustaining that efficiency as marketing rises in the second half is the clearest proof the spending is earning its keep. Non-GAAP gross margin reached 72%, and management guided to the mid-70s for the rest of the year, so anything short of that would stand out. On monetization, the company is stacking several changes at once:
- Fee caps are being lifted for grandfathered members.
- Cash AI version 6.0 is rolling out across the base.
- Advance limits are moving above $500.
- Subscription revenue is gaining share of the mix.
These moves should support revenue per member, but they also raise the stakes on credit. In the second quarter, the provision rose 14% and 28-day delinquencies ticked up to 2.12%, which management attributed to normal post-tax-season patterns. If delinquencies drift higher while advance sizes grow, the seasonal explanation will look thin.
Two other items deserve attention. The Coastal off-balance-sheet funding structure freed up about $100 million in cash and turned receivables into a source of funds. Any update on expanding the $225 million facility would show how far that capital efficiency can stretch. Management also warned that heavier product, AI and marketing spending could limit operating leverage over the next two quarters, so modest EBITDA margin compression would not by itself signal trouble. GAAP results will remain noisy because of warrant and earn-out marks until those securities expire in January 2027.
Sentiment has swung from mildly bearish before the last report to mildly bullish now, even as the stock slid. At $323, shares trade above the 200-day moving average of about $285 but in the lower part of their post-earnings range of $302 to $399. That range is far narrower than the prior quarter's wild swings. The setup is a company with strong fundamentals priced with real caution. Whether that caution fades depends on one question: can Dave grow advance sizes and remove fee caps while keeping delinquencies near last year's levels? If credit holds, another raise looks credible. If it slips, the market's doubts will appear justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-23 | |
| Oct-02 | |
| Sep-29 | |
| Sep-15 | |
| Aug-17 | |
| Aug-07 | |
| Aug-05 | |
| Jul-30 | |
| Jul-22 | |
| Jul-07 | |
| Jun-30 | |
| Jun-09 | |
| May-28 | |
| May-27 |
