Ellington Financial Must Prove Its High-40s Earnings Run-Rate As Shares Slide Toward Lows
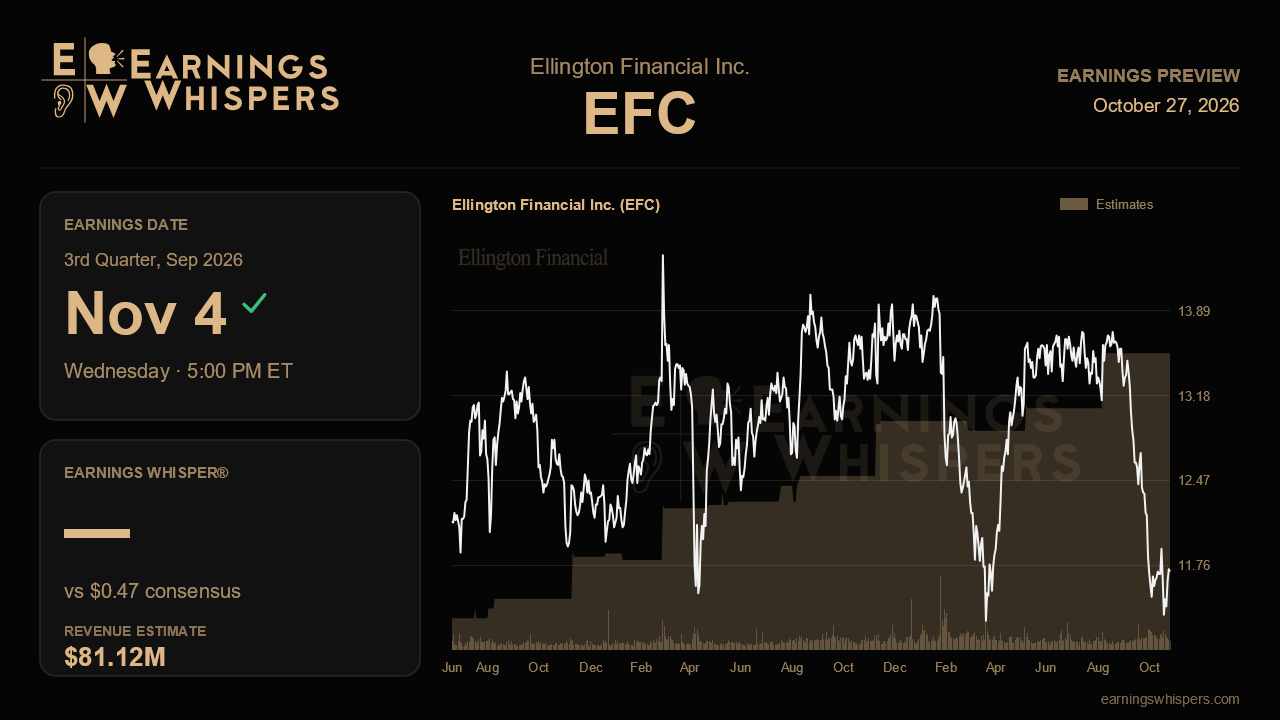
Ellington Financial heads into its third-quarter report with an odd disconnect. Management spent the last call describing a platform hitting on every front, with record adjusted distributable earnings, a raised run-rate outlook and its Longbridge reverse mortgage unit posting all-time volumes. The stock has responded by falling almost 13% since then, trailing a roughly flat S&P 500 by more than 12 percentage points. The report due after the close on November 4 is therefore less about whether Ellington can repeat a blowout quarter and more about whether the underlying earnings engine is as durable as management claims.
The Street is looking for earnings of $0.47 per share on revenue of about $81.1 million. That would be a sharp step down from the prior quarter's $0.60 and about 11% below the year-ago $0.53, while revenue is expected to drop roughly 34% from last year. On the surface that reads like contraction, but the context matters. Management itself flagged that the second quarter benefited from two proprietary reverse mortgage securitizations rather than the usual one, inflating the result, and it pegged the sustainable run-rate in the high-40s cents per quarter, up from roughly 45 cents a quarter earlier. Consensus sits squarely at the low-to-middle portion of that guidance, so a print in line simply confirms the reset management telegraphed. Reported revenue for a mortgage finance company swings with securitization timing and fair value marks, so the earnings line and book value are better guides than the top line.
Longbridge is the most important operating test. Its contribution to adjusted earnings ran around 21 to 23 cents in recent quarters, far above its 12-cent average in 2025. Management pointed to July as a record origination month and noted second-quarter submissions of $870 million versus less than $750 million in the first quarter, which implies a strong pipeline into the back half. Confirmation would look like third-quarter originations comfortably above the $590 million posted last quarter and a Longbridge contribution holding near the 20-cent level even with only a single securitization. Weakness in traditional HECM volumes, which rising rates were already pressuring, would be tolerable if proprietary reverse lending keeps carrying the load.
The quarter should also offer the first look at the residential special servicer acquisition, which was expected to close in the period. Investors will want to know whether it closed on schedule, how it is accretive, and how it fits alongside a forward servicing portfolio that management said had appreciated enough to make the company a more natural seller than buyer. Securitization pace is another signal: with about $4.0 billion issued in the first half against $4.4 billion for all of 2025, continued volume would support the high-yielding retained tranches that feed earnings. Funding improvements, including longer repo terms and a larger slice of non-mark-to-market debt, should ideally hold despite leverage reaching 9.2 times.
Sentiment has barely moved, sitting mildly bearish at about the same level as before the last report, so the stock's decline looks more like a broader repricing than a growing wave of pessimism. Still, at $11.71 the shares trade below their 200-day average of $12.94, sit only about 3% above the post-earnings low of $11.33 and are well under the last reported book value of $13.61 per share. That discount suggests the market doubts the run-rate or worries about credit, which management has kept under watch given softer housing prices and a cooling labor market.
The central question is whether Ellington can deliver high-40s earnings without the help of an extra deal while preserving book value and extending its eight-quarter streak of covering the dividend. Clearing that bar, alongside strong Longbridge volumes and a clean servicer integration, would validate the acceleration story and challenge the market's skepticism. Falling short, or a book value decline tied to credit, would suggest last quarter's optimism ran ahead of the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-07 | |
| Sep-24 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 | |
| Sep-08 | |
| Sep-08 | |
| Aug-24 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Jul-24 |
