DHI Group's ClearanceJobs Surge Faces Its Proof Test As Dice Keeps Shrinking
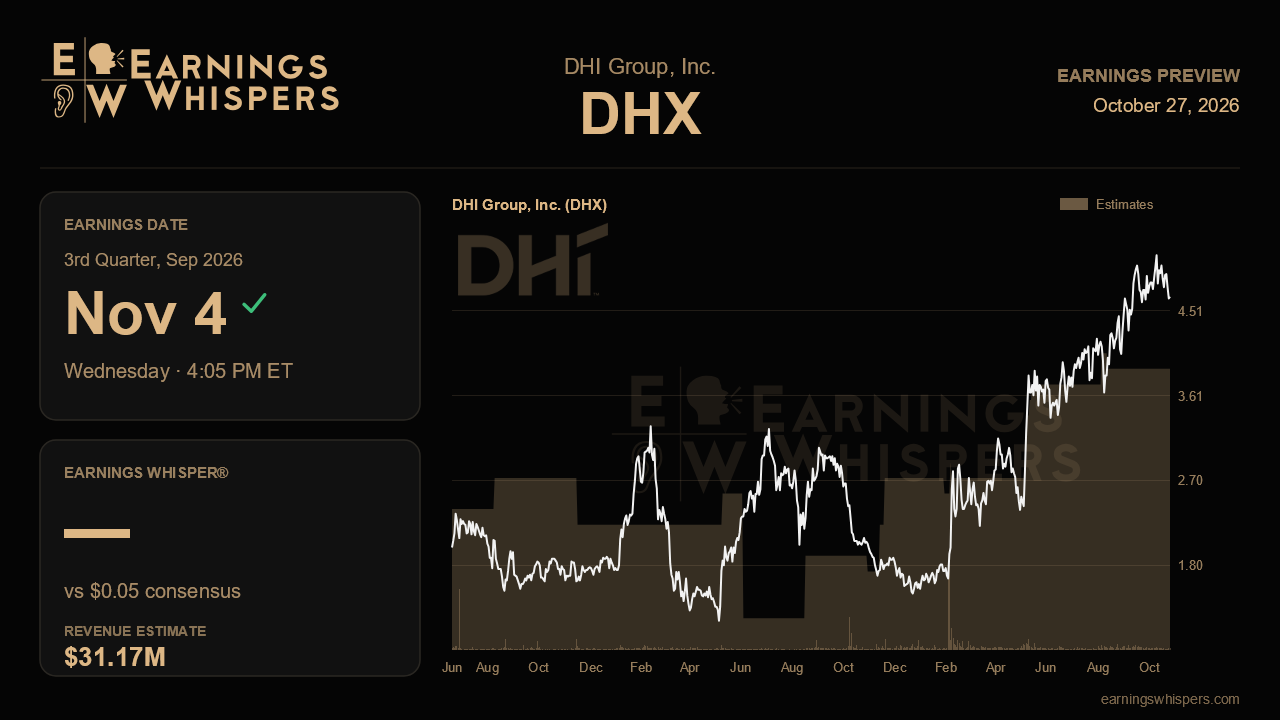
DHI Group heads into its third-quarter report with a story that has finally started to sell itself. Last quarter, ClearanceJobs bookings jumped 24% from a year earlier, the company landed the largest new-business win in its history with Shield AI, and management raised its full-year margin target for Dice. Since then the stock has climbed about 20% while the S&P 500 slipped slightly. The question now is whether the defense-hiring momentum can keep running fast enough to offset a Dice business that management openly expects to keep shrinking.
The Street's bar is modest. Consensus calls for earnings of $0.05 a share on revenue of $31.2 million, which would mean a roughly 17% drop in EPS and a 3% decline in sales from the year-ago quarter. That revenue estimate sits almost exactly at the midpoint of management's $30 million to $32 million guidance range, and it has drifted below the roughly $31.9 million analysts expected when that range was reaffirmed. The full-year outlook of $124 million to $128 million also implies a flat top line. In other words, nobody is asking DHI for growth on a consolidated basis. The real debate is about mix, margins and the trajectory underneath the headline number.
ClearanceJobs carries most of the narrative weight. Revenue there reached $15.6 million last quarter, up 14% from a year earlier, helped by the Point Solutions Group acquisition, which is adding about $2 million a quarter and growing sequentially. Organic bookings rose 7%, and management reiterated a path to double-digit organic revenue growth. With the pipeline at its highest level in more than five years and new-business sales up roughly 75%, investors should reasonably expect bookings growth to stay well into double digits and retention to hold near last quarter's 110%. A sharp deceleration in bookings, or signs that organic growth is fading once the acquisition laps, would undercut the idea that the expanding universe of defense-tech employers is translating into durable demand. It is also worth noting that if CJ keeps growing while Dice contracts, ClearanceJobs could soon become the larger of the two businesses, a symbolic shift in how DHI should be valued.
The tradeoff is margin. CJ's adjusted EBITDA margin slipped to 39% last quarter from 43% for full-year 2025 as lower-margin services labor from PSG entered the mix. Another step down would not be alarming on its own, but the market will want evidence that dilution is stabilizing rather than compounding. On the Dice side, the bar is about pace of decline, not reversal. Revenue and bookings both fell 14% last quarter, and the package customer count dropped 15%. Validation would look like retention holding around 98%, bookings declines narrowing, and profitability tracking toward the newly raised 24% margin target. Management has tied any eventual recovery to job postings, which rose about 30% last quarter, and to the growing share of roles requiring AI skills. Continued shrinkage in deferred revenue, down 12%, and backlog, down 9%, would signal that the turnaround remains further off.
Sentiment has warmed, moving from 12.0% bearish ahead of last quarter to 4.8% bearish now, though it still leans slightly negative. At $4.66, the stock trades well above its 200-day moving average of $3.44 and sits in the upper half of its post-earnings range, though roughly 10% below the $5.19 high. That rally means some of last quarter's optimism is already priced in.
Ultimately, this report hinges on whether ClearanceJobs' acceleration proves sustainable rather than a single standout quarter. If CJ bookings stay strong, margin dilution levels off and Dice's decline keeps easing, the bifurcated story tilts decisively toward improvement. If CJ momentum cools while Dice keeps bleeding, the recent rerating will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-15 | |
| Aug-14 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Jun-30 | |
| Jun-16 | |
| Jun-10 | |
| Jun-04 | |
| Jun-01 | |
| May-26 | |
| May-12 |
