Diversified Energy's First Operated Rig Puts Its Capital-Light Story To The Test
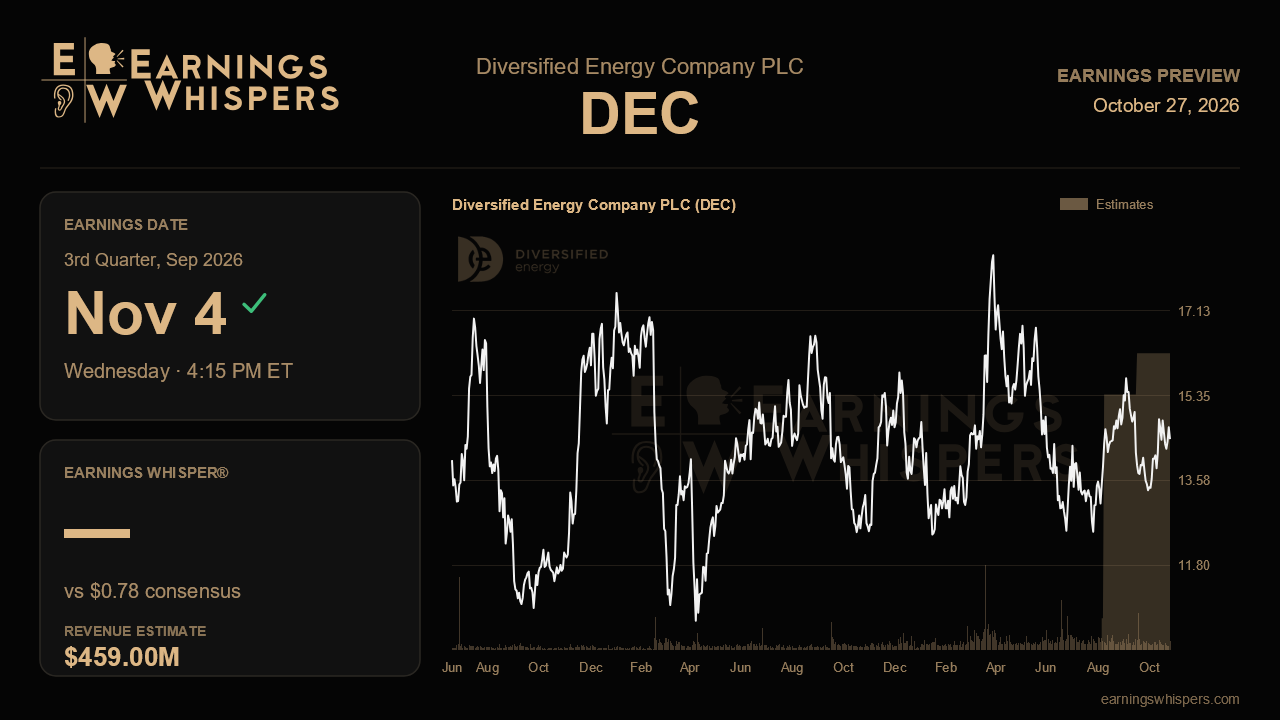
For most of its history, Diversified Energy made money by buying mature, slowly declining gas and liquids wells and squeezing cash from them, leaving the drill bit to others. That changed on the last call, when management said it was standing up a one-rig, company-operated drilling program on its newly acquired Camino acreage in Oklahoma. The third-quarter report, due after the close on November 4, is the first real look at whether that pivot can coexist with the high margins and steady free cash flow that made the stock attractive in the first place.
Wall Street is looking for earnings of $0.78 per share on revenue of about $459 million. Those figures look very different from the prior quarter's loss of $0.29 per share on $811.9 million in revenue, a reminder that reported results for a heavily hedged, acquisitive producer can swing widely from period to period. The more useful anchor is management's own framework: full-year adjusted EBITDA guidance of $925 million to $975 million, raised earlier in the year from $900 million to $925 million, and adjusted free cash flow of roughly $430 million. The company has nudged EBITDA guidance higher on multiple occasions and pushed margins to 68%, so simply reaffirming the range would be acceptable, but the pattern has trained investors to look for at least a tick toward the upper end.
The Camino deal is the swing factor. The $1.175 billion acquisition was structured through an off-balance-sheet vehicle with Carlyle, leaving Diversified to fund only about $210 million while keeping all of the undeveloped acreage, and it was slated to close during this quarter. That makes this report the first chance to see Camino's contribution in the numbers and to judge whether the 1,000 Oklahoma locations, 450 of them economic at $65 oil, translate into a credible drilling plan. Validation would look like EBITDA margins holding near recent levels despite integration costs, early operated wells meeting the company's conservative $65 oil and $3.25 gas assumptions, and a clear explanation of how quickly the rig will run.
Capital spending is where the narrative could wobble. Earlier in the year, total capex for 2026 was guided to $205 million to $235 million. The operated program, combined with three non-operated joint ventures, implies an annual run rate of $250 million to $300 million. If that higher spend arrives without a matching uptick in production or cash flow, the free cash flow target starts to look stretched. Investors should also check that the joint ventures remain on pace to exit the year near 12,500 barrels of oil equivalent per day, the volume meant to offset the base's roughly 10% natural decline, and that leverage stays inside the 2.0x to 2.5x target from the 2.2x last reported, especially with asset-sale proceeds guided down to about $100 million this year from $170 million in 2025.
The market has given management the benefit of the doubt. Shares have gained 6.9% since the last report while the S&P 500 slipped 0.6%, yet sentiment remains modestly bearish and slightly more so than heading into the prior quarter. The stock at $14.44 sits essentially on its 200-day moving average and in the middle of a $12.99 to $15.89 post-earnings range, a narrower band than the previous quarter's. That positioning suggests cautious optimism rather than a crowded bullish bet.
Ultimately, the quarter hinges on whether Diversified can show that drilling is a disciplined option layered onto a low-decline cash machine, not a drift toward the capital-hungry model it long avoided. Steady margins, a reaffirmed or higher EBITDA range, and capex that tracks the stated pace would keep the story intact. Rising spending without visible returns would invite the skeptics to press their case.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Sep-25 | |
| Sep-17 | |
| Sep-16 | |
| Sep-11 | |
| Sep-03 | |
| Sep-03 | |
| Sep-02 | |
| Aug-14 | |
| Aug-11 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
