Energy Recovery Faces Visibility Test As Middle East Delays Keep Guidance On Ice
Energy Recovery heads into its third-quarter report with a problem that no product launch can fix on its own: nobody, including management, can say with confidence when its biggest desalination projects will ship. Guidance has now been withdrawn for two straight quarters, a new leadership team is still settling in, and the stock has been marked down hard. The November 4 release, due after the close, is less about whether the company clears a low bar and more about whether it can begin to restore a sense of timing.
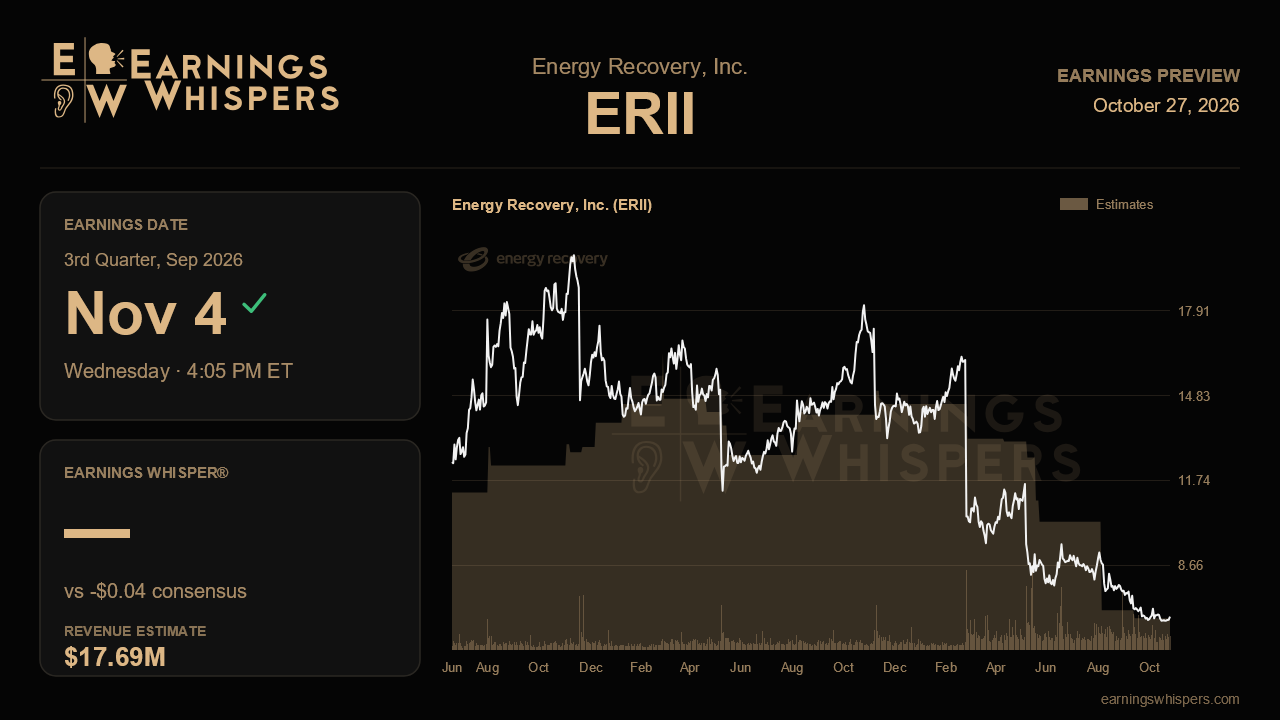
The Street expects a loss of about 4 cents a share on revenue of roughly $17.7 million. That would be a sharp contraction from the year-ago quarter, when the company earned 7 cents on $32.0 million, implying a revenue decline of nearly 45%. Sequentially, though, the forecast calls for a meaningful step up from the $12.0 million and 6-cent loss posted last quarter. With no formal outlook in place, consensus is effectively a guess about how many delayed shipments slip into the period, which makes the revenue line unusually sensitive to the timing of just a handful of orders.
The progression on recent calls explains the caution. A year ago, management reiterated its annual targets and trimmed expense plans on the back of solid sales execution. By the fourth quarter it was flagging an air pocket, with three megaprojects worth about $25 million to $30 million pushed into 2027 and 2026 revenue framed around a midpoint near $45 million. Then the Iran conflict prompted a full withdrawal of guidance, and last quarter management said the delays had become formalized, driven by financing strain, higher geopolitical risk premiums and procurement and logistics hiccups at engineering contractors. It also cautioned that its $27 million megaproject backlog should not be treated as a floor for the second half. Validation this quarter would look like evidence that delayed projects are moving rather than slipping again, along with any willingness from new CEO Alex Buehler and CFO Aidan Ryan to put even a rough framework back on the year. Another round of push-outs, or continued silence on guidance, would challenge the idea that the slump is purely a timing issue.
Beyond megaprojects, two smaller businesses deserve scrutiny. OEM and aftermarket sales, which management expected to prove resilient, ran below last year in the first half, so a rebound there would offer reassurance that the steadier part of the business is holding up. Wastewater was described as quite soft relative to the prior outlook, prompting a leaner sales structure; early signs that the reorganization is producing orders would help. On the positive side, the PXQ650 launch remained on schedule with both small and large deals signed, and the company is leasing a Saudi manufacturing facility expected to lift margins gradually in 2027 and 2028. Updates on 650 order momentum and on capital spending staying within the $3 million to $6 million range would support the longer-term story, as would gross margin holding up despite low volume.
The market has already rendered a harsh verdict. Shares have fallen almost 19% since the last report while the S&P 500 was roughly flat, and at $6.79 the stock sits well below its 200-day moving average of $9.77 and near the bottom of its post-earnings range of $6.55 to $8.92, a range that sits entirely beneath the prior quarter's. Sentiment remains bearish, though slightly less so than before the last report, suggesting pessimism is entrenched but not intensifying.
That backdrop lowers the bar on the headline numbers, but the real test is visibility. If management can show delayed projects converting and offer a credible path for 2026 and 2027, the depressed stock gives room for relief. If the message is again that timing remains unknowable, the structural demand story may keep getting discounted until the shipments actually arrive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-19 | |
| Oct-08 | |
| Oct-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-20 | |
| Jul-17 | |
| Jul-13 | |
| Jun-29 | |
| May-28 | |
| May-08 | |
| May-06 |
