Gulfport's Liquids Ramp Faces Its First Real Test As Dell'Osso Seeks Proof Beyond Tone
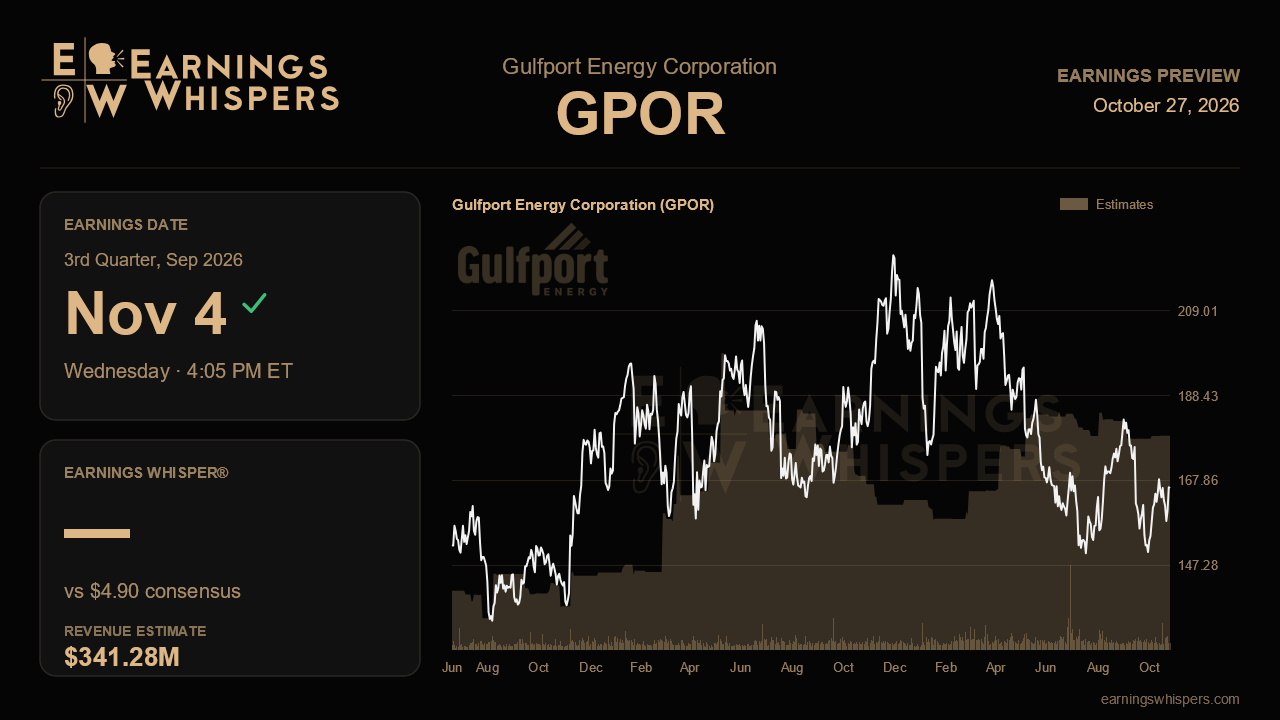
Last quarter, Gulfport Energy's new chief executive, Nick Dell'Osso, made his debut with a confident pitch built on execution, deeper inventory and a sharp step-up in liquids volumes in the back half of 2026. The third-quarter report, due after the close on November 4, is the first set of numbers that can show whether that pitch holds up. Management told investors that second-half liquids would run more than 50% above first-half levels. That promise now has to start showing up in the results.
The Street is setting a demanding bar. Consensus calls for earnings of $4.90 per share, up about 57% from $3.13 a year ago and well above the $3.76 posted last quarter. Revenue, by contrast, is expected to fall roughly 10% from a year earlier to $341.3 million, though that would still be a modest gain from the prior quarter's $323.2 million. The gap between falling sales and sharply higher earnings is the key point in this setup. Analysts are not counting on volume or price to carry the quarter. They are counting on better margins and a richer product mix to turn a smaller revenue base into much more profit per share. That leaves little room for slippage on costs or realized prices.
Several claims from the last call can now be checked. The first is liquids. If the second-half ramp is on track, the quarterly mix should shift clearly toward liquids, and production should land comfortably within the reaffirmed range of 1.03 to 1.055 Bcfe per day. The second is pricing. Management had narrowed its full-year gas differential to $0.15 to $0.30 below Henry Hub and pointed to tighter in-basin pricing, which it tied to early demand from data centers. Realizations near the favorable end of that band would support the idea that Appalachian pricing is improving even with softer benchmark gas. The third is well costs. The new Marcellus pad came in about 25% cheaper per foot to drill and complete, and evidence that those savings are repeatable would do more for the efficiency story than any single good pad. Per-unit operating costs also matter. They were guided slightly higher this year because of the liquids mix, so a reading above the $1.23 to $1.34 range would undercut the margin case.
There are also loose ends that could shape how the stock reacts beyond the headline figures. Chief financial officer Michael Hodges is departing during the leadership transition, so any update on succession will be noted. Gulfport has lifted its discretionary land budget to $140 million and expects to spend far less on acreage in 2027, which makes free cash flow conversion and any early 2027 framework especially relevant. Dell'Osso has said he wants a steadier capital program that avoids first-half production troughs, but he offered no timeline. Clarity on that goal, or on the review of the Scoop assets and larger-scale deals, would reduce the strategic uncertainty that has hung over the story. The company also gave up about 10% of its firm transportation because of its outlook for the M2 market, so commentary on that market bears watching.
Market positioning looks cautiously improved rather than enthusiastic. Sentiment remains on the bearish side but has eased since the last report. The shares are up 5.7% since then, beating the S&P 500 by about five percentage points. Even so, at roughly $166 the stock sits below its 200-day moving average near $179. It is trading in the middle of its post-earnings range of about $150 to $183, well short of a breakout.
In the end, this report comes down to whether the liquids ramp and the margin gains it promised arrive together. A clear rise in liquids volumes with steady costs and tight differentials would turn the new CEO's confident tone into evidence. A soft ramp would leave the elevated earnings estimate looking ahead of the operations.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-21 | |
| Sep-25 | |
| Aug-04 | |
| Aug-03 | |
| Jul-20 | |
| Jun-29 | |
| Jun-26 | |
| May-05 | |
| May-05 | |
| Apr-21 | |
| Mar-09 | |
| Mar-05 | |
| Feb-28 | |
| Feb-25 |
