GRAIL's Doubled Stock Faces A Test Of Volume Growth, Pricing And FDA Timing
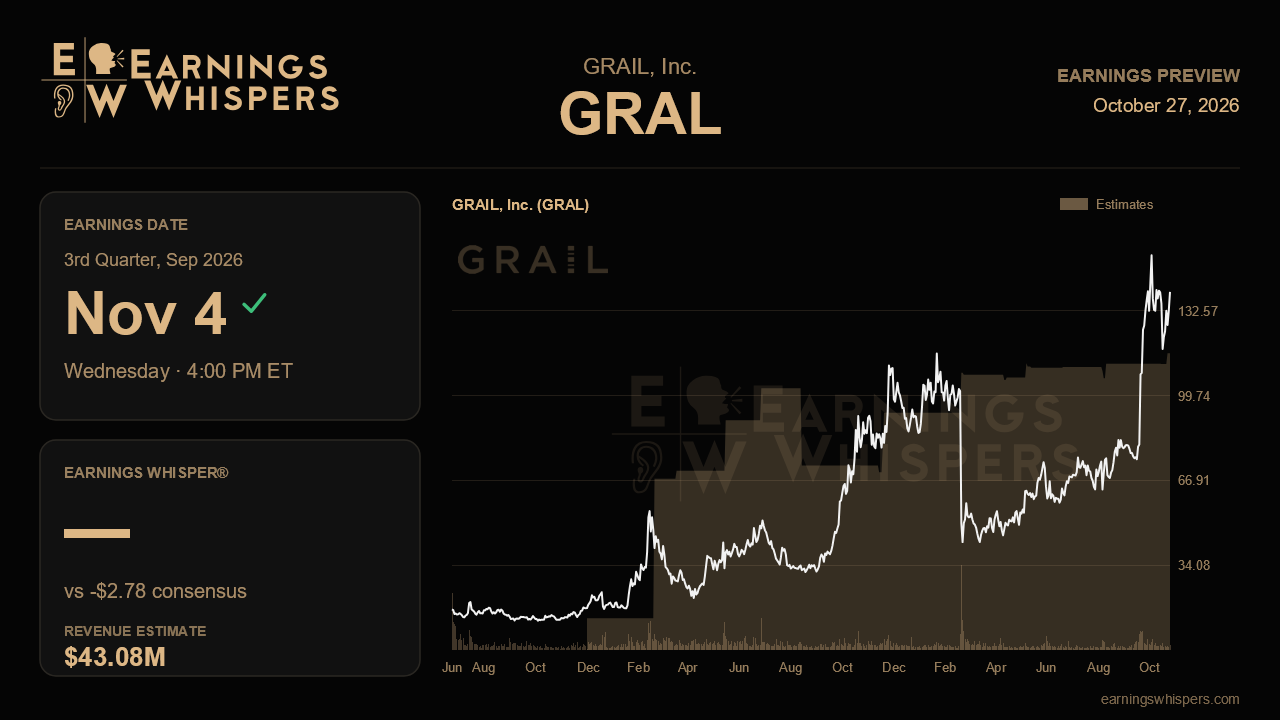
GRAIL heads into its third-quarter report with a share price that has more than doubled since its last update, a gain driven far more by regulatory hope than by anything the income statement has shown so far. That leaves the company in an unusual spot. The quarterly numbers matter, but the commentary around the anticipated FDA advisory committee, and whether early 2027 still looks realistic for approval, may matter more to how the stock trades after the close on November 4.
The Street is looking for a loss of $2.78 per share, wider than the $2.46 loss a year ago and the $2.56 loss last quarter. Revenue is expected to reach about $43.1 million, up 21.2% from a year earlier. That is still solid growth, but it is a step down from the 26% pace of the second quarter, and it implies sales slightly below the $44.7 million GRAIL posted last quarter. The forecast also sits just under the low end of management's reaffirmed full-year growth range of 22% to 32%. Since the first half grew about 30%, the company can still land comfortably inside that range, but analysts are clearly baking in some deceleration.
The likely reason is pricing. Management flagged that average selling prices are drifting toward roughly $700 as planned employer discounts take hold. GRAIL sold 61,000 tests last quarter, up 35% from a year earlier, after a 50% jump in the first quarter. If volume keeps compounding in the mid-30% range while price slips, a revenue figure near consensus would be a reasonable outcome. The more telling number is volume itself. The expanded sales force was only fully deployed after ASCO, the company added about 1,000 new ordering providers in the second quarter, and the Priority Health deal began opening employer coverage in July. This is the first quarter where all three should show up together. Test volume that reaccelerates would validate the commercial story; volume growth that keeps slowing would suggest rival multi-cancer tests, which management spent unusual time rebutting last quarter, are causing more than just confusion.
Margins and losses deserve a close look too. Adjusted gross profit grew faster than revenue in each of the past two quarters, a sign of operating leverage. With prices falling and the high single-digit Illumina royalty set to resume at the end of the fourth quarter, any slippage in gross profit growth now would raise questions about 2027 economics. Meanwhile, net loss improvement slowed sharply last quarter, and the wider consensus loss suggests spending on the sales build and FDA preparation is not easing yet. Investors should want to see that spending translating into volume, not simply widening the gap.
Sentiment has swung from clearly bearish ahead of the last report to modestly bullish now, and the stock's 106 percentage point lead over the S&P 500 says the market has already priced in a good deal of regulatory progress. At about $140, shares sit far above their 200-day moving average near $77 but roughly 16% below the post-earnings high of $166, suggesting some of the enthusiasm has already been tested. Any hint that FDA leadership changes or panelist scheduling could push the advisory meeting into 2027 would hit a stock this extended hard. Updates on the Samsung partnership in South Korea and the stalled NHS discussions after the Gallery trial missed its primary endpoint are secondary, but still relevant.
Ultimately, the report needs to show that GRAIL's commercial engine can keep growing volumes fast enough to outrun price cuts, while management keeps the FDA timeline on track. If both hold, the rally has a foundation. If either cracks, the doubling in the share price leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-05 | |
| Oct-01 | |
| Sep-30 |
Why Grail Stock Skyrocketed Nearly 70% In A Week. What To Watch Next.
GRAL
Investor's Business Daily
|
| Sep-24 | |
| Sep-24 |
Grail Surges After FDA Advisors Back Its Cancer-Finding Blood Test
GRAL +15.38%
Investor's Business Daily
|
| Sep-23 | |
| Sep-23 |
Grail's Multi-Cancer Blood Test Gets FDA Committee Vote for Premarket Approval
GRAL
The Wall Street Journal
|
| Sep-23 | |
| Sep-23 | |
| Sep-23 |
