DMC Global Blows Past Estimates On Broad Margin Gains, But Tariff Refunds And A Seasonal Q4 Step-Down Temper The Beat
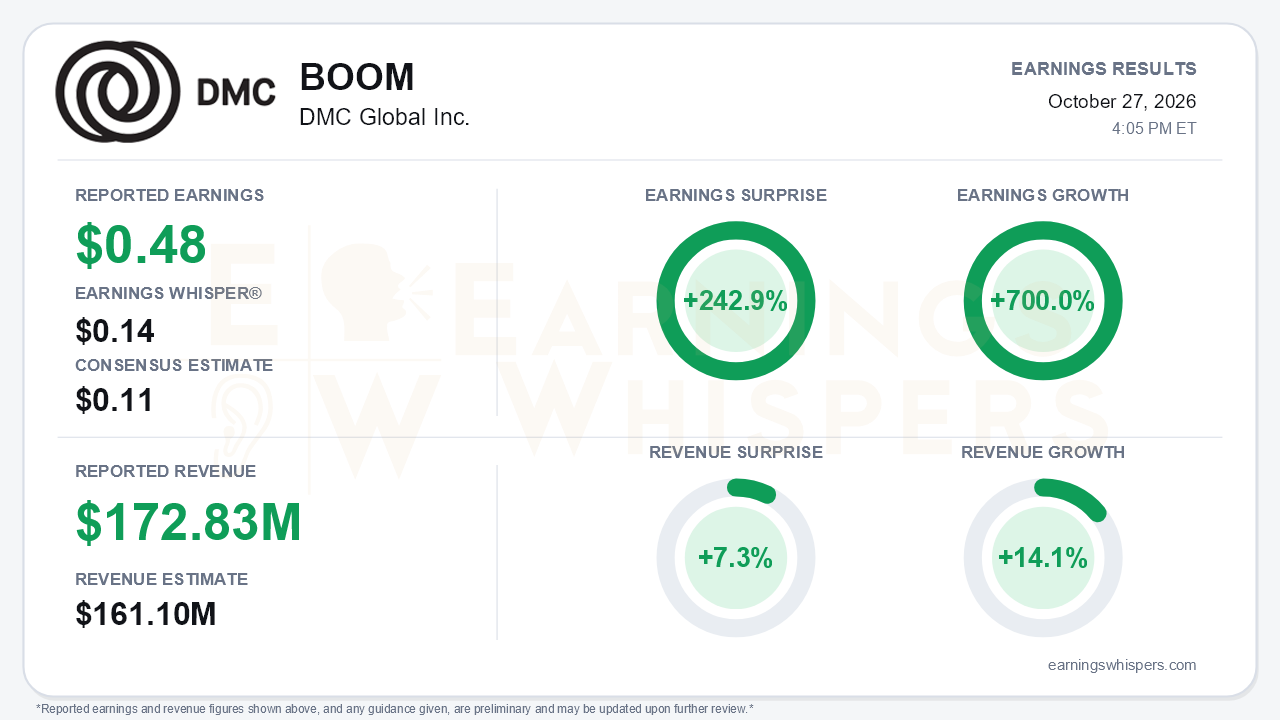
DMC Global delivered its strongest quarter in some time. Adjusted earnings of $0.48 per share topped the $0.11 consensus by 242.9% and cleared the $0.14 Earnings Whisper number by a wide margin. Revenue of $172.83 million beat the $161.1 million consensus by 7.3%. Earnings grew 700.0% year over year against an adjusted loss in the prior-year quarter, and revenue rose 14.1%. On a GAAP basis, net income attributable to DMC was $9.7 million, or $0.59 per diluted share, versus a $3.1 million loss a year ago. The beat is real and broad, but it was not entirely operational. That is the central tension: a genuine self-help story is being amplified by one-time help and set against a Q4 outlook that steps down.
The quality of the beat deserves scrutiny. DynaEnergetics received $5.4 million in tariff refunds in the quarter, up from $1.5 million in Q2. The adjusted EPS figure does not strip those refunds out. Gross margin jumped to 26.9% from 21.9% in Q2, and roughly 10 points of improvement at Dyna was partly flattered by the refunds. A light $1.2 million tax provision on $13.3 million of pretax income also helped. Still, the underlying picture holds up. Excluding the refunds, adjusted EBITDA attributable to DMC was $13.6 million. That was above the top of the $10-$13 million guide, up 59% year over year and 48% sequentially. It also continues a steep climb from $3.9 million in Q1 and a loss in Q4 2025.
What changed beneath the surface is that all three segments expanded margins at once:
- **Arcadia:** Adjusted EBITDA margin reached 14.7%, versus 13.6% in Q2 and 6.9% in Q1. Sales rose 25% as the unit regained short-cycle commercial and high-end residential share.
- **DynaEnergetics:** Excluding refunds, margin improved to 9.7% from 6.2% in Q2 and 4.6% in Q1, even though sales slipped 3%. Cost-outs and a better mix did the work, including first contributions from enhanced geothermal and a newly disclosed defense business of about $0.75 million in drone-related detonators and charges.
- **NobelClad:** Sales rose 38% and margin hit 15.9%. The quarter benefited from a large petrochemical order and the resolution of supply-chain problems on a defense order that fully shipped.
Cash generation was the other standout. Free cash flow of $16.6 million, against an operating cash outflow in Q2, cut net debt to $13.7 million, the lowest since the 2021 Arcadia deal.
The forward catalysts are tangible but modest in scale. NobelClad's backlog rose to $72.4 million from $63.5 million, including a quarterly record $16 million in U.S. Navy vessel orders, and its 12-month book-to-bill ratio was 1.19. Defense and geothermal give DynaEnergetics diversification beyond North American completions. Management was careful, however, to cap expectations:
- **Construction:** The CEO called the market "truly terrible," the worst since 2008-09, with interest rates still rising.
- **Arcadia share gains:** Further recapture is now at "diminishing returns."
- **Dyna margins:** Management described them as sustainable but not scalable. Dyna Americas volume declined despite higher rig counts.
- **Defense revenue:** It was flagged as a non-recurring "bluebird," and analysts were told to haircut Dyna margins by 50-100 basis points.
- **Arcadia put option:** The call did not address the 40% noncontrolling-interest put, exercisable since September, which carries potential redemption obligations and dilution risk.
Guidance is where the story cools. Q4 sales are guided to $154-$164 million, well below Q3's $172.8 million. Adjusted EBITDA is guided to $10-$13 million, the same range given for Q3 and a step down from the $13.6 million ex-refund result. Management attributes the decline to seasonality, a roughly two-week shutdown of a California finishing facility in late December, fewer large long-cycle projects, aluminum volatility and tight builder labor. The outlook also excludes any escalation in Middle East supply-chain disruption. Earnings Whispers characterizes the guide as in-line. That is reasonable on its face, but it means the Q3 upside is not being extrapolated.
Investor sentiment improved modestly into the report, rising to 0.27 from 0.21. That is a mild positive shift, not enthusiasm. The tape has been far less forgiving. Shares were $5.37 ahead of the release, down 23.3% since the open after the July report and 18.3% below the 200-day moving average of $6.57. The stock sat just 6.9% above its October 20 inter-earnings low of $5.02 and 31.6% beneath the August 7 high of $7.85. Price and AVWAP trend readings remain negative. The market has been pricing a deteriorating macro backdrop, not the margin recovery now visible in the numbers.
The bottom line is that DMC proved its cost and commercial initiatives are working across every segment. It also produced cash and repaired the balance sheet faster than skeptics expected. Bears still have legitimate ammunition: refunds inflated the headline, management itself says the easy self-help gains are largely captured, Q4 guidance steps down, and construction demand is described in crisis terms. With the stock entering the report near its lows, the setup favors a market that rewards evidence of durability over one strong quarter.
Read our earnings preview for DMC Global Inc.: https://www.earningswhispers.com/article/BOOM/20742
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jun-22 | |
| May-01 | |
| Apr-30 | |
| Apr-30 | |
| Apr-24 | |
| Apr-07 | |
| Feb-24 | |
| Feb-23 |
