Rocky Brands Raises Guidance Again As Sales Accelerate, But Tariff Windfalls Inflate The Margin Story
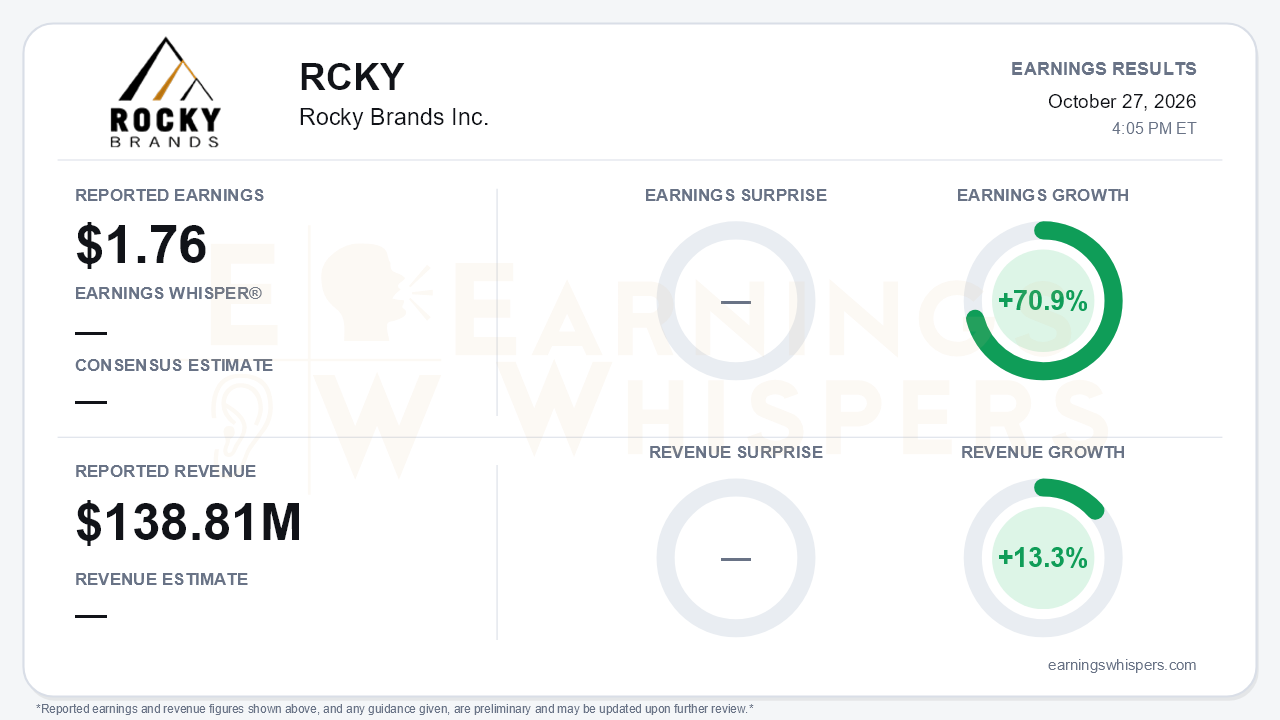
Rocky Brands (NASDAQ: RCKY) delivered a third straight quarter of accelerating revenue and its second consecutive beat-and-raise. Adjusted EPS rose 70.9% year over year to $1.76 on revenue of $138.81 million, up 13.3%. GAAP EPS was $1.69 versus $0.96 a year ago. No consensus estimate was supplied, so the case rests on the trajectory and the guidance. Both moved the right way. Sales growth climbed from 9.1% in Q1 to 12% in Q2 and 13.3% in Q3. Management also lifted full-year revenue growth guidance for the third consecutive call, to roughly 10.5% from about 8.5% in Q2 and 6% at the start of the year. The central tension is that much of the earnings upside came from tariff items that will not repeat. The demand acceleration, by contrast, looks real.
The quality of the margin expansion deserves scrutiny. Reported gross margin jumped 480 basis points to 45.0%. The company attributed the increase primarily to $2.5 million of IEEPA tariff refunds and a temporary $3.5 million benefit from selling free-trade-zone inventory that carried no incremental tariffs. Together that is $6.0 million of the $62.5 million gross profit. Stripping out tariff effects, gross margin was 40.7%. That is roughly 200 basis points better than Q2 but only modestly above last year's 40.2%. Underneath, operating expenses grew faster than sales, rising to 31.4% of net sales on an adjusted basis from 30.1%. The drivers were outbound logistics tied to the Retail mix, heavier digital advertising, higher fuel costs and higher incentive compensation. Adjusted operating margin of 13.6% versus 10.1% looks impressive, but the improvement is mostly tariff-driven rather than operating leverage.
The top-line story is cleaner and broader. Wholesale grew 11.8% to $99.6 million, an acceleration from 7.9% in Q2 and 4.8% in Q1. Retail rose 20% to $35.4 million. Branded DTC websites grew in the low-30% range after a shift to customer-acquisition-cost-based digital advertising. Durango, Muck and XTRATUF all posted double-digit gains, Lehigh grew low double digits, and the Rocky Western line is reviving through the Ride LTE collection. Durango is gaining doors and shelf space at large Western and farm-and-ranch retailers. There were soft spots:
- Georgia Boot declined against a bulk-order comparison.
- XTRATUF wholesale moderated to high single digits after the company cut off international distributors that were diverting product.
- Ex-tariff wholesale gross margin slipped 90 basis points year over year on mix.
The guidance raise needs to be read carefully. Reported full-year EPS guidance rose to about $5.30 from about $5.00. Normalized EPS guidance, however, held at roughly $4, unchanged from Q2. The entire raise in reported earnings is therefore tariff-related, while the higher revenue outlook is being absorbed by cost pressure. Normalized gross margin guidance did tick up to about 41% from 40%, yet the long-term target remains 40%. The guide also implies Q4 growth moderating to around 8%. That reflects two headwinds: a difficult DTC comparison against last year's snow-driven Muck Cyber Week, and an expected ~$2 million decline in contract manufacturing as military contracts wind down.
Forward catalysts are tangible:
- Spring 2027 bookings are up across Durango, XTRATUF (including a new sandal program) and Georgia BOA styles.
- A USA-made, first-to-market BOA design partnership launches in early 2027.
- Two new commercial military bids, with the U.S. Air Force and an international government, ship early next year.
- Fire boots were recertified under new NFPA standards ahead of Q4.
Bears have legitimate ammunition for 2027, though:
- The roughly $13.5 million net tariff benefit in 2026 will not recur.
- Management expects incremental Section 301 tariffs.
- Freight and oil-linked component inflation point to mid-single-digit product cost increases, and 2027 pricing is still undetermined.
- Commercial military sales missed plan on raw-material shortages and diverted government budgets.
The balance sheet continues to improve. Total debt fell 16.6% year over year to $116.0 million, down from $122.4 million in Q2, which lowered interest expense. Inventory was 2.0% below last year. Two items are worth watching. Other receivables swelled to $11.2 million, mainly the uncollected tariff refund, so part of the windfall has not yet turned into cash. Trade receivables also rose to $97.0 million from $82.6 million, outpacing sales growth. Investor sentiment readings and a current share price were not available, which limits the read on market positioning. For reference, the stock opened at $49.49 after the July report, comfortably above the current 200-day moving average of $40.69. That suggests the market had already begun rewarding the acceleration story heading into this print.
The bottom line is that Rocky Brands is executing well on demand. Revenue and wholesale growth are accelerating, DTC is booming, and spring bookings support continued momentum. But the headline earnings leap and the reported EPS raise lean heavily on non-recurring tariff benefits, and normalized earnings guidance did not move. The investment debate now shifts to 2027. The question is whether volume growth, pricing and the new product and military wins can offset the loss of a $13.5 million tariff tailwind, new Section 301 exposure and rising sourcing costs.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-20 | |
| Oct-19 | |
| Oct-02 | |
| Sep-14 | |
| Sep-14 | |
| Aug-17 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-21 | |
| May-20 | |
| May-18 |
