Ribbon Beats On EPS As The Second-Half Inflection Arrives, But A Shrinking Full-Year Outlook And A Thinning Balance Sheet Keep Pressure On The Story
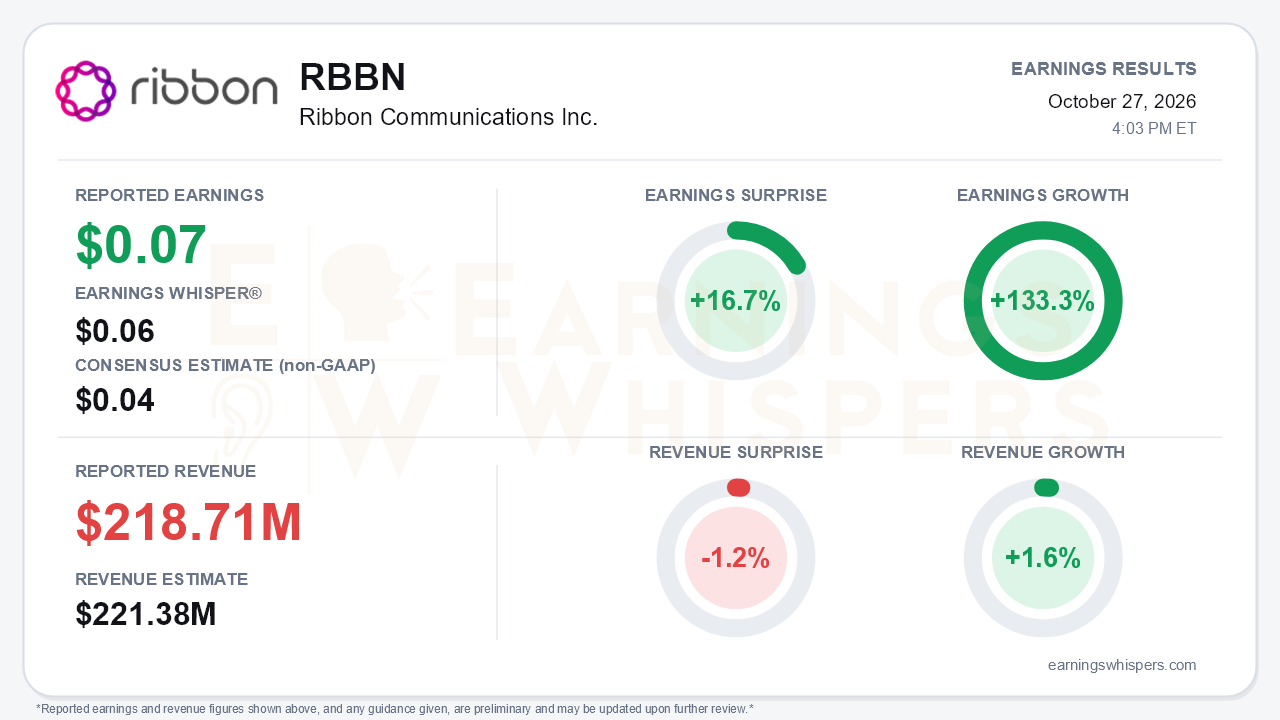
Ribbon Communications delivered the sequential rebound it had promised, though not quite the quarter it had guided to. Third-quarter non-GAAP earnings of $0.07 per share beat the $0.04 consensus and the $0.06 Earnings Whisper number, a 16.7% surprise, and rose 133.3% from a year ago. Revenue of $218.71 million missed consensus by 1.2%. It grew just 1.6% year over year, but that still marks a turn after a first half in which nine-month sales fell from $617 million to $574 million. The central tension is that the quarter confirmed the inflection while the outlook embedded in it got smaller again.
The quality of the beat deserves scrutiny. Revenue jumped 14% sequentially and adjusted EBITDA more than doubled to $27 million from $12 million in the second quarter, with non-GAAP operating expenses held at $88 million. On a year-over-year basis, though, the picture is flatter. Adjusted EBITDA slipped from $29 million, and non-GAAP gross margin fell to 50.3% from 52.6%. The tax effect of non-GAAP adjustments added roughly $0.03 per share this quarter versus a $0.01 drag a year earlier, which flatters the triple-digit EPS growth figure. On a GAAP basis, Ribbon still lost $9.1 million, or $0.05 per share. That loss narrowed from $26.9 million in the second quarter and $12.1 million a year ago, but it remains a loss.
The operating story improved on the call:
- **IP Optical Networks** posted a record third quarter of $96 million, up 17% sequentially. U.S. IP optical sales grew more than 150% year over year, and two new U.S. Tier 2 service providers came aboard, including data center connectivity projects.
- **Cloud and Edge** grew 11% sequentially. Segment gross margin widened 210 basis points to 61.9%.
- **Verizon** sales were up roughly 50% from the first-half run rate. That reverses the slow voice-modernization narrative that weighed on the first two quarters, and management pointed to further fourth-quarter gains, faster 2027 migrations and potential Frontier upside.
Management's tone was noticeably more confident than earlier this year.
Bears still have legitimate ammunition. IP optical book-to-bill fell to about 0.82x from 1.6x in the second quarter and 1.5x in the first, even though segment bookings were up 9% year over year. IP optical gross margin dropped 390 basis points year over year, and the segment remains EBITDA-negative. Supply constraints in memory, core silicon and optical line systems could push $5 million to $10 million of fourth-quarter demand into 2027, while component and logistics inflation runs about $2 million per quarter.
The guidance carries a conflict worth spelling out. The fourth-quarter outlook of $233 million to $247 million in revenue and $40 million to $47 million in adjusted EBITDA is in line with expectations and implies year-over-year growth. Combined with year-to-date results, however, it puts full-year revenue at roughly $807 million to $821 million. That is below the $810 million to $840 million range given on the second-quarter call and well short of the original $840 million to $875 million. Implied EBITDA of about $71 million to $78 million sits entirely below the prior $78 million to $88 million range, and far from the original $105 million to $120 million. Management did not reiterate full-year guidance.
The balance sheet makes that slippage matter more:
- Operating cash flow was about -$14 million in the quarter and -$47.9 million year to date.
- Cash fell to roughly $42 million, including restricted cash, despite a $15 million revolver draw.
- Net leverage climbed to 4.4x from 2.3x at the end of 2025.
- The release's risk factors explicitly cite compliance with the credit agreement's maximum net leverage ratio.
A strong fourth-quarter EBITDA print is therefore close to essential.
The market had already priced in deep skepticism. Shares were at $1.34 on the eve of the report, down 41% from the $2.27 open after the July release. They sat about 41% below the 200-day moving average and just 4.5% above the $1.28 52-week low set on October 22. Investor sentiment deteriorated sharply into the print, sliding from -0.19 to -0.76. Sequential growth is now trending positively in the Earnings Whispers trend readings, but price and AVWAP trends remain negative. That gap between improving quarter-over-quarter fundamentals and persistent selling is the setup this report has to resolve.
The bottom line is that Ribbon showed the recovery is real at the sequential level, with Verizon activity returning, new optical logos and margins rising for a second straight quarter. However, a third consecutive step-down in implied full-year targets, cooling optical orders and rising leverage mean the company is still asking investors to trust a back-half-weighted plan. With the stock pinned near its lows and sentiment deeply negative, expectations are low. The fourth quarter now has to deliver on both EBITDA and cash, not just revenue.
Read our earnings preview for Ribbon Communications Inc.: https://www.earningswhispers.com/article/RBBN/20789
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Sep-09 | |
| Sep-01 | |
| Aug-14 | |
| Aug-02 | |
| Jul-28 | |
| Jul-28 | |
| Jul-21 | |
| Jul-16 | |
| Jul-14 |
