Manhattan Associates Beats And Raises As 28% Cloud Growth Outruns A Services Slowdown And Cash-Flow Dip
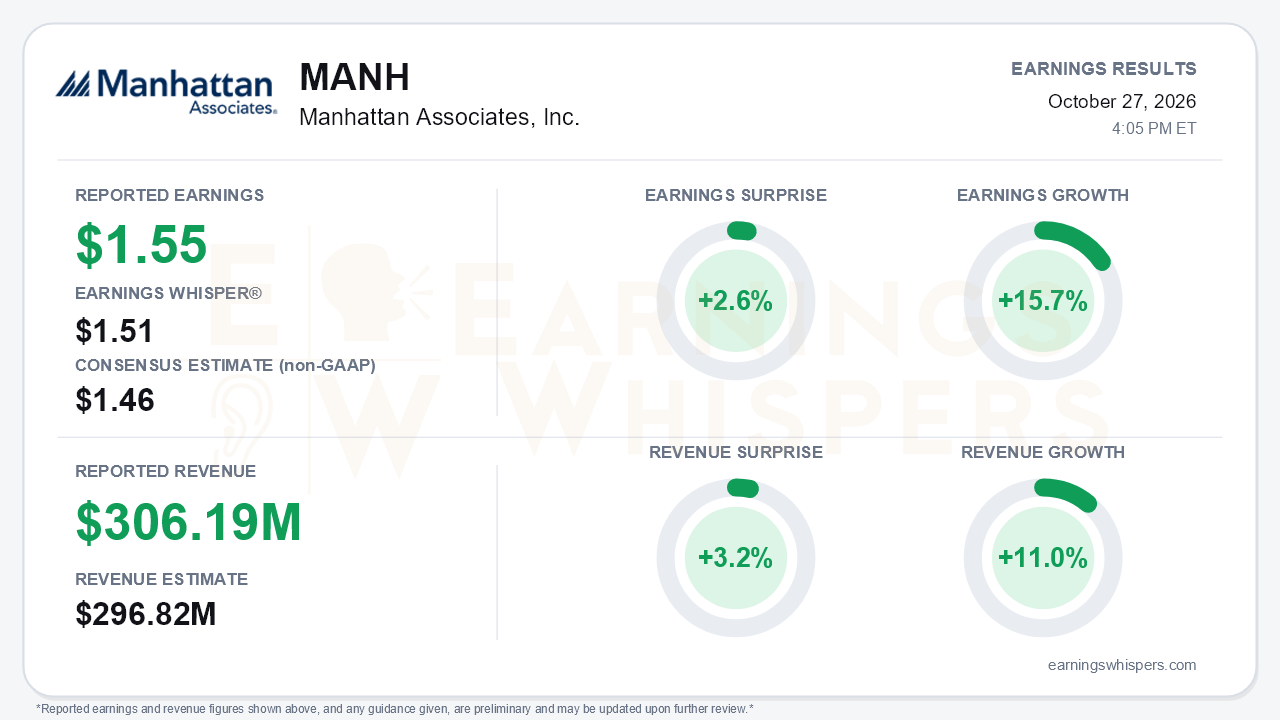
Manhattan Associates delivered the kind of quarter that makes a growth story harder to dismiss. Adjusted earnings of $1.55 per share topped both the $1.46 consensus and the $1.51 Earnings Whisper number, a 2.6% surprise, while revenue of $306.19 million beat consensus by 3.2%. More important than the beat was the direction of travel. Earnings grew 15.7% year over year and revenue rose 11.0%, extending a sequence in which total revenue growth climbed from 7% in Q1 to 9% in Q2 to 11% now. Cloud subscription revenue rose 28% to $134.4 million and surpassed services revenue for the first time. That is the central takeaway: the cloud transition is not just progressing, it is speeding up.
The quality of the beat holds up better than most, though it has caveats. Adjusted operating income rose to $115.2 million from $103.4 million, and the call put the adjusted operating margin at 37.6% against a 36.9% guide. GAAP diluted EPS rose to $1.04 from $0.96, but the GAAP picture is softer over longer periods. Nine-month GAAP EPS of $2.72 trails last year's $2.75, and full-year GAAP EPS guidance of $3.62 to $3.64 implies only about 1% growth, versus 9% to 10% on an adjusted basis. Equity-based compensation climbed to $34.2 million from $27.6 million, and sales and marketing expense jumped to $26.8 million from $18.1 million as Manhattan funds its go-to-market push. Per-share results also benefit from aggressive buybacks. Diluted shares fell to 58.7 million from 61.0 million after $325 million of repurchases this year. Those buybacks helped cut cash to $199.4 million from $328.7 million at year-end.
The call explained what is driving the acceleration. RPO grew 25% to $2.59 billion, up from 23% growth in Q2. Management raised its full-year RPO growth outlook to 21% from its 18% to 20% range, an unusual move given that the target is normally updated only once a year. Manhattan posted a fourth straight record bookings quarter, and year-to-date deal volume already exceeds all of 2025. Win rates stayed above 70%, new logos made up about 35% of new cloud bookings, and partner-sourced deals are up more than fourfold. The new Editions packaging launched in Q3, producing Enterprise Edition wins and a first Essentials deal from outside the existing pipeline. For the first time, management explicitly credited AI with contributing to cloud upside, and more AI deals are going straight to subscription.
Guidance moved higher again. The full-year revenue range is now $1.176 billion to $1.178 billion, and adjusted EPS guidance rose to $5.54 to $5.56 from $5.44 to $5.50 last quarter. Adjusted EPS guidance stood at $5.04 to $5.20 at the start of the year. Management also said current 2027 consensus looks appropriate, including roughly 20% cloud growth and further margin expansion. That is supportive, though it stops short of formal guidance.
Bears still have legitimate ammunition. Services growth slowed to 1% from 4% in Q1 and 3% in Q2 as faster deployments shorten projects. Operating cash flow fell to $68.6 million from $93.1 million a year earlier, and days sales outstanding jumped to 81 from 67 on late-quarter billing. Management attributed the decline to collection timing, but it needs to reverse in Q4. Contract durations are drifting toward about five years, which trims RPO per deal. Roughly half of the Q3 cloud beat came from variable upsells that management does not build into guidance, so not all of this quarter's upside should be assumed to repeat.
The market setup is more demanding than the surprise implies. Investor sentiment swung from -0.185 at the prior report to +0.154, a meaningful shift from mildly negative to modestly positive. Shares have rallied 21.2% from the $195 open after the July report to $236.40. They sit 43.2% above the 200-day moving average and just 2.6% below the 52-week high of $242.63 set on October 23. Most Earnings Whispers trend readings are positive, with sequential growth the neutral exception. Manhattan entered this report having already been rewarded for the acceleration narrative, so the bar was a beat-and-raise, not merely a beat.
The bottom line is that Manhattan cleared that bar on the metrics that matter most: cloud growth, RPO, margins and guidance all moved higher, and early 2027 commentary held up. The open questions are cash conversion, a services line that has effectively stalled, and how much of the cloud upside rests on less predictable upsells. With the stock near its highs and sentiment no longer skeptical, execution on those secondary metrics will likely matter more from here.
Read our earnings preview for Manhattan Associates, Inc.: https://www.earningswhispers.com/article/MANH/20773
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-22 | |
| Sep-22 | |
| Sep-03 | |
| Sep-01 | |
| Jul-29 |
