ZoomInfo's Consumption Pricing Pivot Meets Its First Test As Retention Slips
ZoomInfo heads into its third-quarter report as a company asking investors to trust two stories at once. The first is a shrinking top line, with revenue expected to fall for the year after a sharp guidance cut in the spring. The second is a leaner, more cash-generative business with a fresh AI distribution angle and a pricing overhaul that only began reaching new customers at the end of this quarter. Wednesday's numbers will show which of those stories is gaining the upper hand.
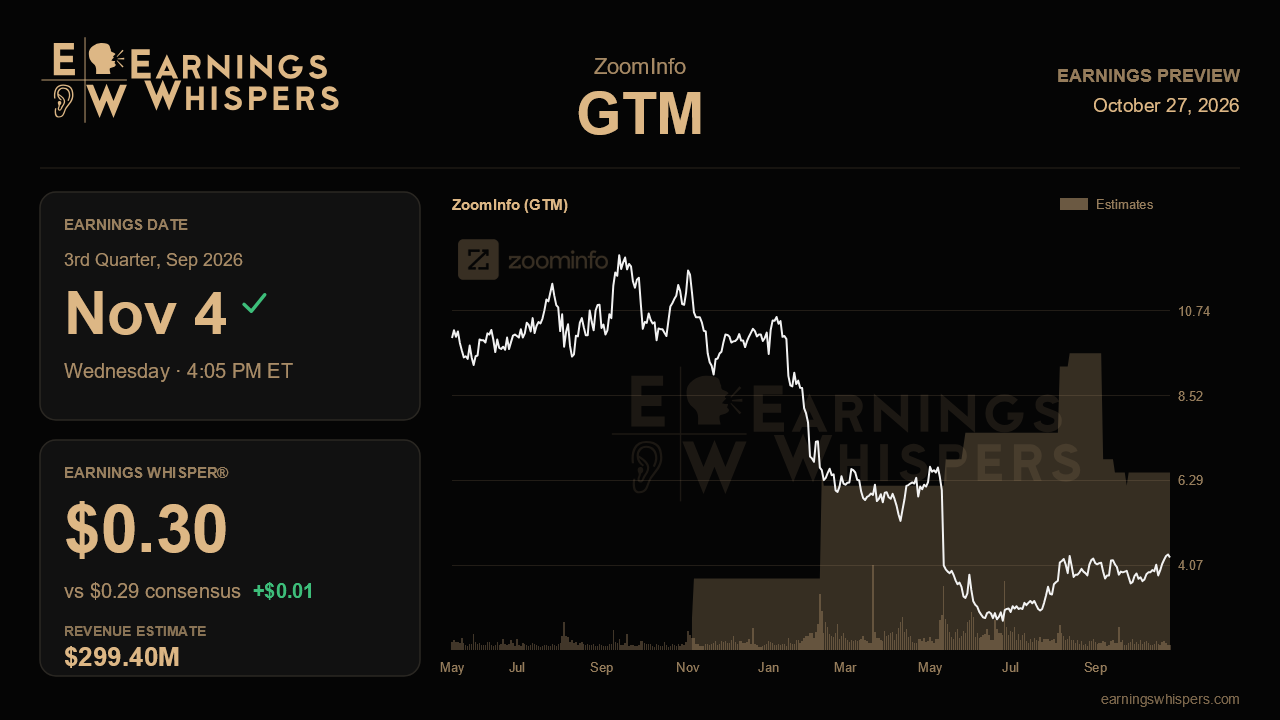
The bar itself is well defined. Analysts expect non-GAAP earnings of $0.29 a share on revenue of about $299.4 million, a decline of roughly 5.9% from the $318.0 million reported a year ago and a step down from last quarter's $310.4 million. Management guided to $0.28 to $0.29 and $298 million to $301 million, so the Street sits at the top of the earnings range and squarely in the middle on revenue. The whisper number of $0.30 is only a penny above consensus, but it signals that investors expect the company's cost discipline to produce a modest beat. With headcount down 15% from a year ago and several hundred more positions slated to go, that expectation is not unreasonable. A revenue figure at or above the top of guidance would matter more, since the top line is where credibility was lost.
The operating metrics behind that revenue deserve the closest scrutiny. Net revenue retention slipped to 89% last quarter after three straight readings at 90%, upmarket contract value growth slowed from 6% to 5% to 3% over three quarters, and the count of customers paying $100,000 or more fell sequentially to 1,891. Management blamed persistent weakness among software buyers, particularly at the lower end of its upmarket base, along with confusion as companies sort out their AI and agentic purchasing plans. Retention holding at 89% or ticking back up, along with stabilization in the $100,000 cohort, would support the idea that the business is finding a floor. Another leg down in either would suggest the spring guidance cut did not fully capture the erosion. The deliberately shrinking downmarket, where contract value fell 12%, matters less as long as the decline stays contained.
There are genuine offsets to watch. The operations and data-as-a-service business has grown around 20% for several consecutive quarters, the million-dollar customer cohort expanded 16%, and the company closed its largest contract ever last quarter. The GTM.AI headless layer, which plugs ZoomInfo's data directly into tools such as Claude, Copilot, Cursor and Gemini, is the newest catalyst, and early adoption commentary will help determine whether it is a real growth channel or a defensive feature. Equally important is how the hybrid consumption pricing launch is landing with new business, because management has already flagged that the migration creates revenue recognition variability heading into 2027. Investors will also want reassurance on the full-year outlook, which was nudged up to $1.207 billion to $1.217 billion in revenue and $1.12 to $1.13 in earnings, plus updates on discounted debt repurchases and the target of $1.25 in levered free cash flow per share entering 2027.
Sentiment has warmed noticeably, swinging from bearish ahead of the last report to moderately bullish now, and the stock has climbed 13% since August while the S&P 500 slipped slightly. At $4.27, shares sit in the upper part of their post-earnings range of $3.50 to $4.48 but remain below the 200-day moving average near $4.93, a reminder that the rebound has not yet repaired the longer-term damage.
That combination makes the report a meaningful test. The rally implies investors believe the worst of the reset is behind ZoomInfo. To keep that thesis intact, the company needs to show that retention and upmarket growth have stopped deteriorating while margins and cash flow keep improving. A clean earnings beat paired with another dip in retention would likely be read as cost cutting masking a weakening franchise.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Oct-23 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-05 | |
| Oct-03 | |
| Oct-01 | |
| Sep-30 |
